NOW Down, EBAY Up: Upside, Downside Movers in the Morning

Upside
– $GKOS +16% (record Q3 sales and a large FY revenue-guidance raise topped expectations)
– $INSM +14% (BRINSUPRI revenue grew 29% sequentially and guidance was raised for both BRINSUPRI and ARIKAYCE)
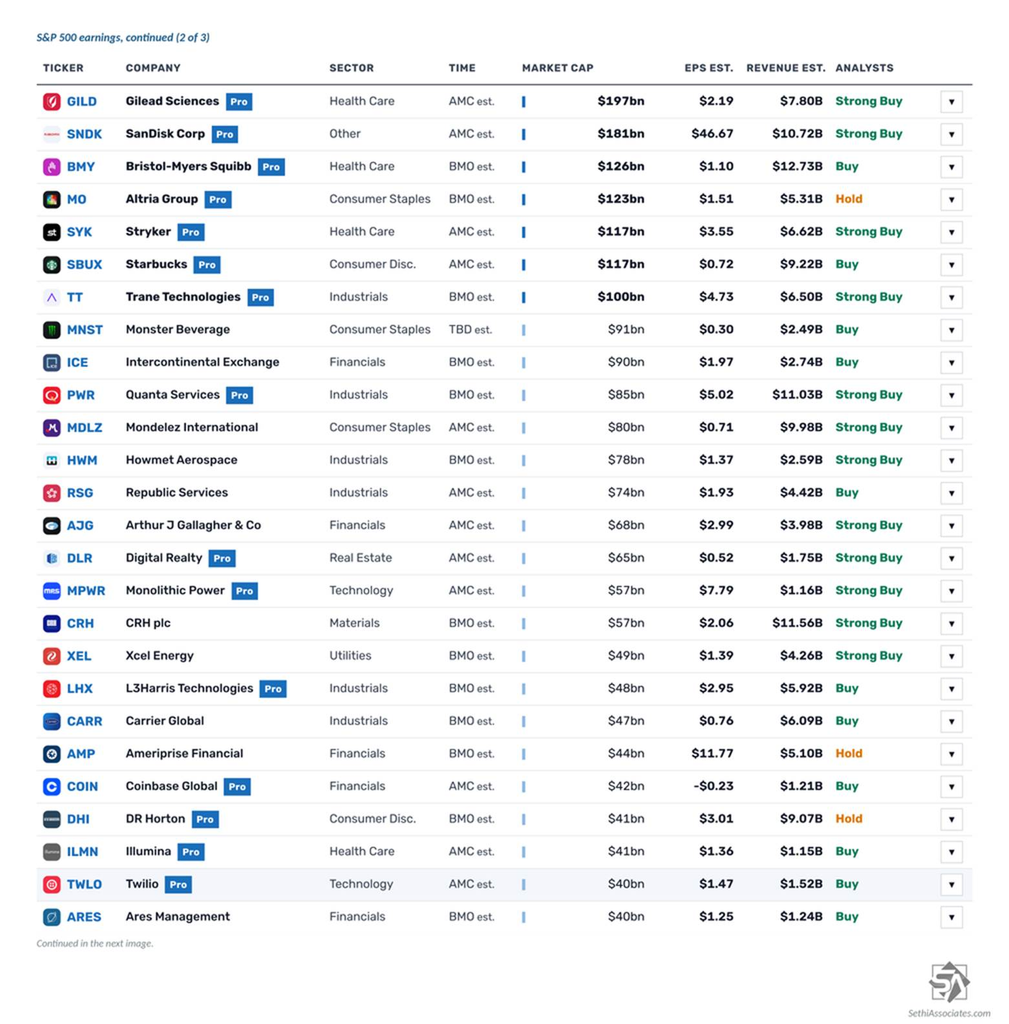
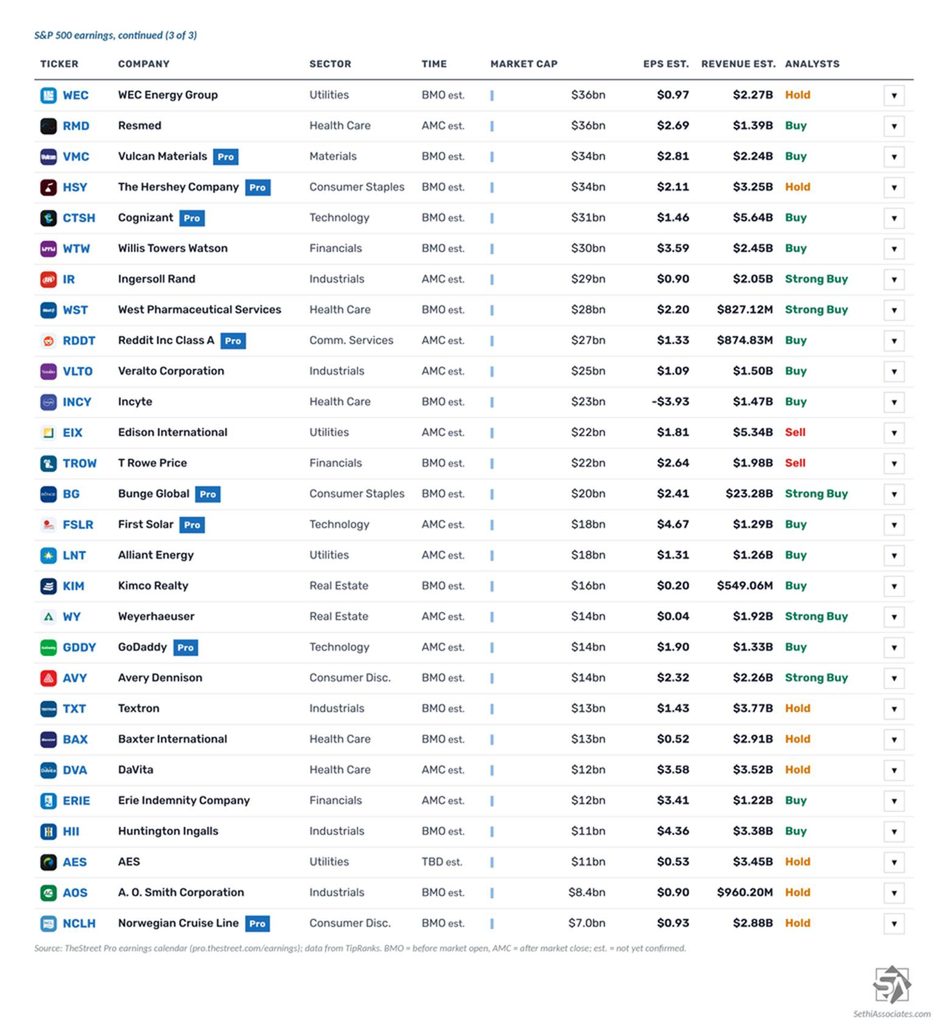
– $NCLH +12% (Q3 results topped guidance and the FY EBITDA and EPS outlooks were raised)
– $CVNA +8.4% (large Q3 revenue beat and accelerating retail-unit growth outweighed an EPS miss)
– $CMG +8.3% (Q3 comparable sales beat expectations despite a modest profit miss)
– $DASH +6.9% (record GOV, revenue and net income alongside an agreed $17B acquisition of CART)
– $LITE +6.9% (MRVL is reportedly in advanced acquisition talks, with a deal potentially announced next week)
– $EBAY +6.1% (Q3 revenue and GMV growth accelerated, reinforcing improving marketplace momentum)
– $HII +5.6% (record Q3 revenue, $32.4B of contract awards and higher FY shipbuilding-revenue guidance)
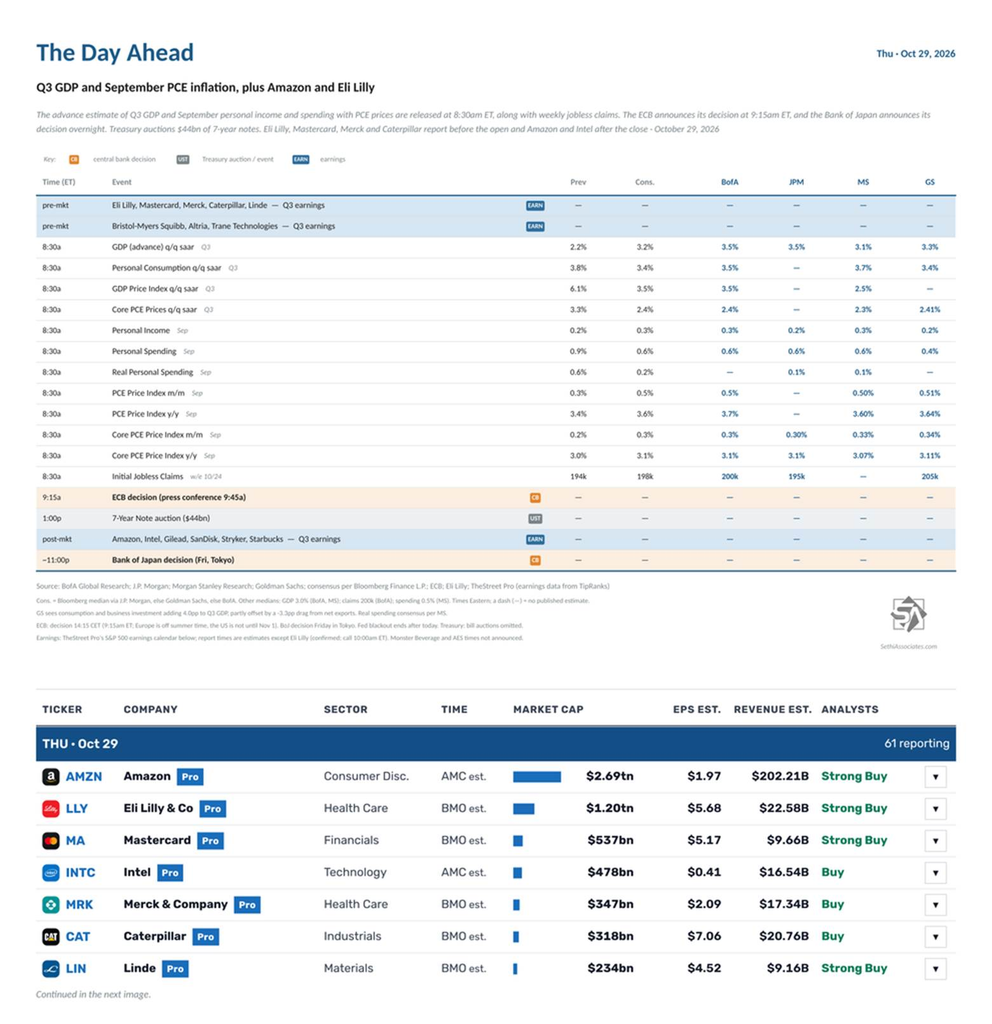
– $LLY +5.1% (annual revenue guidance topped expectations)
– $NVS +3.2% (2026 core operating-income guidance was raised despite a drug-trial write-down)
– $RCL +3.5%, CCL +3.0% (cruise names rise after NCLH beat and raised its FY outlook)
– $MSFT +1.1% (strong cash flow and cloud guidance signaled better returns from heavy AI investment)
Downside
– FTNT -27% (headline beat and raised guidance failed to offset sharply slowing product growth and concerns the refresh cycle is fading)
– NOW -19% (strong topline results were overshadowed by softer forward cRPO expectations and unfavorable renewal phasing)
– HLN -14% (Q3 organic sales missed and FY organic-growth guidance was cut to around 2.5%)
– OSK -13% (quarter missed and FY revenue and EPS guidance were cut as fire-truck production problems persisted)
– MRVL -12% (reported talks to acquire LITE sparked concerns over deal cost and execution risk)
– $CAT -11% (quarter beat, but the margin outlook and durability of AI-infrastructure demand fell short of elevated expectations)
– $GOOGL -11% (Q3 profit and revenue missed as softer search advertising and surging AI spending intensified cash-burn concerns)
– $EGO -10% (2026 gold-production guidance was cut and cost outlooks were raised amid a slower Skouries ramp)
– $CTSH -10% (Q3 beat, but the FY revenue-growth outlook narrowed and Q4 growth guidance disappointed)
– $SCI -8.9% (Q3 earnings missed and guidance was cut)
– $ZS -7.1%, $OKTA -7.5%, $PANW -6.8%, $RBRK -6.8%, $CRWD -6.8%, $SAIL -8.0% (cybersecurity names fall on FTNT’s product-growth slowdown and refresh-cycle concerns)
– $NBIS -6.7%, $CRWV -6.4%, $STRL -6.6% (AI-infrastructure names retreat as $GOOGL’s spending surge renews concerns about monetization and cash returns)
– $HUBS -6.5%, $TEAM -6.9%, $CRM -5.8%, $TYL -5.8%, $WDAY -6.1% (enterprise-software names weaken after NOW’s forward cRPO and renewal outlook disappointed)