Wednesday: The Fed, Alphabet and Amazon

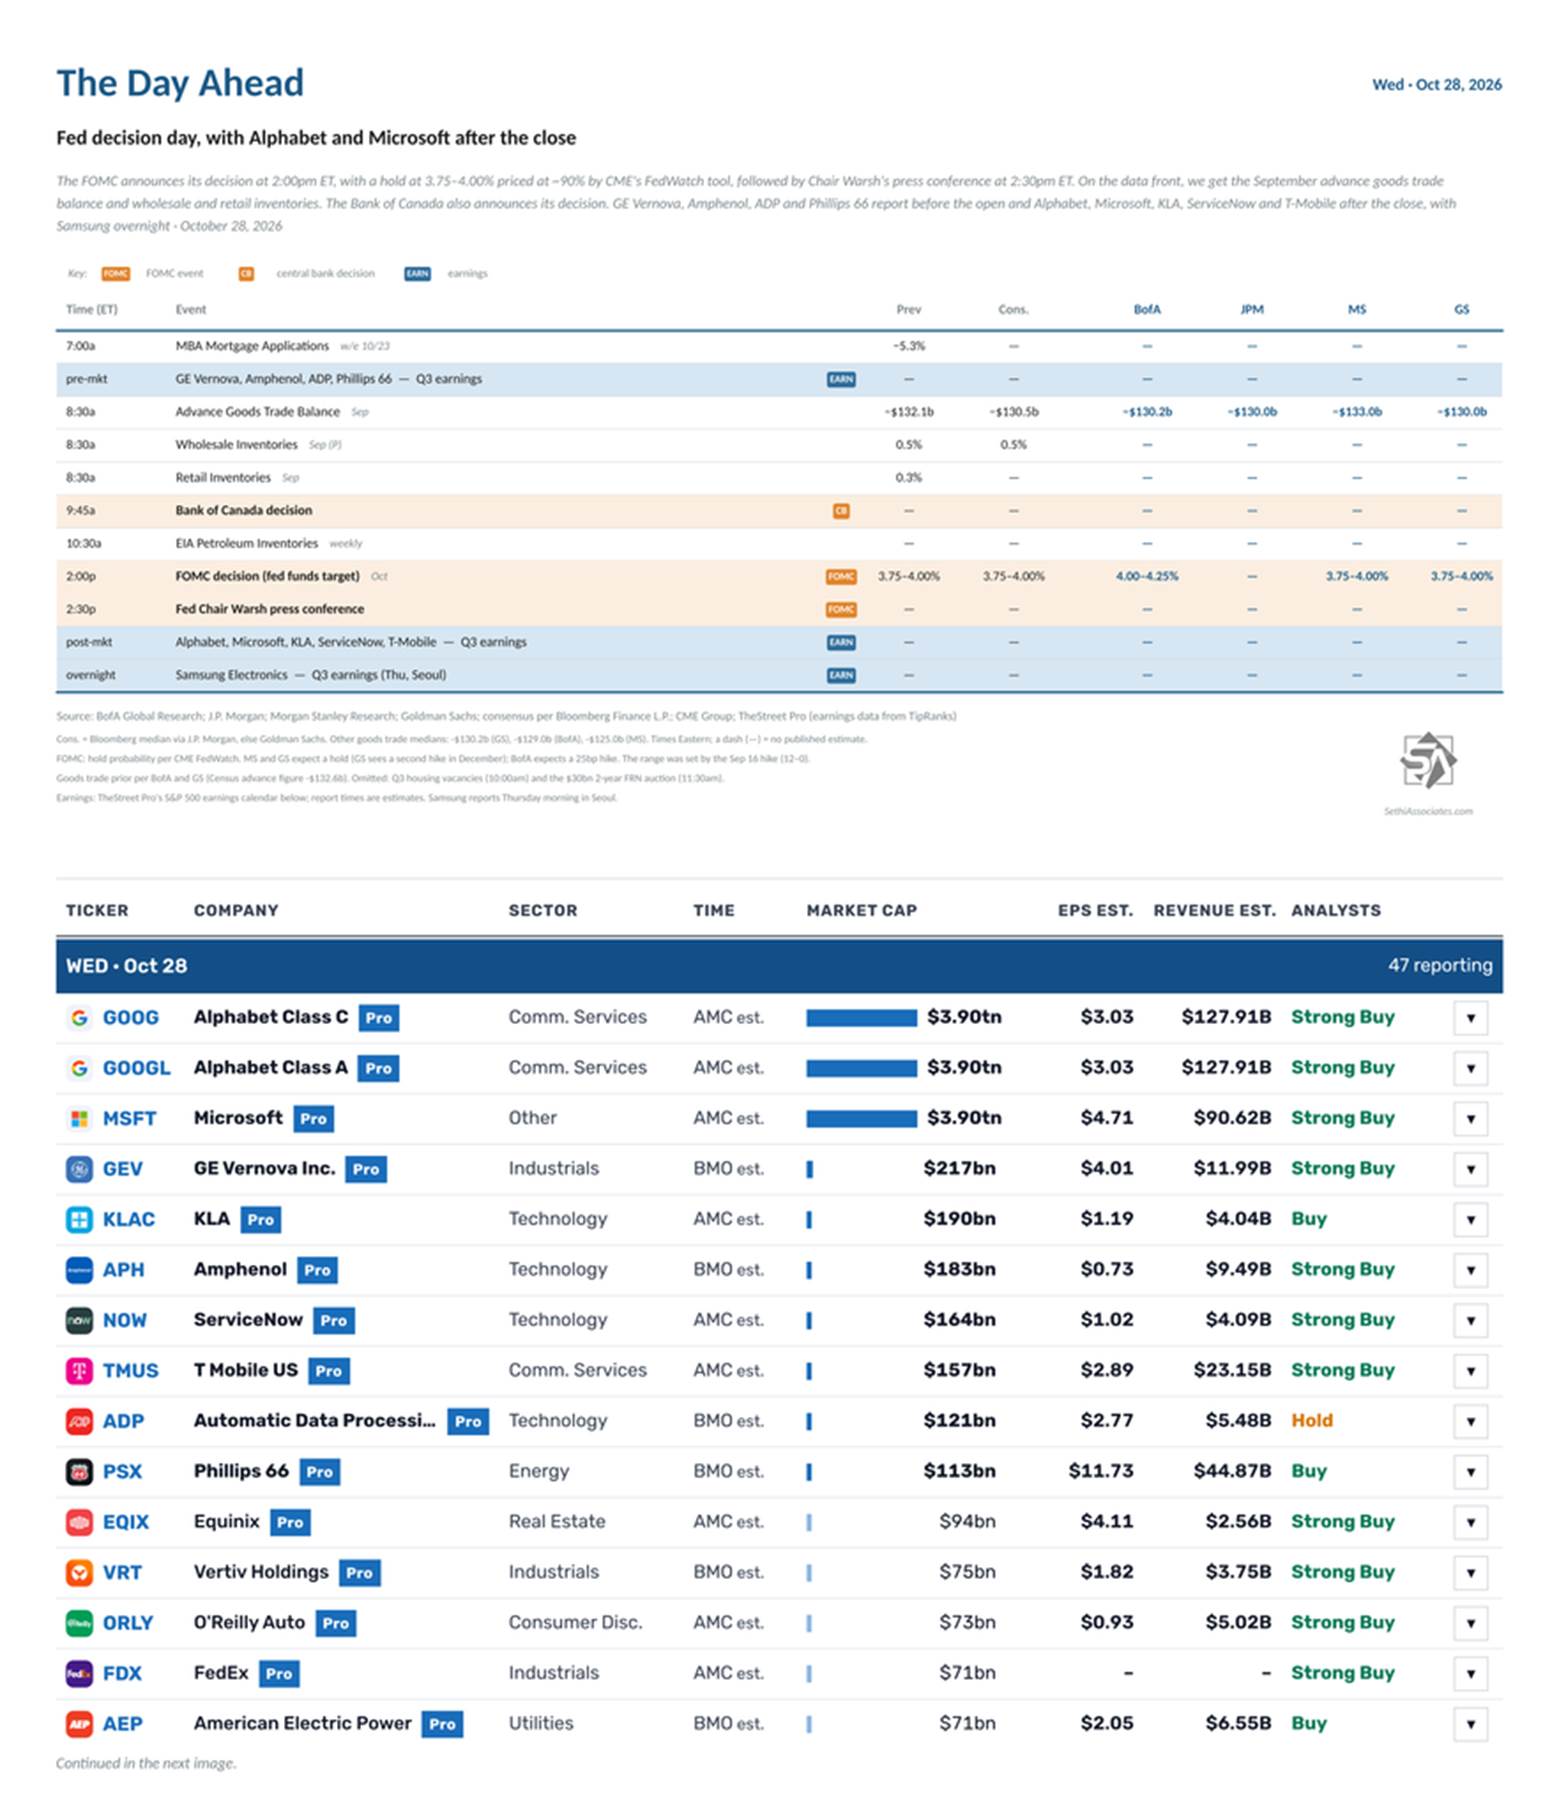
US economic data is light Wednesday, with just the September advance goods trade balance and wholesale and retail inventories plus weekly MBA mortgage applications and EIA petroleum inventories.

The FOMC takes center stage announcing its decision at 2pm ET, with a hold priced at ~93% by CME’s FedWatch tool, followed by Chair Warsh’s press conference at 2:30pm ET.

The only Non-Bill (>1yr in maturity) US Treasury auction is a $30B 2-year floating-rate note (not followed due to its floating nature).

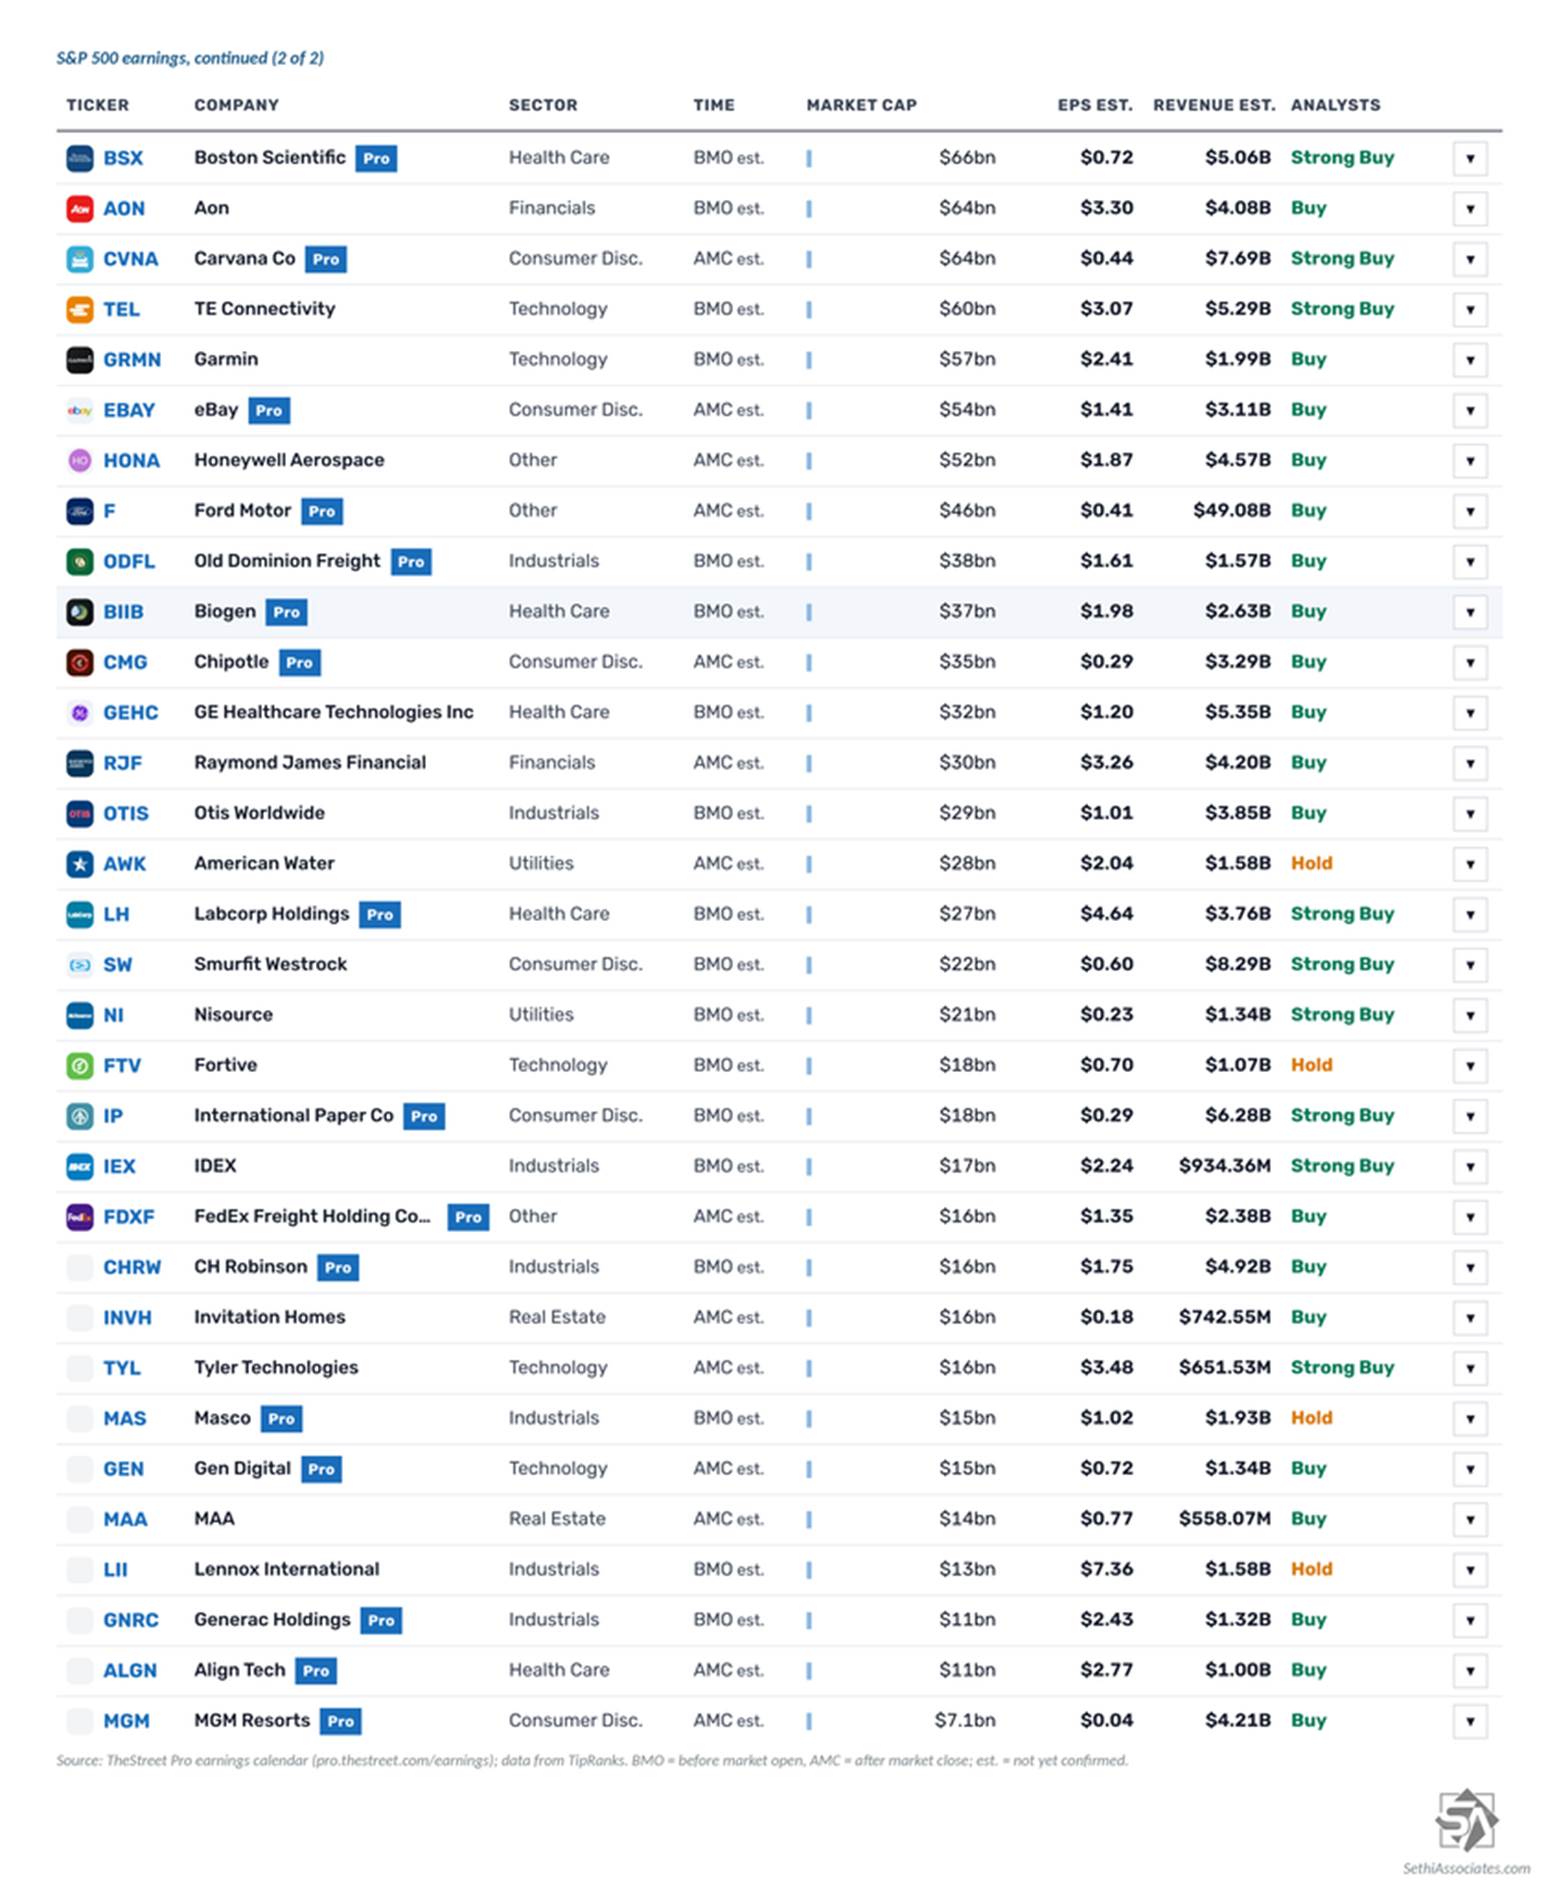
Alphabet and Microsoft lead 46 S&P 500 components reporting, nine of them with market caps over $100B:

Before the open: GE Vernova ($GEV), Amphenol ($APH), ADP ($ADP), Phillips 66 ($PSX), Vertiv ($VRT), American Electric Power ($AEP), Boston Scientific ($BSX), Aon ($AON), TE Connectivity ($TEL), Garmin ($GRMN), Old Dominion Freight Line ($ODFL), Biogen ($BIIB), GE HealthCare ($GEHC), Otis Worldwide ($OTIS), Labcorp ($LH), Smurfit Westrock ($SW), NiSource ($NI), Fortive ($FTV), International Paper ($IP), IDEX ($IEX), C.H. Robinson ($CHRW), Masco ($MAS), Lennox International ($LII) and Generac ($GNRC)

After the close: Alphabet ($GOOGL), Microsoft ($MSFT), KLA ($KLAC), ServiceNow ($NOW), T-Mobile ($TMUS), Equinix ($EQIX), O’Reilly Automotive ($ORLY), FedEx ($FDX), Carvana ($CVNA), eBay ($EBAY), Honeywell Aerospace ($HONA), Ford ($F), Chipotle ($CMG), Raymond James ($RJF), American Water Works ($AWK), FedEx Freight ($FDXF), Invitation Homes ($INVH), Tyler Technologies ($TYL), Gen Digital ($GEN), MAA ($MAA), Align Technology ($ALGN) and MGM Resorts ($MGM)

Ex-US highlights include decisions from central banks in Canada and New Zealand, Germany November GfK consumer confidence, France Q3 total jobseekers, Italy August industrial sales and September PPI, and Australia September CPI.
Upside, Downside Movers in the Morning

Upside

– $AEMD +403% (merger agreement with North Immunology adds an IL-13 x IL-18 bispecific-antibody program for atopic dermatitis)

– $GNRC +30% (Amazon supply agreement includes $2.4B of backup-generator deliveries expected during 2027-2028)

– $VEEA +30% (non-binding combination term sheet with NovaGen targets a $750M AI-health platform)

– $DTSS +12% (strategic cooperation expands into AI-powered elderly-care robots in China)

– $MEDS +12% (Helomics acquisition expands its cancer-diagnostics and precision-oncology platform)

– $VICR +12% (licenses its vertical power-delivery technology to a leading AI OEM)

– $NBIS +9.0% (reported AI-compute price increases signal stronger pricing power amid constrained capacity)

– $IREN +5.5%, CIFR +6.3% (AI-compute peers gain on the pricing-power read-through from NBIS)

– $APLD +5.8%, HUT +5.0%, WULF +4.7% (Wells Fargo initiates the data-center infrastructure names at Overweight)

– $NOK +5.0% (expands its Microsoft partnership by integrating network-automation data tools with Microsoft Fabric)

– $BE +4.5%, $GEV +3.3% (data-center power names gain as the Amazon-GNRC agreement reinforces hyperscaler power demand)

– LCID +4.2% (partners with Bolt to deploy at least 25,000 Level 4 autonomous vehicles across Europe)

– QGEN +3.5% (traders circulating German press report saying Qiagen attracts interest from KKR, Advent, TPG)

– GLW +3.7%, ANET ($ANET) +2.7%, CIEN +3.2% (AI networking and optical names rise as compute pricing points to continued infrastructure tightness)

– MRVL ($MRVL) +3.5%, LRCX +3.6%, INTC +3.2%, TER +3.6%, AMAT +3.2%, KLAC +3.2% (semiconductors rebound with technology shares after the Fed decision clears a major policy-event overhang)

Downside

– LGVN -49% (Phase 2b ELPIS II trial in hypoplastic left heart syndrome missed its primary efficacy endpoint)

– DLXY -45% (reverses sharply after a non-binding LOI covering up to a 48% interest in a Kazakhstan oil-field project)

– FLNC -22% (cuts FY guidance as supply-chain issues and delays ramping its Houston manufacturing facility drive a much larger expected loss)

– S -3.9% (no clear fresh catalyst identified; notable liquid cybersecurity move)

– BDX -3.5% (no clear fresh catalyst identified; unusually large premarket move in the medical-device name)

– LEN ($LEN) -1.3% (quarter missed and forward guidance disappointed as affordability pressure continued to weigh on homebuilding demand)

Source: Trade The News

A Hawkish Fed Does Little To Soothe Markets

The S&P 500 falls for the 7th time in 8 sessions straining against key downside levels as a more hawkish than expected Fed does little to soften expectations for higher volatility in stock and bond markets.