OpenAI and Oracle to Use Google Chips: 8 Key Items Shaping the Stock Market Wednesday

SK Hynix and ASM International see tight chip capacity, here comes Fed Chair Kevin Warsh and other headlines moving the market this morning.
SK Hynix and ASM International see tight chip capacity, here comes Fed Chair Kevin Warsh and other headlines moving the market this morning.
– $ULBI +145% (agrees to be acquired for $16.00 a share in cash)
– $BOOM +21% (Q3 sales and adjusted EBITDA exceeded the high end of guidance as backlog and cash flow strengthened)
– $AXGN +16% (Q3 beat and full-year revenue guidance was raised)
– $VRT +16% (Q3 organic orders more than doubled and full-year sales guidance was raised by $650 million)
– $UCTT +15% (Q3 results and outlook drove a sharp upside reaction)
– $LUNG +12% (Q3 results and outlook drove a sharp upside reaction)
– $GEHC +9.7% (Q3 beat, full-year EPS and free-cash-flow guidance was raised, and a $945 million acquisition was announced)
– $FLEX +9.5% (fiscal Q2 beat and the full-year outlook was raised)
– $LCII +7.6% (confirms an unsolicited $101-a-share cash acquisition proposal)
– $SKHY +7.5% (quarterly revenue exceeded 100 trillion won for the first time)
– $STLA +6.9% (Q3 net loss narrowed about 90% and the 2026 outlook was reaffirmed)
– $ETSY +6.6% (announces a leadership transition)
– $SNDK +4.2%, MU +3.6% (memory names rise after SKHY posted record quarterly revenue)
– $GEV +2.4% (Q3 orders surged 96%, backlog reached $197 billion, cash-flow guidance was raised and the buyback authorization doubled)
– $RAPP -23% ($350 million of stock and convertible-note offerings priced alongside a $30 million private placement)
– $ENPH -19% (Q3 revenue missed and the Q4 sales guide was roughly 20% below consensus amid weak US residential-solar demand)
– $INTA -17% (quarter beat, but the fiscal-year outlook failed to clear elevated expectations)
– $EDU -13% (fiscal Q1 results disappointed investors)
– $BSX -12% (Q3 EPS missed and Q4 and full-year profit guidance came in below consensus)
– $LOGI -12% (holiday-quarter sales guidance called for a decline and included a $70 million–$80 million supplier-incident hit)
– $SEDG -8.7% (solar-equipment sympathy decline following ENPH’s weak demand commentary and Q4 guide)
– $NXPI -8.1% (Q3 beat, but the Q4 guide was only roughly in line and fell short of elevated expectations)
– $FFIV -7.6% (Q4 beat, but fiscal 2027 growth guidance disappointed and operating margins contracted)
– $HOOD -6.4% (revenue missed as crypto revenue fell 55%, outweighing an EPS beat and record total revenue)
– $GSK -5.8% (headline Q3 beat was offset by weak vaccine sales, soft new-product performance and unchanged guidance)
– $LII -4.7% (Q3 profit fell, segment margin contracted 240 basis points and the full-year EPS outlook disappointed)
– $STX -2.5% (fiscal Q1 results prompted a modest sell-the-news reaction)
– $V -1.7% (fiscal Q4 earnings and revenue missed forecasts despite healthy payment-volume growth and a 16% dividend increase)
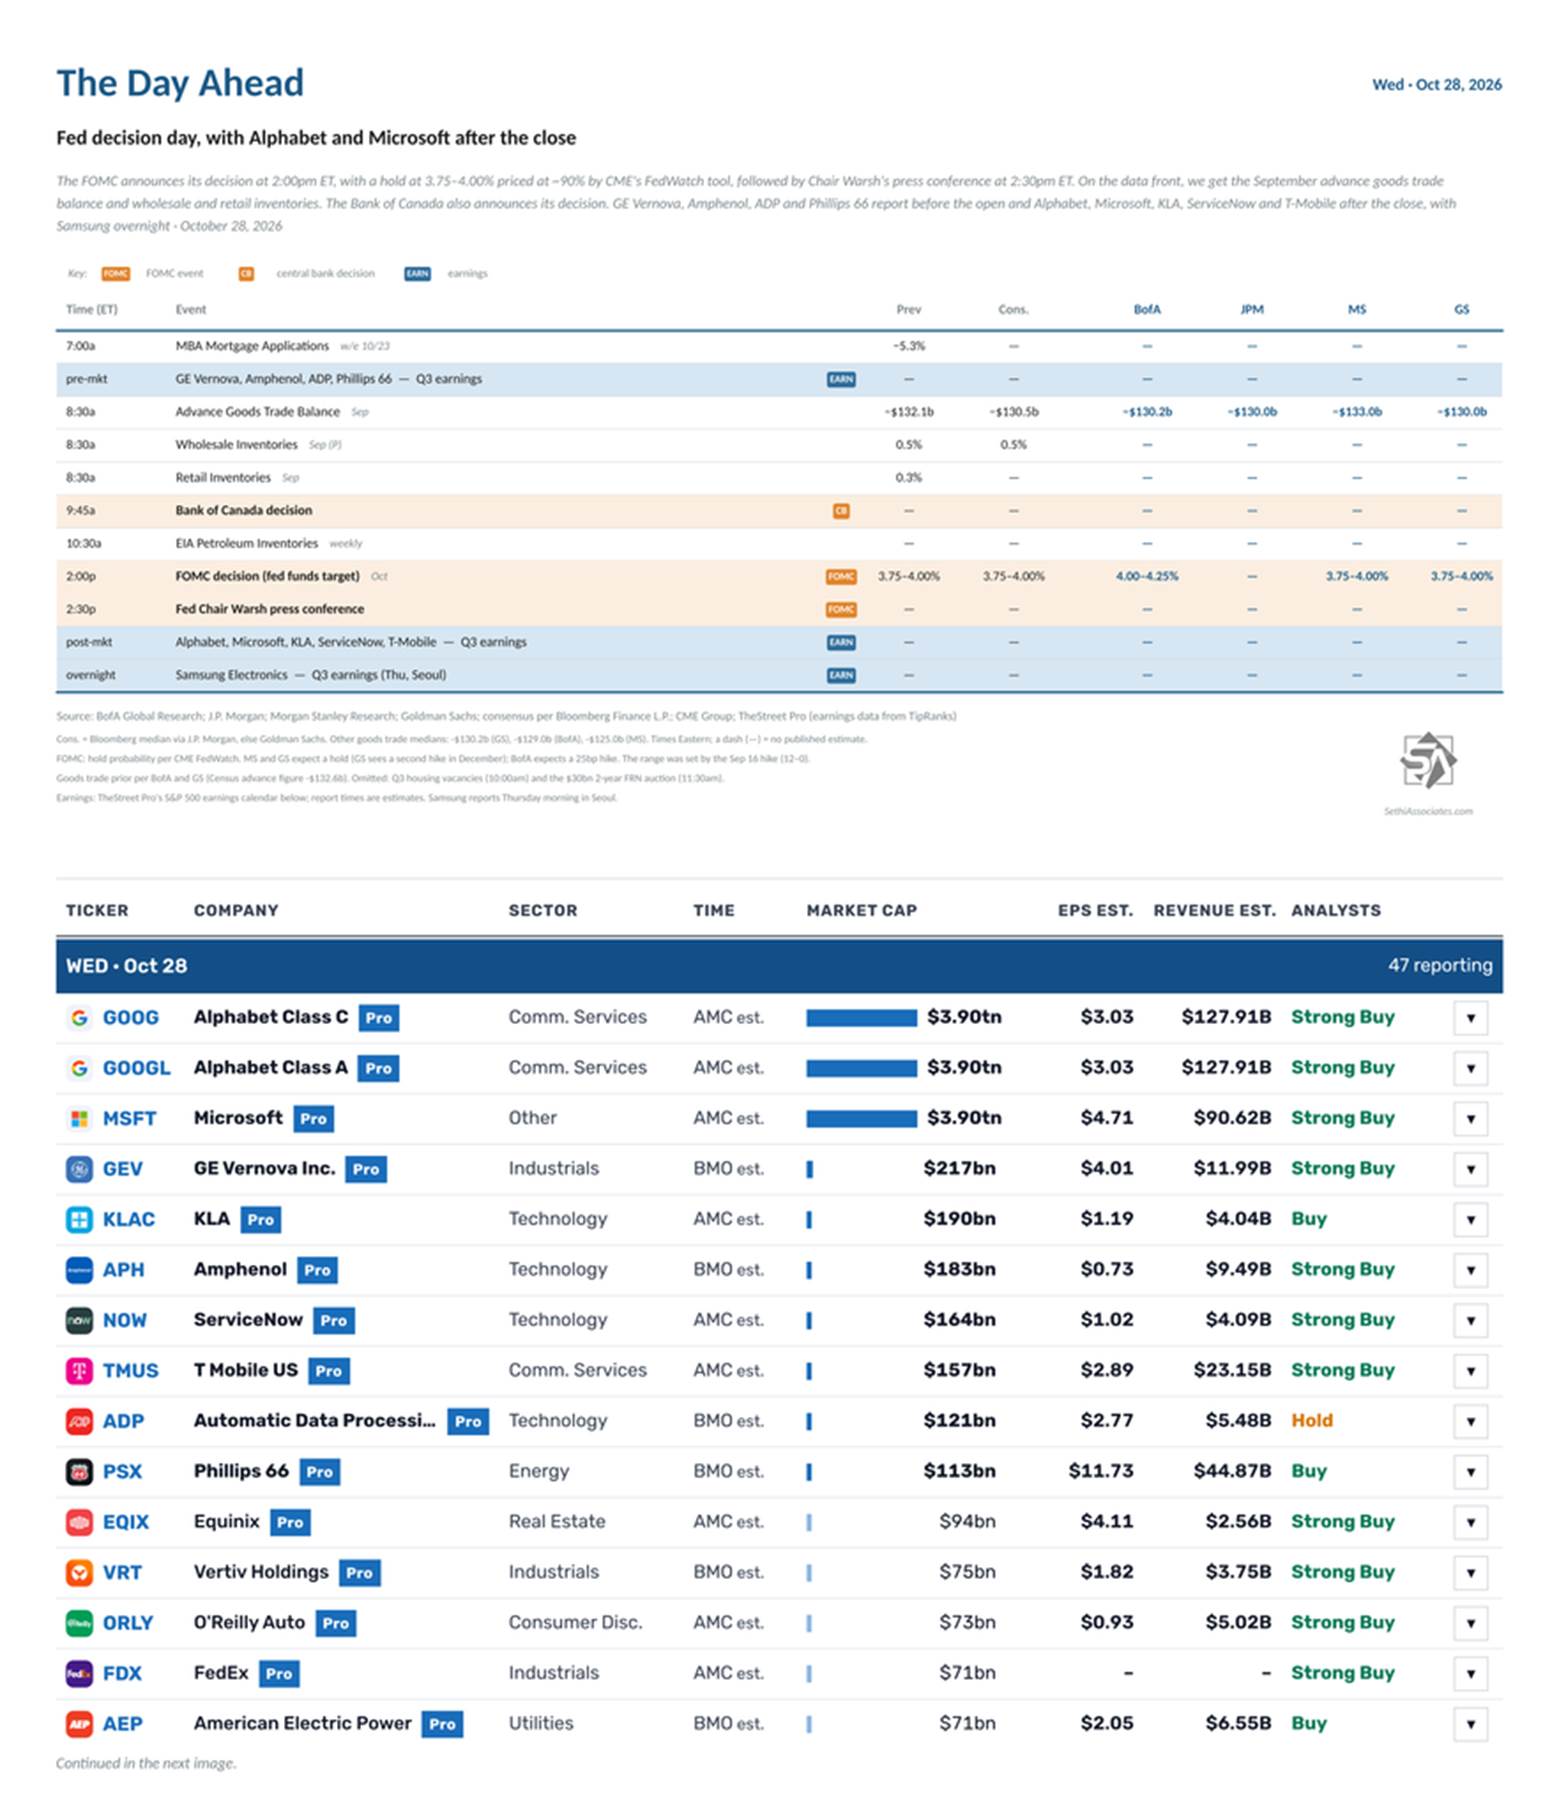
US economic data is light Wednesday, with just the September advance goods trade balance and wholesale and retail inventories plus weekly MBA mortgage applications and EIA petroleum inventories.
The FOMC takes center stage announcing its decision at 2pm ET, with a hold priced at ~93% by CME’s FedWatch tool, followed by Chair Warsh’s press conference at 2:30pm ET.
The only Non-Bill (>1yr in maturity) US Treasury auction is a $30B 2-year floating-rate note (not followed due to its floating nature).
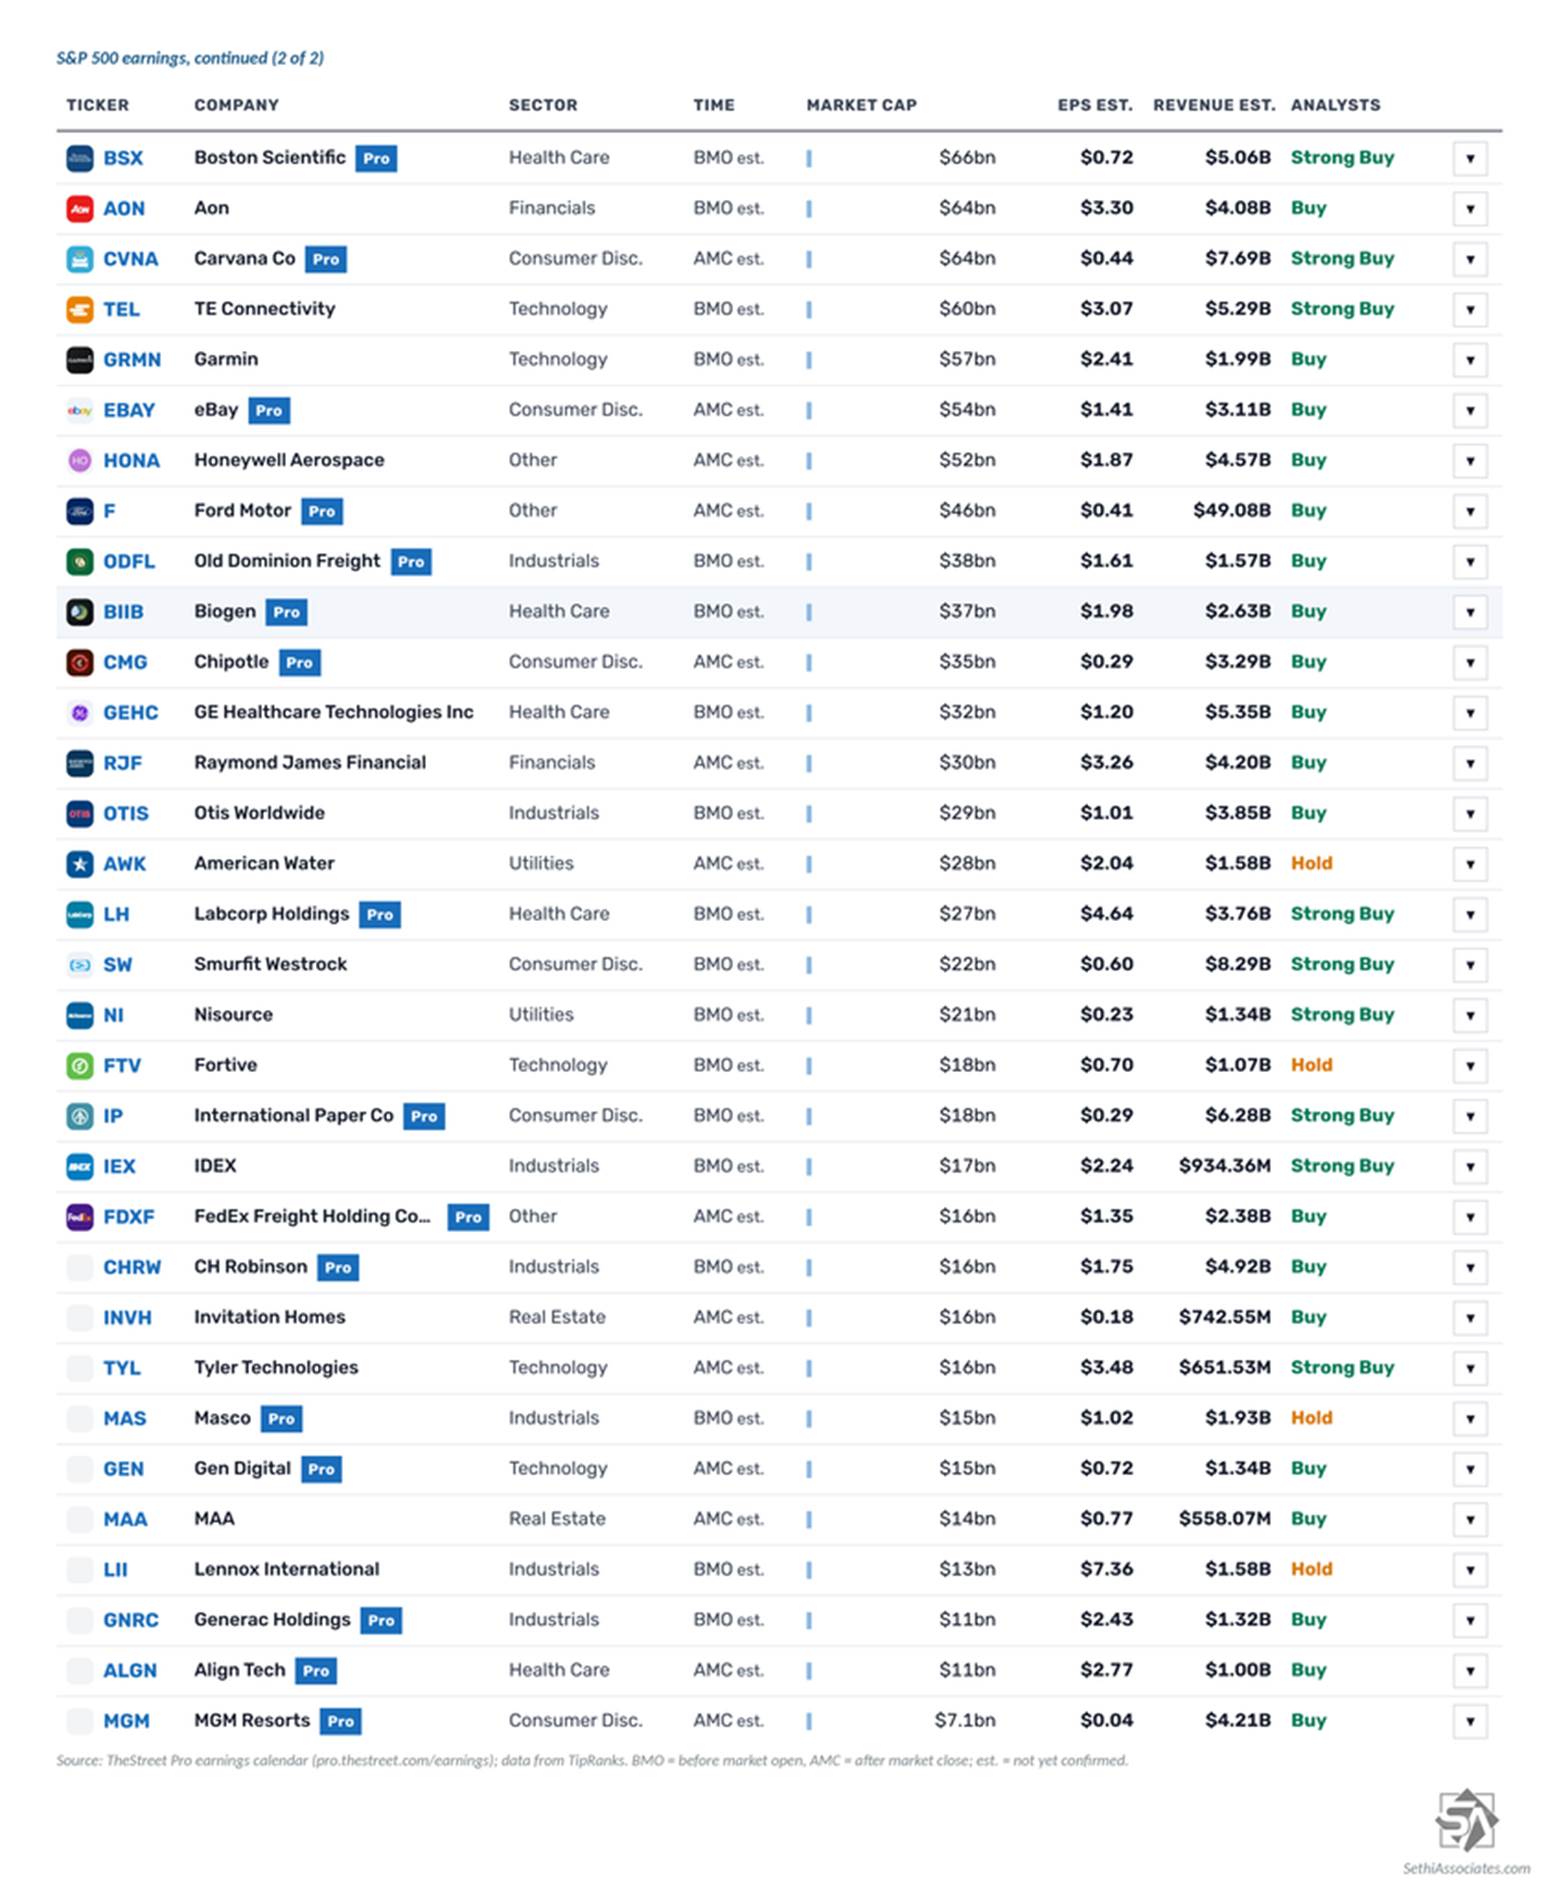
Alphabet and Microsoft lead 46 S&P 500 components reporting, nine of them with market caps over $100B:
Before the open: GE Vernova ($GEV), Amphenol ($APH), ADP ($ADP), Phillips 66 ($PSX), Vertiv ($VRT), American Electric Power ($AEP), Boston Scientific ($BSX), Aon ($AON), TE Connectivity ($TEL), Garmin ($GRMN), Old Dominion Freight Line ($ODFL), Biogen ($BIIB), GE HealthCare ($GEHC), Otis Worldwide ($OTIS), Labcorp ($LH), Smurfit Westrock ($SW), NiSource ($NI), Fortive ($FTV), International Paper ($IP), IDEX ($IEX), C.H. Robinson ($CHRW), Masco ($MAS), Lennox International ($LII) and Generac ($GNRC)
After the close: Alphabet ($GOOGL), Microsoft ($MSFT), KLA ($KLAC), ServiceNow ($NOW), T-Mobile ($TMUS), Equinix ($EQIX), O’Reilly Automotive ($ORLY), FedEx ($FDX), Carvana ($CVNA), eBay ($EBAY), Honeywell Aerospace ($HONA), Ford ($F), Chipotle ($CMG), Raymond James ($RJF), American Water Works ($AWK), FedEx Freight ($FDXF), Invitation Homes ($INVH), Tyler Technologies ($TYL), Gen Digital ($GEN), MAA ($MAA), Align Technology ($ALGN) and MGM Resorts ($MGM)
Ex-US highlights include decisions from central banks in Canada and New Zealand, Germany November GfK consumer confidence, France Q3 total jobseekers, Italy August industrial sales and September PPI, and Australia September CPI.
A wave of AI-related deals sent semiconductor shares soaring, helping the Nasdaq rally while investors prepared for the Fed and crucial earnings from Microsoft and Google parent Alphabet.
Brent topped $116 and stocks pulled back on fears of renewed U.S.-Iran hostilities after the midterm elections. For the week, small caps led with the Russell 2000 up 2% while the S&P 500 and Nasdaq slipped.
We added to six holdings, and upgraded and lifted a price target on another as favorable AI data conflicted with market emotion.
Dougie Kass
3m ago
The tide is going out and now you understand my resentment towards Fin TV.
Look at their favorite stocks – $BABA $UBER $NFLX $SHAK $GEV $CAT Paramount, $BA, $RDDT the banks/brokers/private equity et al
They are swimming naked.
Memo to retail investors – they will not take ownership of their mistakes, the will continue to smile, they will be confident in view, they will take your assets.
They will cost you money.
Turn off your TVs.
Positions: None
Worries about the sustainability of the AI trade surfaced once again, driving down a swath of related stocks, but other stocks rallied as Treasury yields dropped the most since August 2025, seeing equal-weight vs cap-weight the most extreme since 2024.
“The sea was angry that day, my friends – like an old man trying to send back soup in a deli.”
– George Costanza
Today’s market is different than some of the past sharp drawdowns in the last 12-18 months.
* The drop is broad and deep — with other asset classes like gold and bitcoin joining the downside.
* There is no single catalyst like Leopold (Situational Awareness hedge fund liquidation) to blame on the market’s selloff.
* The weakness in financials over the last several months is now accelerating, with no respite whatsever.
* The decline in over stretched stocks is breathtaking — especially the over conceptualized AI stocks on the periphery (e.g. $GEV -$105 to $820). Look at the breakdown in $CAT’s chart (-$45 and down from $950 to $695 in a straight line).
* We are witnessing a classical (but violent) rotation. See the remarkable strength in staples and healthcare.
* A sign of flight to quality/safety seen in a pronounced rise in bond prices (and in lower bond yields). ($TLT +$1.20 today)
Position: None
Dougie Kass
39m ago
I am no longer dwelling on the BS from panelists on the shows.
But as I have warned when the tide goes out you will realize the absence of analytical rigor and process.
The panelists, you will also realize, will not revisit their losers.
They will never timestamp because viewers would realize the “jig is up.”
Panelists want to seem/look smart – they want to polish their images as they are asset gatherers or are selling a service.
But look at the shares of homebuilders, $RDDT, $SHAK, $BABA, $TTAN, $GEV, $UBER, $NFLX and the many others that were confidently recommended by the panelists of floor traders, veterans of Long Island Boiler Room brokerages, phony technical analysts (who don’t even know what a fractal is or who Mandlebrot was!).
I have highlighted their BS as an advocate of the retail viewer who all generally think being a regular panelist on CNBC means alot.
It means virtually nothing.
Positions: None.