Can Nvidia Save the Indices?


A spreading Tech selloff and a report of an NSA network outage sent the S&P 500 to its lowest close since late July, undercutting its November 5th close, with all 11 sectors lower ahead of Nvidia’s results.
A spreading Tech selloff and a report of an NSA network outage sent the S&P 500 to its lowest close since late July, undercutting its November 5th close, with all 11 sectors lower ahead of Nvidia’s results.
– $SEZL +30% (Q3 revenue and transaction volume surged, FY guidance was raised for the fourth time and preliminary 2027 EPS guidance was introduced)
– $ARQ +26% (record Q3 revenue, sharp margin expansion and the low end of FY EBITDA guidance was raised)
– $APP +22% (Q3 profit beat and revenue came in $100 million above the top of the company’s forecast)
– $RUN +21% (Q3 beat as direct installations returned to growth and storage attachment reached a record)
– $WRBY +21% (raised the low end of FY sales guidance and confirmed November 12 preorders for its first Intelligent Eyewear collection)
– $ADMA +20% (ASCENIV sales rose 31%, gross margin expanded sharply and the adjusted earnings outlook was raised)
– $U +20% (strongest quarter on record, with Vector revenue up 126% and the first GAAP profit since its IPO)
– $TPR +14% (Q1 beat with strong Coach growth and FY revenue, margin and EPS guidance raised)
– $EPAM +12% (Q3 beat alongside a $1.5 billion buyback expansion and planned $500 million accelerated repurchase)
– $TM +8.8% (first-half profit strengthened and the full-year operating-income and net-income forecasts were raised)
– $SONY +6.0% (Q2 profit surged on gaming and film strength, prompting higher full-year sales, profit and dividend forecasts)
– $BABA +5.3%, $TCOM +4.3%, $NTES +3.9%, $PDD +3.7%, $JD +4.2% (China ADRs rise with an overnight rebound in Hong Kong technology shares)
– $GFI +4.4% (gold producer gains as bullion prices rally)
– $CELH +2.7% (record Q3 revenue rose 17% as the expanded beverage portfolio sustained growth)
– $UBER +2.4% (Amazon Prime members can now order Uber Eats with free delivery on qualifying purchases)
– $MNTN -46% (slashed FY revenue and EBITDA guidance after sales-team execution problems and named a new CEO)
– $BZFD -34% (Q3 revenue plunged 44%, adjusted EBITDA turned negative and the FY outlook was deferred)
– $VCYT -32% (lowered near-term Decipher Prostate expectations, narrowed FY guidance below consensus and forecast only mid-single-digit 2027 revenue growth)
– $ANVS -29% (proposed a dilutive stock-and-warrant offering while disclosing limited cash, going-concern risk and expanded authorized shares)
– $AKBA -25% (Q3 revenue fell sharply as Auryxia sales were hit by generic competition and pricing pressure)
– $HIMX -25% (guided Q4 revenue down 22% to 26% sequentially on abrupt automotive-display order corrections)
– $GIL -23% (Q3 missed expectations, FY sales and EPS guidance was cut sharply and 2026–2028 objectives were withdrawn)
– $WMS -13% (organic stormwater sales declined, demand softened and the FY revenue outlook was reduced)
– $QCOM -11% (smartphone-chip sales missed expectations on sluggish demand and declining Apple-related revenue)
– $FICO -10% (withheld FY27 guidance amid mortgage-pricing uncertainty and was downgraded by RBC despite a quarterly beat)
– $SNAP -10% (Q3 revenue missed expectations)
– $MELI -9.2% (earnings missed and logistics investment compressed operating margin despite strong revenue growth)
– $AMCR -8.1% (profit missed and the six-month EPS outlook was cut as energy and distribution costs outpaced pricing recovery)
– $ASX -7.6%, $SNDK -5.8%, $SKHY -6.2%, $STX -4.5% (Asian and memory-chip names extend the semiconductor selloff as election results intensify concerns over slower data-center construction)
– $ARM -7.4% (quarter beat, but current-quarter guidance failed to clear elevated expectations and shares joined the broader chip selloff)
– $HUBS -6.5% (Q3 beat, but Q4 profit guidance came in below expectations)
– $BDX -5.4% (Q4 beat, but low-single-digit FY27 revenue growth and modest EPS growth guidance disappointed)
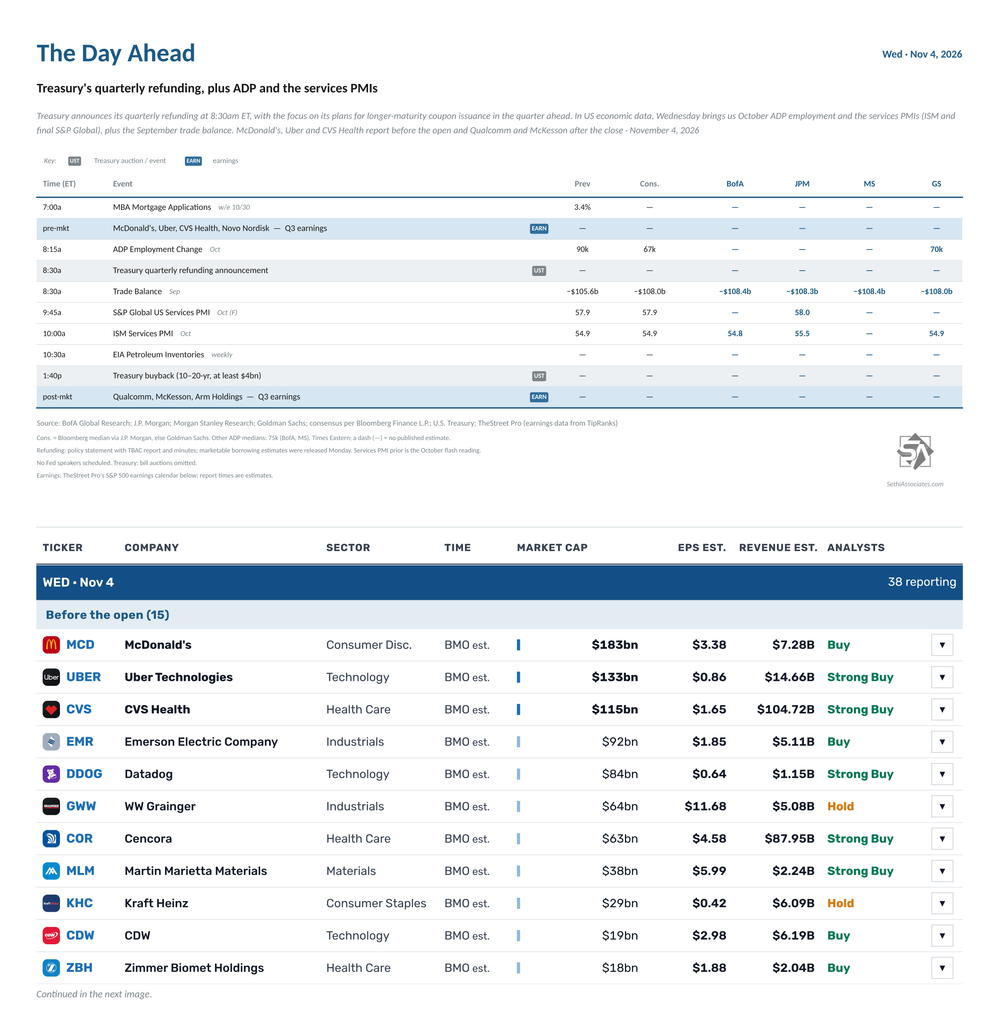
In US economic data, Wednesday brings us October ADP private employment growth and the services PMIs (ISM and final S&P Global), plus the September trade balance. We’ll also get weekly MBA mortgage applications and EIA petroleum inventories.
There are no Fed speakers scheduled.
There are no non-Bill (>1yr in maturity) US Treasury auctions, but Treasury announces its quarterly refunding at 8:30am ET, with the focus on its plans for longer-maturity coupon issuance in the quarter ahead. It also holds a buyback of 10- to 20-year securities in the afternoon.
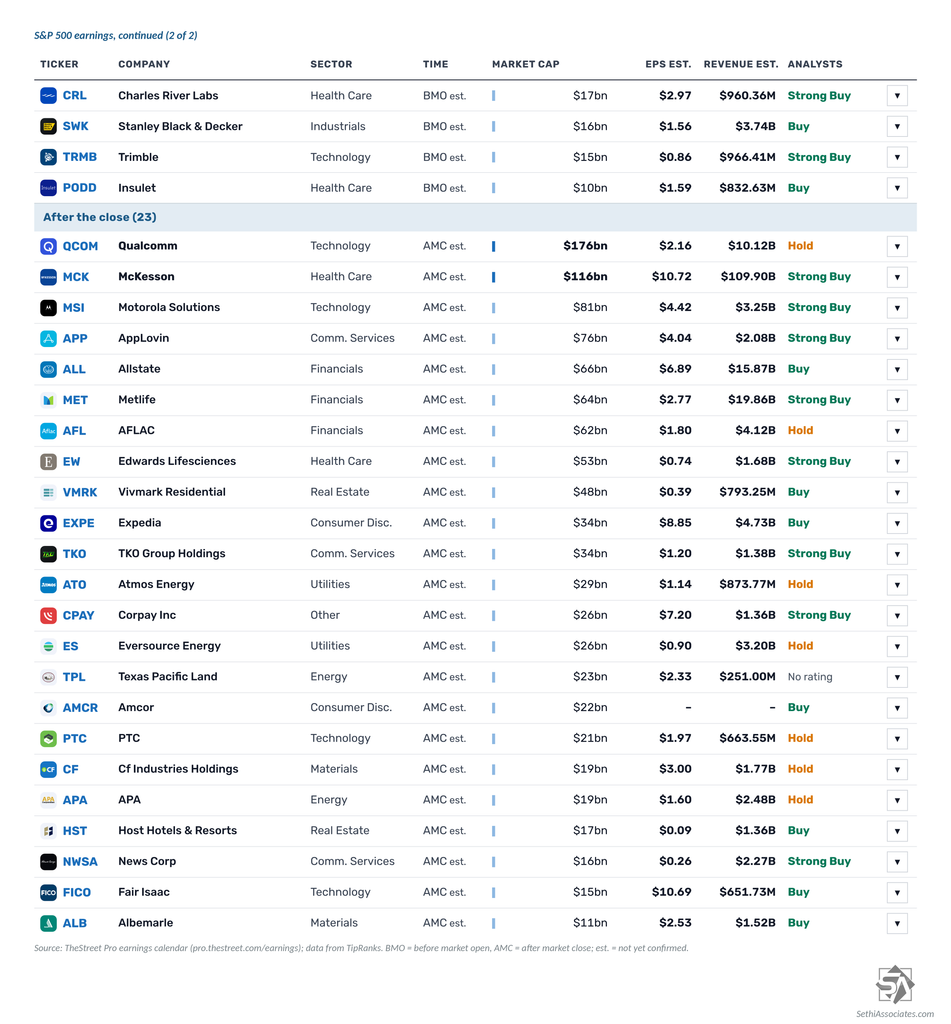
38 S&P 500 components report, five of them with market caps over $100B:
Before the open: McDonald’s ($MCD), Uber ($UBER), CVS Health ($CVS), Emerson Electric ($EMR), Datadog ($DDOG), W.W. Grainger ($GWW), Cencora ($COR), Martin Marietta Materials ($MLM), Kraft Heinz ($KHC), CDW ($CDW), Zimmer Biomet ($ZBH), Charles River Laboratories ($CRL), Stanley Black & Decker ($SWK), Trimble ($TRMB) and Insulet ($PODD)
After the close: Qualcomm ($QCOM), McKesson ($MCK), Motorola Solutions ($MSI), AppLovin ($APP), Allstate ($ALL), MetLife ($MET), Aflac ($AFL), Edwards Lifesciences ($EW), Vivmark Residential ($VMRK), Expedia ($EXPE), TKO Group ($TKO), Atmos Energy ($ATO), Corpay ($CPAY), Eversource Energy ($ES), Texas Pacific Land ($TPL), Amcor ($AMCR), PTC ($PTC), CF Industries ($CF), APA ($APA), Host Hotels & Resorts ($HST), News Corp ($NWSA), Fair Isaac ($FICO) and Albemarle ($ALB)
Outside the S&P 500, Novo Nordisk ($NVO) reports before the open and Arm Holdings ($ARM) and MercadoLibre ($MELI) after the close.
Also, opening arguments are scheduled in a Los Angeles trial over claims that Meta ($META) and Snap ($SNAP) designed their platforms to be addictive and harmful to young users, per Bloomberg.
Ex-US highlights include the final October services PMIs (including China’s RatingDog services PMI), Eurozone October CPI, Spain’s October unemployment rate, UK October official reserves changes and Canada’s September trade balance. There are rate decisions from Sweden’s Riksbank, Poland and Brazil, the ECB releases its wage tracker, ECB Chief Economist Lane and Bank of France Governor Moulin speak, and the Bank of Japan releases the minutes of its September meeting.
Semiconductors led a rebound that broke the S&P 500’s three-day losing streak, but the average stock fell.
Let’s dig in following an up day on Wall Street to see what’s happened and what to expect.
Eight of 11 sectors rose and the Dow Jones Industrial Average gained for a third straight day, but another selloff in chipmakers kept the S&P 500 little changed and the Nasdaq in the red on the lightest volume of the year.
– AMOD +108.5% (closed a bitcoin-funded private placement and regained Nasdaq listing compliance)
– NIVF +40.0% (closed an approximately $1.25M public offering)
– SDEV +36.0% (extends Thursday’s surge in the SKY-token treasury name; no clear fresh company-specific catalyst identified)
– TNMG +20.0% (agreed to sell its Japanese business in a $5.5M management buyout)
– $SYNA +15.0%, ON +8.0% (revised merger makes ON’s acquisition of SYNA an all-cash deal at $123 per share)
– $CYPH +8.5%, $FWDI +6.5%, $MSTR +5.0%, $COIN +1.5% (digital-asset treasury and crypto-linked names rise as Bitcoin and major tokens rally)
– $BETR +7.5% (Cantor Fitzgerald upgrades to Overweight from Neutral)
– $XRPN +7.0% (shareholders approved the proposed business combination with Evernorth)
– $RZAI -21.0% (extends volatile post-direct-listing selling after Thursday’s 29% drop)
– $NXL -20.0% (gives back part of Thursday’s 76% spike following a 10-year Latin American distribution agreement)
– $STX -11.5%, WDC -7.0% (HDD makers fall after Toshiba outlined plans to double capacity and target sharply higher market share)
– $NKE -9.0% (mixed FQ1 as revenue missed and the FY sales outlook implied a surprise steep decline, alongside job cuts and a business reorganization)
– $FICO -8.5%, $EFX -3.5%, $TRU -2.5% (mortgage-credit names fall on a reported FHFA plan requiring lenders to pull data from two credit bureaus instead of three for GSE loans)
– $ASTS -3.5% (B. Riley downgrades to Neutral from Buy)
Major indices were down for a second session Tuesday but finished well off the lows after a key Fed voice said there’s “no need for urgency” on rate hikes.
Upside
– $BKYI +76% (no clear fresh catalyst identified; unusually large, high-volume premarket move)
– $SSTI +51% (agrees to be acquired for $8.00 cash plus a contingent-value right worth up to another $3.00 per share)
– $SANG +39% (agrees to a $204M cash-and-stock takeover at an indicated 47% premium)
– $SMMT +18% ($2B strategic equity investment at an $18.36-equivalent share price plus an expanded oncology collaboration)
– $MSGY +15% (rebounds after the financing-driven selloff; $1M placement proceeds will fund a further acquisition)
– $FFAI +13% (no clear fresh catalyst identified; unusually large, high-volume premarket move)
– $MX +8.7% (rises on read-through from its strategic partner’s U.S. government silicon-carbide development award)
– $NVTS +8.7% (awarded a U.S. government program to develop next-generation 10-kV silicon-carbide power semiconductors)
– $IOVA +8.3% (no clear fresh catalyst identified after a clinical and regulatory-news check; unusually large, liquid biotech move)
– $KMX +5.6% (Q2 beat across the board as sales and profit topped expectations)
Downside
– $QURE -52%, CLPT -24% (FDA said the AMT-130 data package was inadequate to support accelerated approval in Huntington’s disease; CLPT falls on delivery-platform read-through)
– $JLHL -31% ($898K private placement includes shares and pre-funded warrants priced at $0.30, implying substantial dilution)
– $FICO -21%, EFX -4.0% (credit-data names fall as FHFA pushes broader VantageScore use and moves to weaken FICO’s mortgage-scoring monopoly)
Position: None