OpenAI and Oracle to Use Google Chips: 8 Key Items Shaping the Stock Market Wednesday

SK Hynix and ASM International see tight chip capacity, here comes Fed Chair Kevin Warsh and other headlines moving the market this morning.
SK Hynix and ASM International see tight chip capacity, here comes Fed Chair Kevin Warsh and other headlines moving the market this morning.
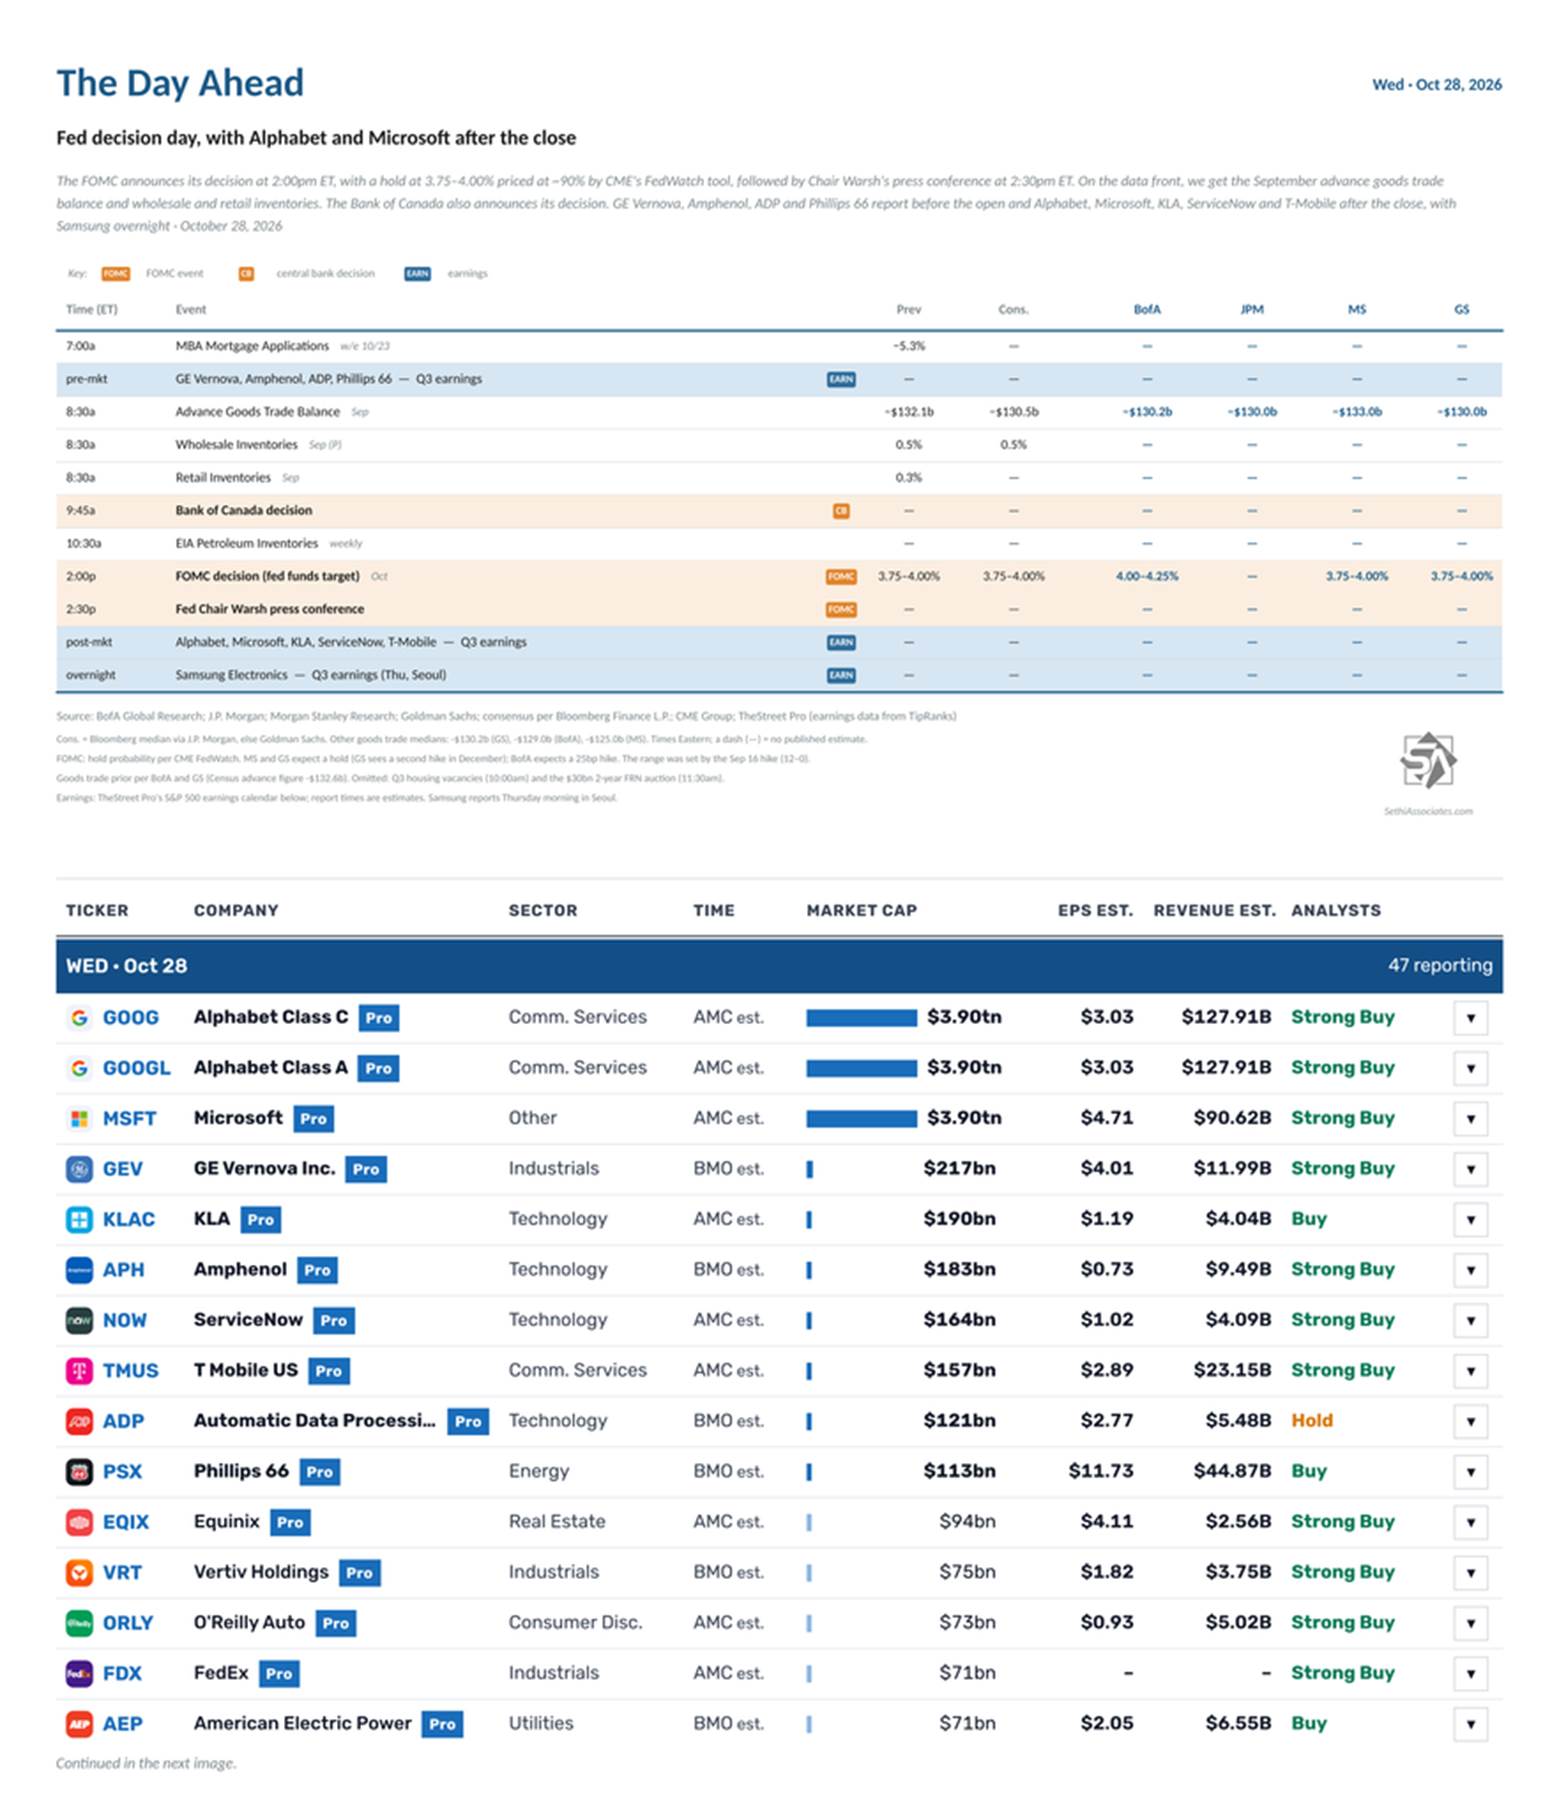
US economic data is light Wednesday, with just the September advance goods trade balance and wholesale and retail inventories plus weekly MBA mortgage applications and EIA petroleum inventories.
The FOMC takes center stage announcing its decision at 2pm ET, with a hold priced at ~93% by CME’s FedWatch tool, followed by Chair Warsh’s press conference at 2:30pm ET.
The only Non-Bill (>1yr in maturity) US Treasury auction is a $30B 2-year floating-rate note (not followed due to its floating nature).
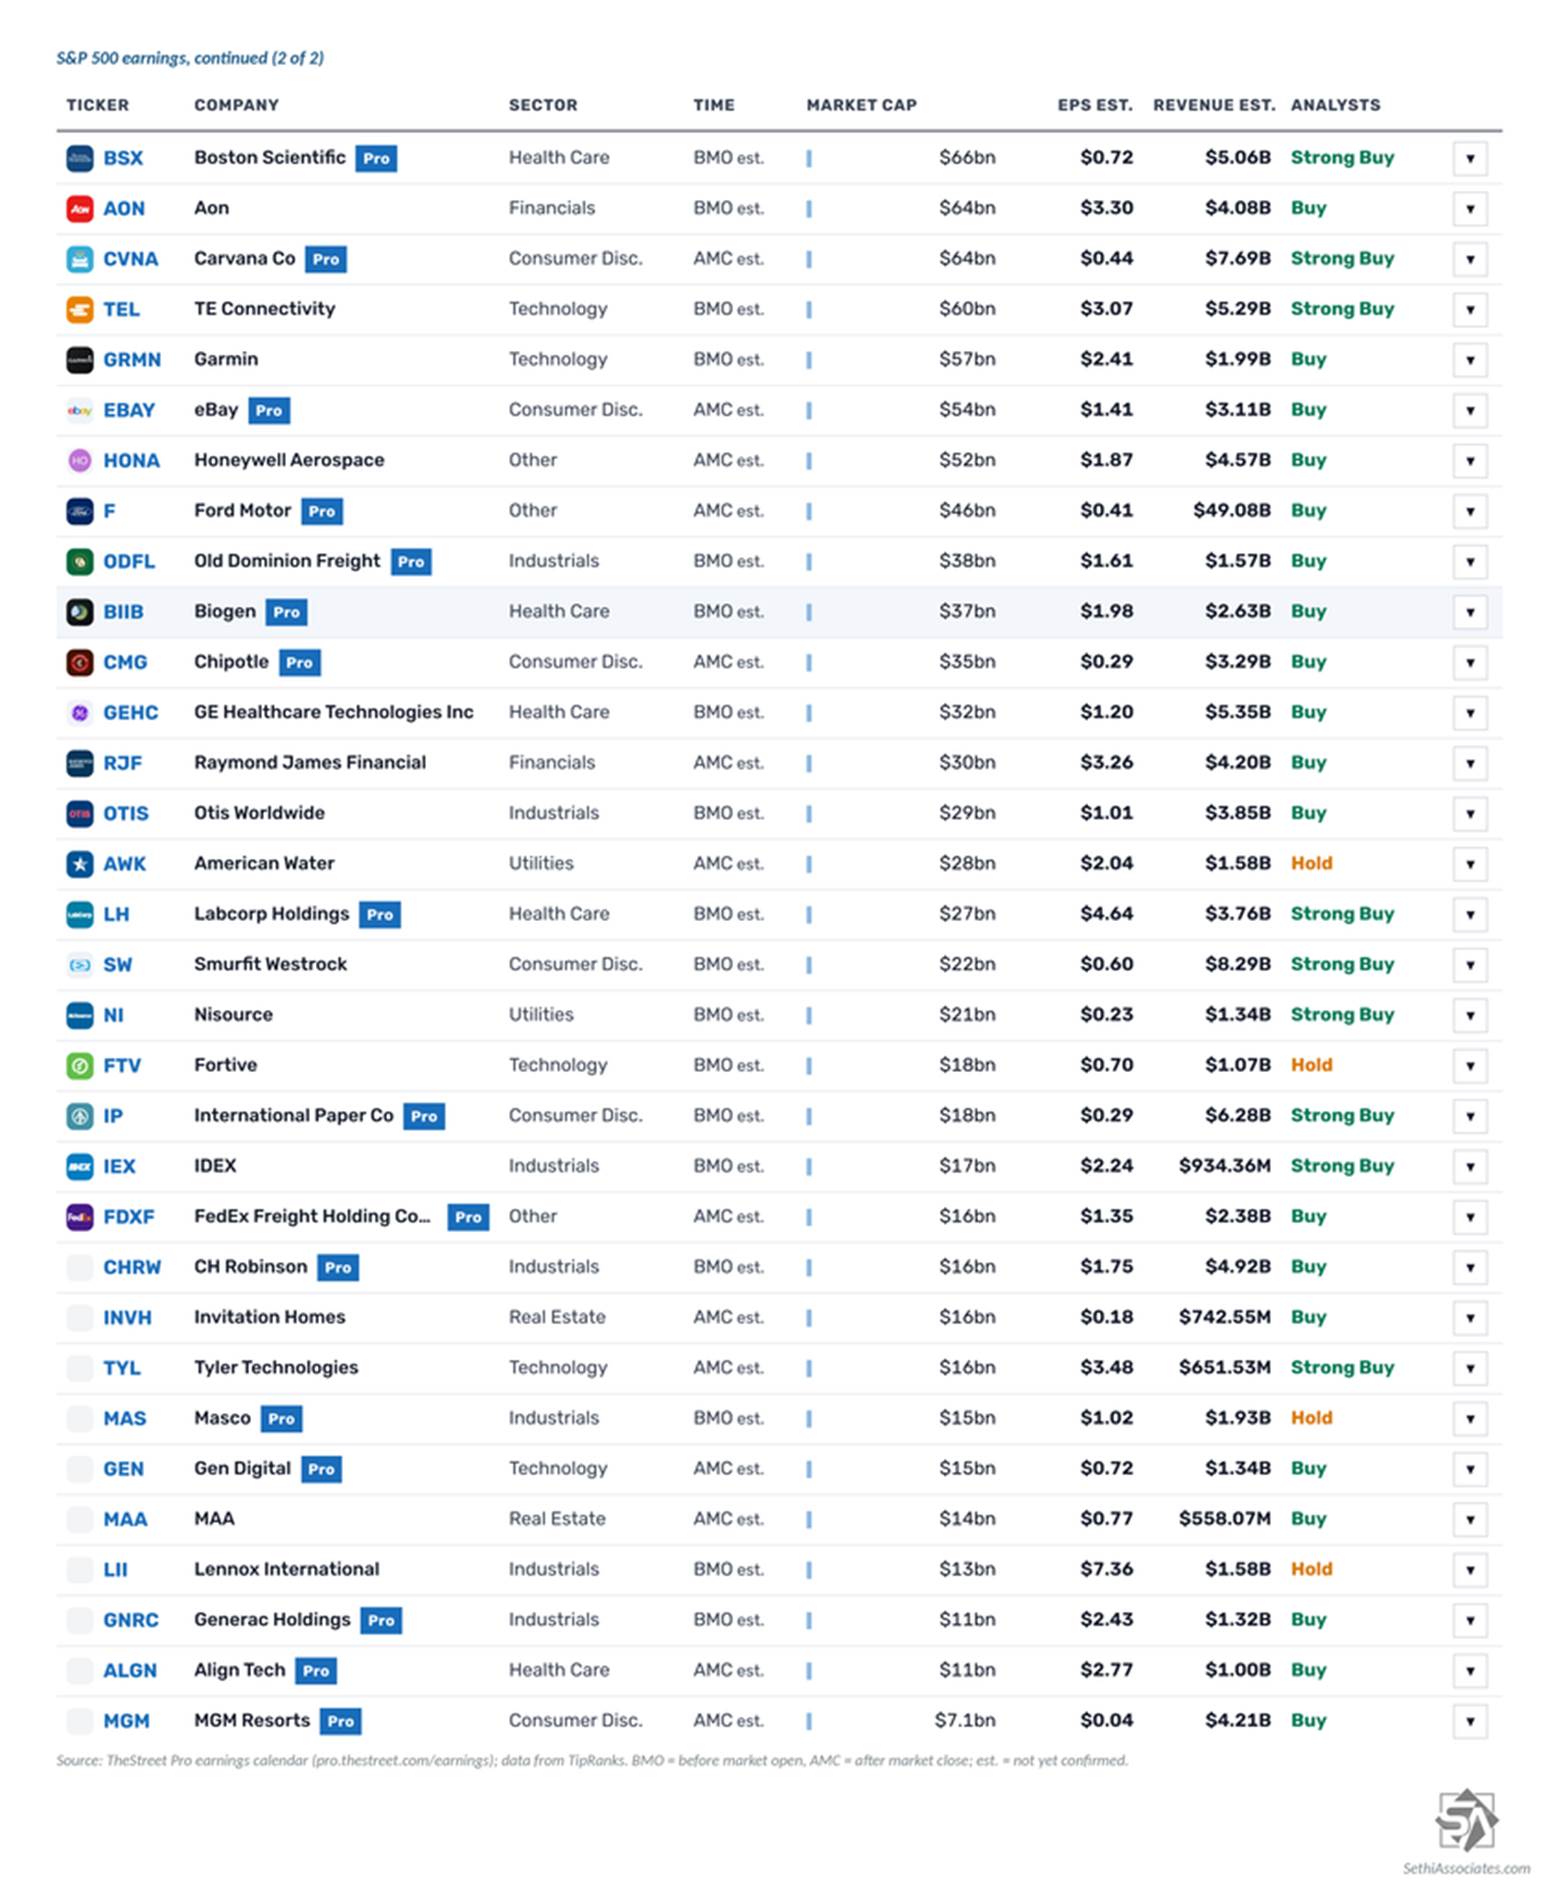
Alphabet and Microsoft lead 46 S&P 500 components reporting, nine of them with market caps over $100B:
Before the open: GE Vernova ($GEV), Amphenol ($APH), ADP ($ADP), Phillips 66 ($PSX), Vertiv ($VRT), American Electric Power ($AEP), Boston Scientific ($BSX), Aon ($AON), TE Connectivity ($TEL), Garmin ($GRMN), Old Dominion Freight Line ($ODFL), Biogen ($BIIB), GE HealthCare ($GEHC), Otis Worldwide ($OTIS), Labcorp ($LH), Smurfit Westrock ($SW), NiSource ($NI), Fortive ($FTV), International Paper ($IP), IDEX ($IEX), C.H. Robinson ($CHRW), Masco ($MAS), Lennox International ($LII) and Generac ($GNRC)
After the close: Alphabet ($GOOGL), Microsoft ($MSFT), KLA ($KLAC), ServiceNow ($NOW), T-Mobile ($TMUS), Equinix ($EQIX), O’Reilly Automotive ($ORLY), FedEx ($FDX), Carvana ($CVNA), eBay ($EBAY), Honeywell Aerospace ($HONA), Ford ($F), Chipotle ($CMG), Raymond James ($RJF), American Water Works ($AWK), FedEx Freight ($FDXF), Invitation Homes ($INVH), Tyler Technologies ($TYL), Gen Digital ($GEN), MAA ($MAA), Align Technology ($ALGN) and MGM Resorts ($MGM)
Ex-US highlights include decisions from central banks in Canada and New Zealand, Germany November GfK consumer confidence, France Q3 total jobseekers, Italy August industrial sales and September PPI, and Australia September CPI.
A wave of AI-related deals sent semiconductor shares soaring, helping the Nasdaq rally while investors prepared for the Fed and crucial earnings from Microsoft and Google parent Alphabet.
When a stock keeps falling on good news, the market’s trying to tell you something.
– $PROF +19% (preliminary Q3 revenue was about 45%-47% above consensus, with gross margin expected above 70%)
– $HAE +14% (no fresh company catalyst confirmed; unusually large move on light premarket volume)
– $WOLF +13% (received a conditional commitment for up to $1.5B of 30-year U.S. defense financing, partly offset by warrants for up to 7.5% of diluted equity)
– $EFX +4.5% (no fresh company catalyst confirmed; unusually large premarket move)
– $APA +3.1%, OXY +2.5%, DVN +2.4% (oil producers rise as WTI and Brent jump roughly 4.5%)
– $PLTR +2.3% (extends AI-software momentum despite weaker index futures)
– $PEP +1.6% (Q3 revenue and profit beat expectations; a better-than-feared quarter offsets a cut to the FY earnings-growth outlook)
– $ARGX -15% (Phase 3 UNITY study in Sjögren’s disease was stopped for futility, overshadowing positive Phase 2 celiac-disease data)
– $GLW -3.3% (no fresh company catalyst confirmed; unusually large premarket move)
– $EQIX -3.0% (rate-sensitive data-center REIT falls as the 10-year Treasury yield climbs to roughly 5.33%)
– $NXPI -3.1%, $AMAT -2.5%, $LRCX -2.9%, $HPE -2.0% (semiconductor and hardware names weaken as Treasury yields rise and global technology shares sell off)
– $SHW -2.7% (crude-oil surge raises petrochemical feedstock and input-cost concerns)
Renewed conflict in the Middle East, Microsoft and Meta earnings and other headlines moving stocks this morning.
* I am the anti Boca Biff…
I am the executor of a large estate. The estate has been probated for about two months.
The estate has a very large and concentrated equity portfolio. ($NVDA represents over 40% of the account, $FTAI, $EQIX, $IIPR and a bunch of BDCs are the major components of the estate’s stock portfolio.)
I have patiently waited to liquidate the equities.
Yesterday afternoon I liquidated the entire stock portfolio. Not one share of equities remain. Given the elevated level of stock prices I wanted zero (nada, zilch) stock exposure.
Upon settlement I plan to put the proceeds into a money market fund on Monday morning.
This is called an Estate Sale.
Post Script: I recently spoke to Boca Biff for the first time in years. More on Boca Biff’s stock trading early next week.
Position: None