Blue Wave Pops Market, But Can It Overcome Technical Hurdles?: 8 Key Items Shaping the Stock Market Wednesday

AMD and Super Micro crush earnings, CVS Health splits, and other headlines moving the market this morning.
AMD and Super Micro crush earnings, CVS Health splits, and other headlines moving the market this morning.
– $INO +262% (FDA grants accelerated approval to VOCERYQ to reduce surgery frequency in adults with recurrent respiratory papillomatosis)
– $PERI +31% (agrees to be acquired by Affle for $11.70 a share in cash, valuing the deal at about $420M)
– $IDXX +7.8% (Q3 beat and FY revenue and EPS outlooks were raised, outweighing a slightly lower margin range)
– $BABA +3.3% (China adds liquidity through a 100B-yuan swap facility, while reports point to BABA support for AAPL’s China AI rollout)
– $SKHY +3.2%, MU +1.1%, WDC +1.0%, SMTC +1.3% (memory and connectivity names rebound from Friday’s chip rout as Deutsche Bank turns bullish on US technology)
– $GFI +3.1%, AG +1.7%, HL +1.9% (gold and silver miners rebound as precious-metal prices recover)
– $RIVN +3.0% (UBS upgrades to Buy on valuation after the recent selloff)
– $CRWD +2.6% (Deutsche Bank upgrades to Buy)
– $EL +2.3% (Q1 beat with strong margin expansion and the FY sales, margin and EPS outlook raised)
– $AU +2.2% (TD Cowen initiates at Buy as gold rebounds)
– $FORM +1.7% (Freedom Capital upgrades to Buy after record Q3 results and the recent pullback)
– $CRWV +1.4%, BE +1.2%, $VRT +1.3% (AI-infrastructure names rebound with technology after the sharp three-week selloff)
– $KPTI -69% (files Chapter 11 and names Ayrmid as lead bidder in a court-supervised sale process)
– $PGEN -28% (falls on new RRP competition after the FDA approves INO’s VOCERYQ)
– $KOS -9.2% (Q3 profit and revenue missed expectations as crude prices retreat)
– $CHKP -6.3% (Q3 revenue slipped and missed expectations as management said the recovery is taking longer than anticipated)
– $EQNR -2.9%, $OXY -2.0%, $APA -1.9%, $XOM -1.3%, $CVX -1.1% (oil producers fall as crude drops nearly 4% on renewed US-Iran diplomacy)
Marvell and Lumentum ink a deal, Google and Amazon address capex funding concerns and other headlines moving the market this morning.
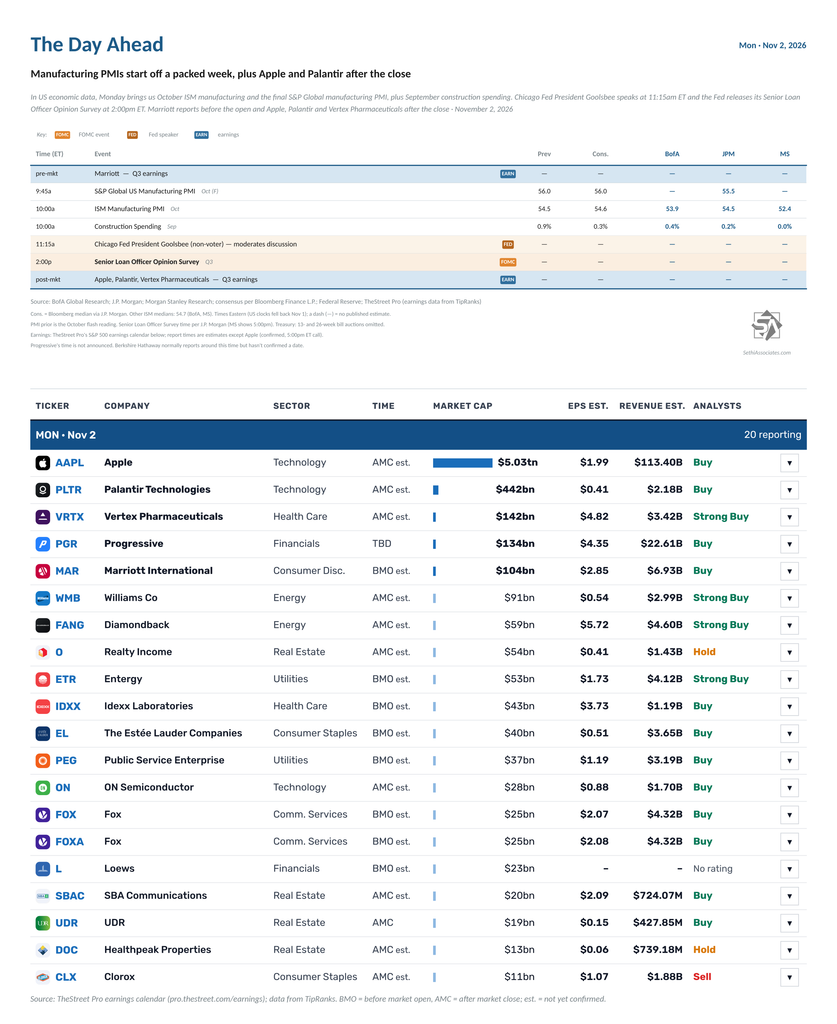
In US economic data, Monday brings us October ISM manufacturing and the final S&P Global manufacturing PMI. September reports are construction spending.
In terms of the Fed, Chicago Fed President Goolsbee (non-voter) moderates a discussion at 11:15am ET, and the Fed releases its Senior Loan Officer Opinion Survey at 2pm ET.
There are no Non-Bill (>1yr in maturity) US Treasury auctions this week, but we’ll get the Treasury’s borrowing amounts for the fourth quarter today.
19 S&P 500 components report, five of them with market caps over $100B:
Before the open: Marriott ($MAR), Entergy ($ETR), Idexx Laboratories ($IDXX), Estée Lauder ($EL), Public Service Enterprise Group ($PEG), Fox ($FOXA) and Loews ($L)
After the close: Apple ($AAPL), Palantir ($PLTR), Vertex Pharmaceuticals ($VRTX), Williams ($WMB), Diamondback Energy ($FANG), Realty Income ($O), ON Semiconductor ($ON), SBA Communications ($SBAC), UDR ($UDR), Healthpeak Properties ($DOC) and Clorox ($CLX)
Time not announced: Progressive ($PGR)
We can see several reasons for a deal, but the real question is how much is Marvell willing to pay up?
Zscaler reiterates guidance, Boeing’s Lockheed Martin win, and other headlines moving the market this morning.
Trump and Canada talk tariff deal, Venezuela oil production and other headlines moving the market this morning.
As peace eludes and perils grow in Middle East, why hasn’t oil run wild … yet? Also, the ‘BUZZ’ on chips and trouble n China.
We added to one holding this week, and locked in outsized gains for two others.