Benefits outstripped wages for a fourth straight quarter as inflation-adjusted compensation fell 0.4% from a year earlier vs. the +0.58% pre-pandemic average.
Futures are pointing to another rough session for large cap indices with the S&P 500 indicated lower by over 1% and the Nasdaq-100 ($QQQ) 2.5%. Again non-Tech is faring better with the Russell 2000 ($RUT) indicated lower by just under a half percent.
Otherwise though catalysts are light today:
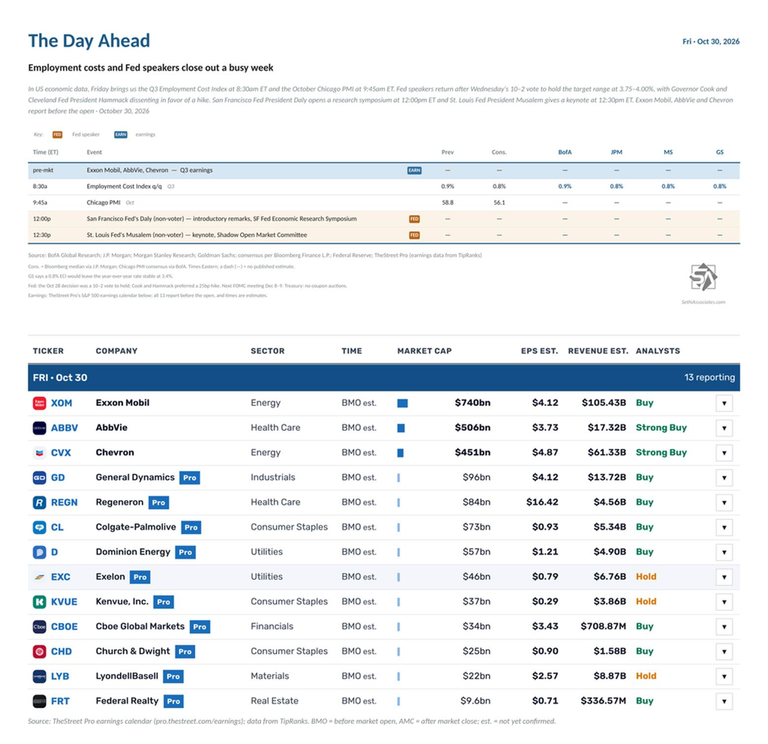
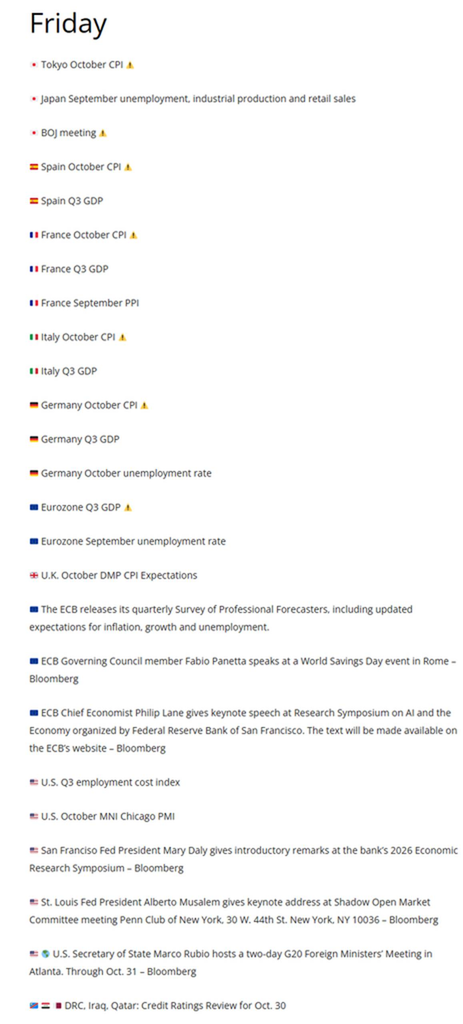
In US economic data, Friday brings us the Q3 Employment Cost Index (the Fed’s preferred wage inflation metric) and the October Chicago PMI.
Fed speakers return after Wednesday’s 10-2 decision to hold the fed funds target range at 3.75%-4%, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of a 25bp hike. San Francisco Fed President Daly gives introductory remarks at the San Francisco Fed’s Economic Research Symposium at 12pm ET, and St. Louis Fed President Musalem delivers a keynote address at the Shadow Open Market Committee meeting at 12:30pm ET.
There are no non-Bill (>1yr in maturity) US Treasury auctions.
13 S&P 500 components report, all before the open, three of them with market caps over $100bn:
Before the open: Exxon Mobil ($XOM), AbbVie ($ABBV), Chevron ($CVX), General Dynamics ($GD), Regeneron ($REGN), Colgate-Palmolive ($CL), Dominion Energy ($D), Exelon ($EXC), Kenvue ($KVUE), Cboe Global Markets ($CBOE), Church & Dwight ($CHD), LyondellBasell ($LYB) and Federal Realty ($FRT)
Outside the US, AstraZeneca ($AZN), Sanofi ($SNY) and BP ($BP) report.
Ex-US is a busier day, with highlights including a decision from the Bank of Japan, Japan October Tokyo CPI, September jobless rate, job-to-applicant ratio, retail sales, industrial production and housing starts, UK October Lloyds Business Barometer, the ECB Survey of Professional Forecasters, Germany October CPI, unemployment claims rate, Q3 GDP and September import price index, France October CPI, Q3 GDP, private sector payrolls, September consumer spending and PPI, Italy Q3 GDP and October CPI, Eurozone Q3 GDP and September unemployment rate, Spain October CPI and Canada August GDP. The G20 foreign ministers also meet in Atlanta (through October 31).
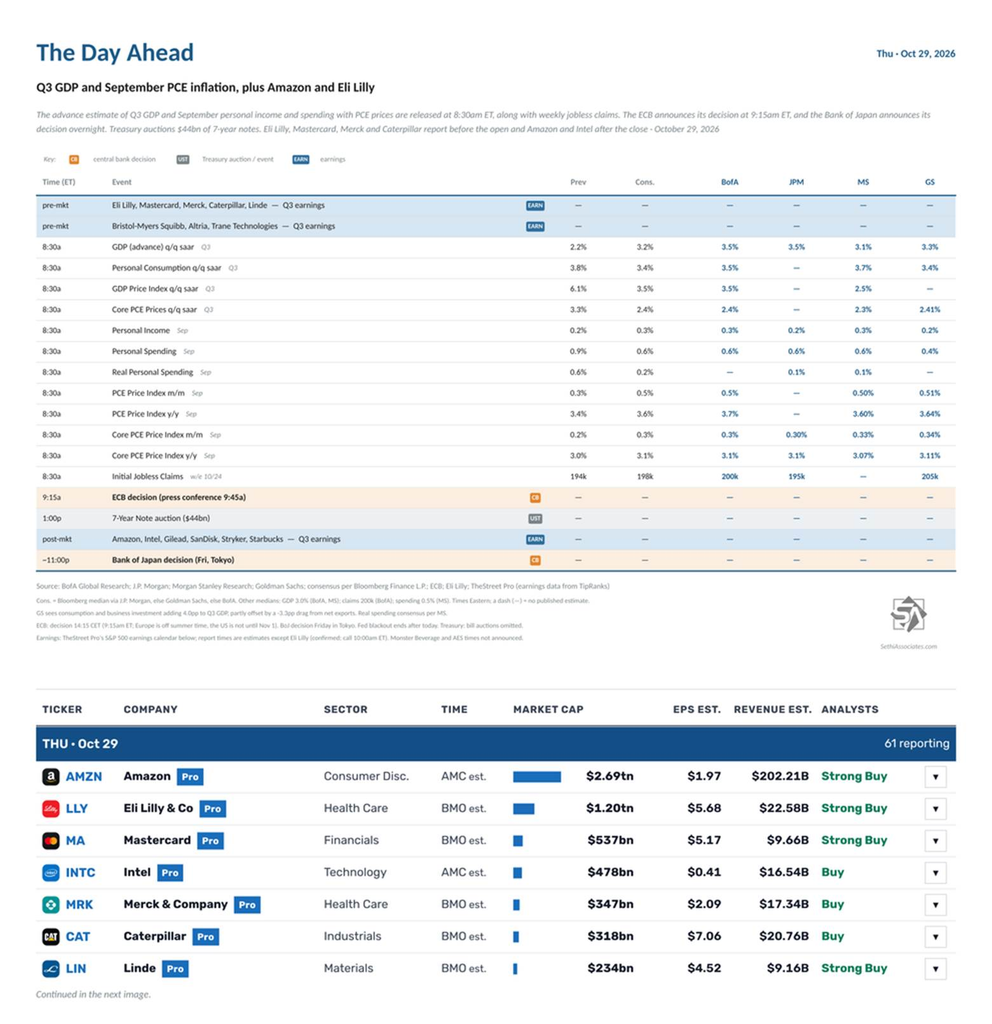
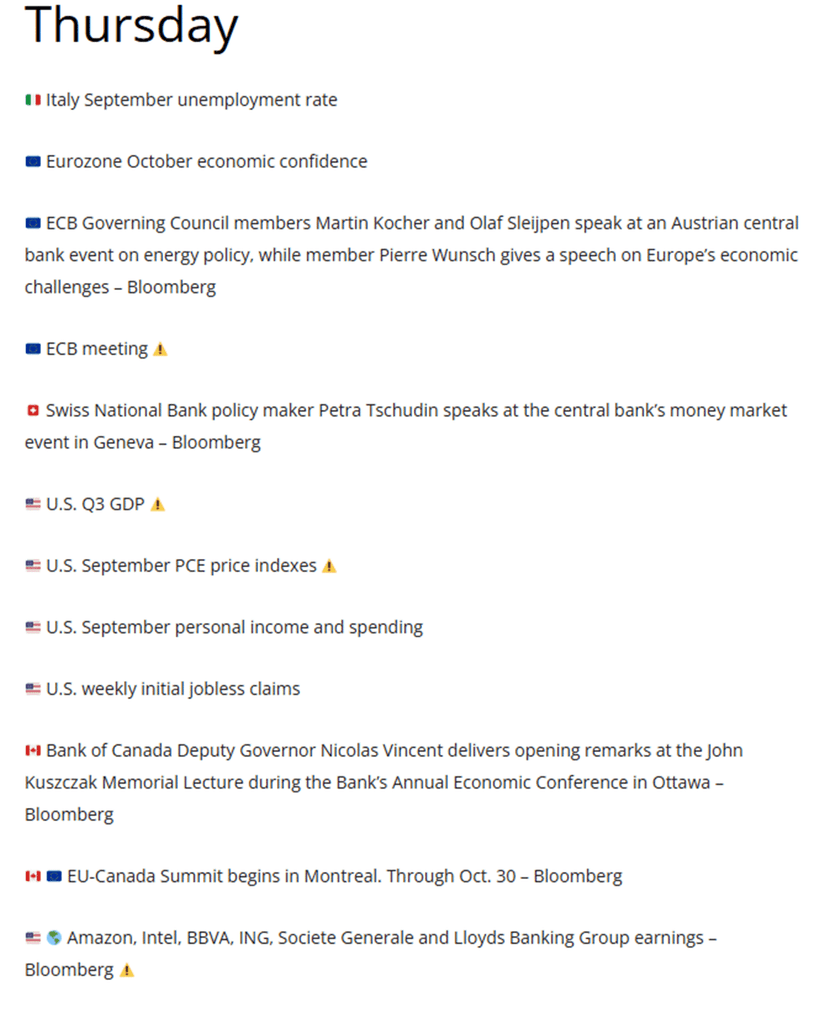
US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.
The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.
The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.
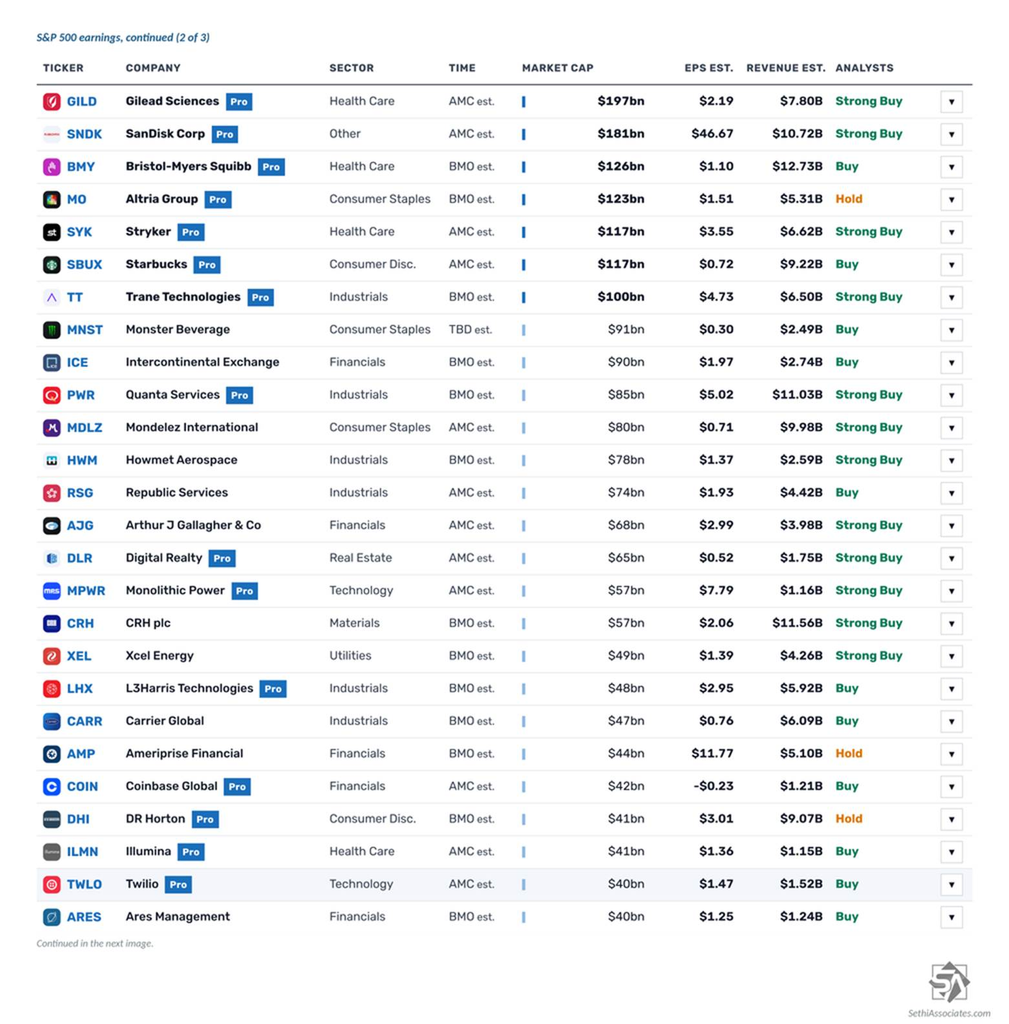
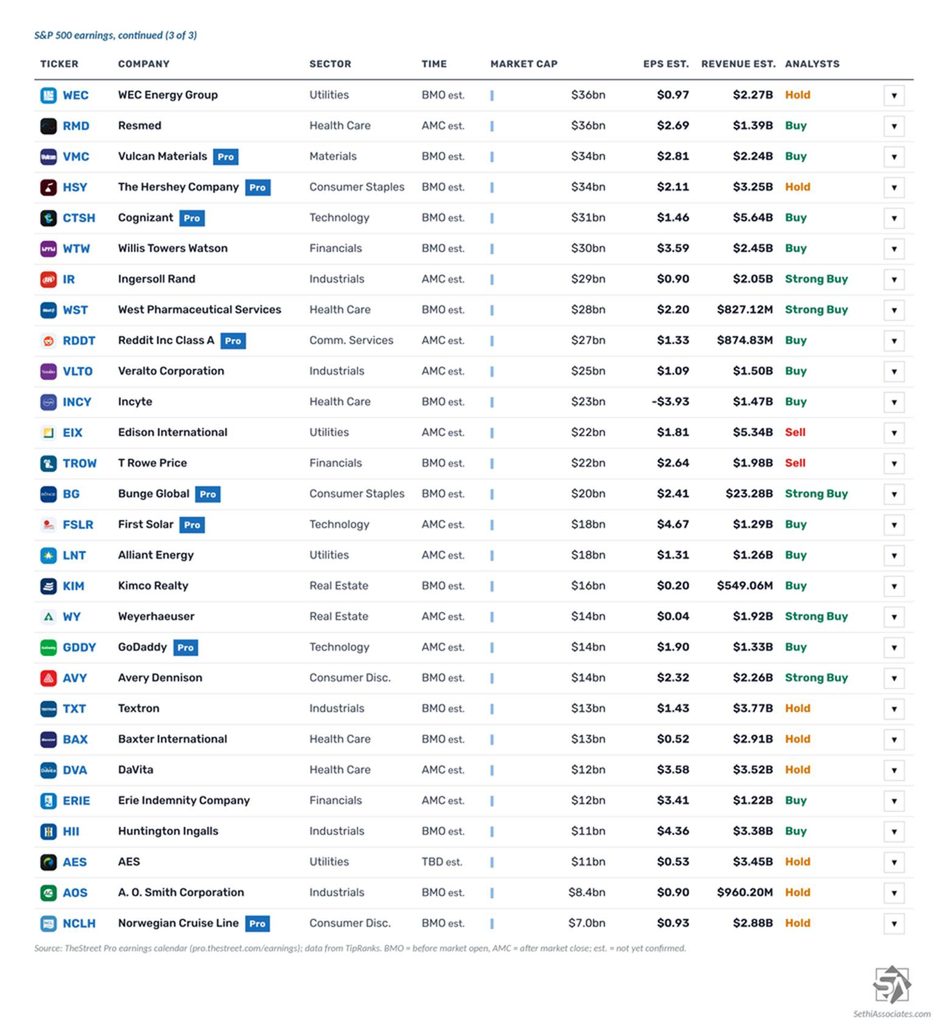
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:
Before the open: Eli Lilly ($LLY), Mastercard ($MA), Merck ($MRK), Caterpillar ($CAT), Linde ($LIN), Bristol Myers Squibb ($BMY), Altria ($MO), Trane Technologies ($TT), Intercontinental Exchange ($ICE), Quanta Services ($PWR), Howmet Aerospace ($HWM), CRH ($CRH), Xcel Energy ($XEL), L3Harris ($LHX), Carrier ($CARR), Ameriprise ($AMP), D.R. Horton ($DHI), Ares Management ($ARES), WEC Energy ($WEC), Vulcan Materials ($VMC), Hershey ($HSY), Cognizant ($CTSH), WTW ($WTW), West Pharmaceutical ($WST), Incyte ($INCY), T. Rowe Price ($TROW), Bunge ($BG), Kimco Realty ($KIM), Avery Dennison ($AVY), Textron ($TXT), Baxter ($BAX), Huntington Ingalls ($HII), A.O. Smith ($AOS) and Norwegian Cruise Line ($NCLH)
After the close: Amazon ($AMZN), Intel ($INTC), Gilead ($GILD), SanDisk ($SNDK), Stryker ($SYK), Starbucks ($SBUX), Mondelez ($MDLZ), Republic Services ($RSG), Arthur J. Gallagher ($AJG), Digital Realty ($DLR), Monolithic Power ($MPWR), Coinbase ($COIN), Illumina ($ILMN), Twilio ($TWLO), ResMed ($RMD), Ingersoll Rand ($IR), Reddit ($RDDT), Veralto ($VLTO), Edison International ($EIX), First Solar ($FSLR), Alliant Energy ($LNT), Weyerhaeuser ($WY), GoDaddy ($GDDY), DaVita ($DVA) and Erie Indemnity ($ERIE)
Time not announced: Monster Beverage ($MNST) and AES ($AES)
Outside the US, Shell ($SHEL), TotalEnergies ($TTE) and Volkswagen ($VWAGY) report.
Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.
The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
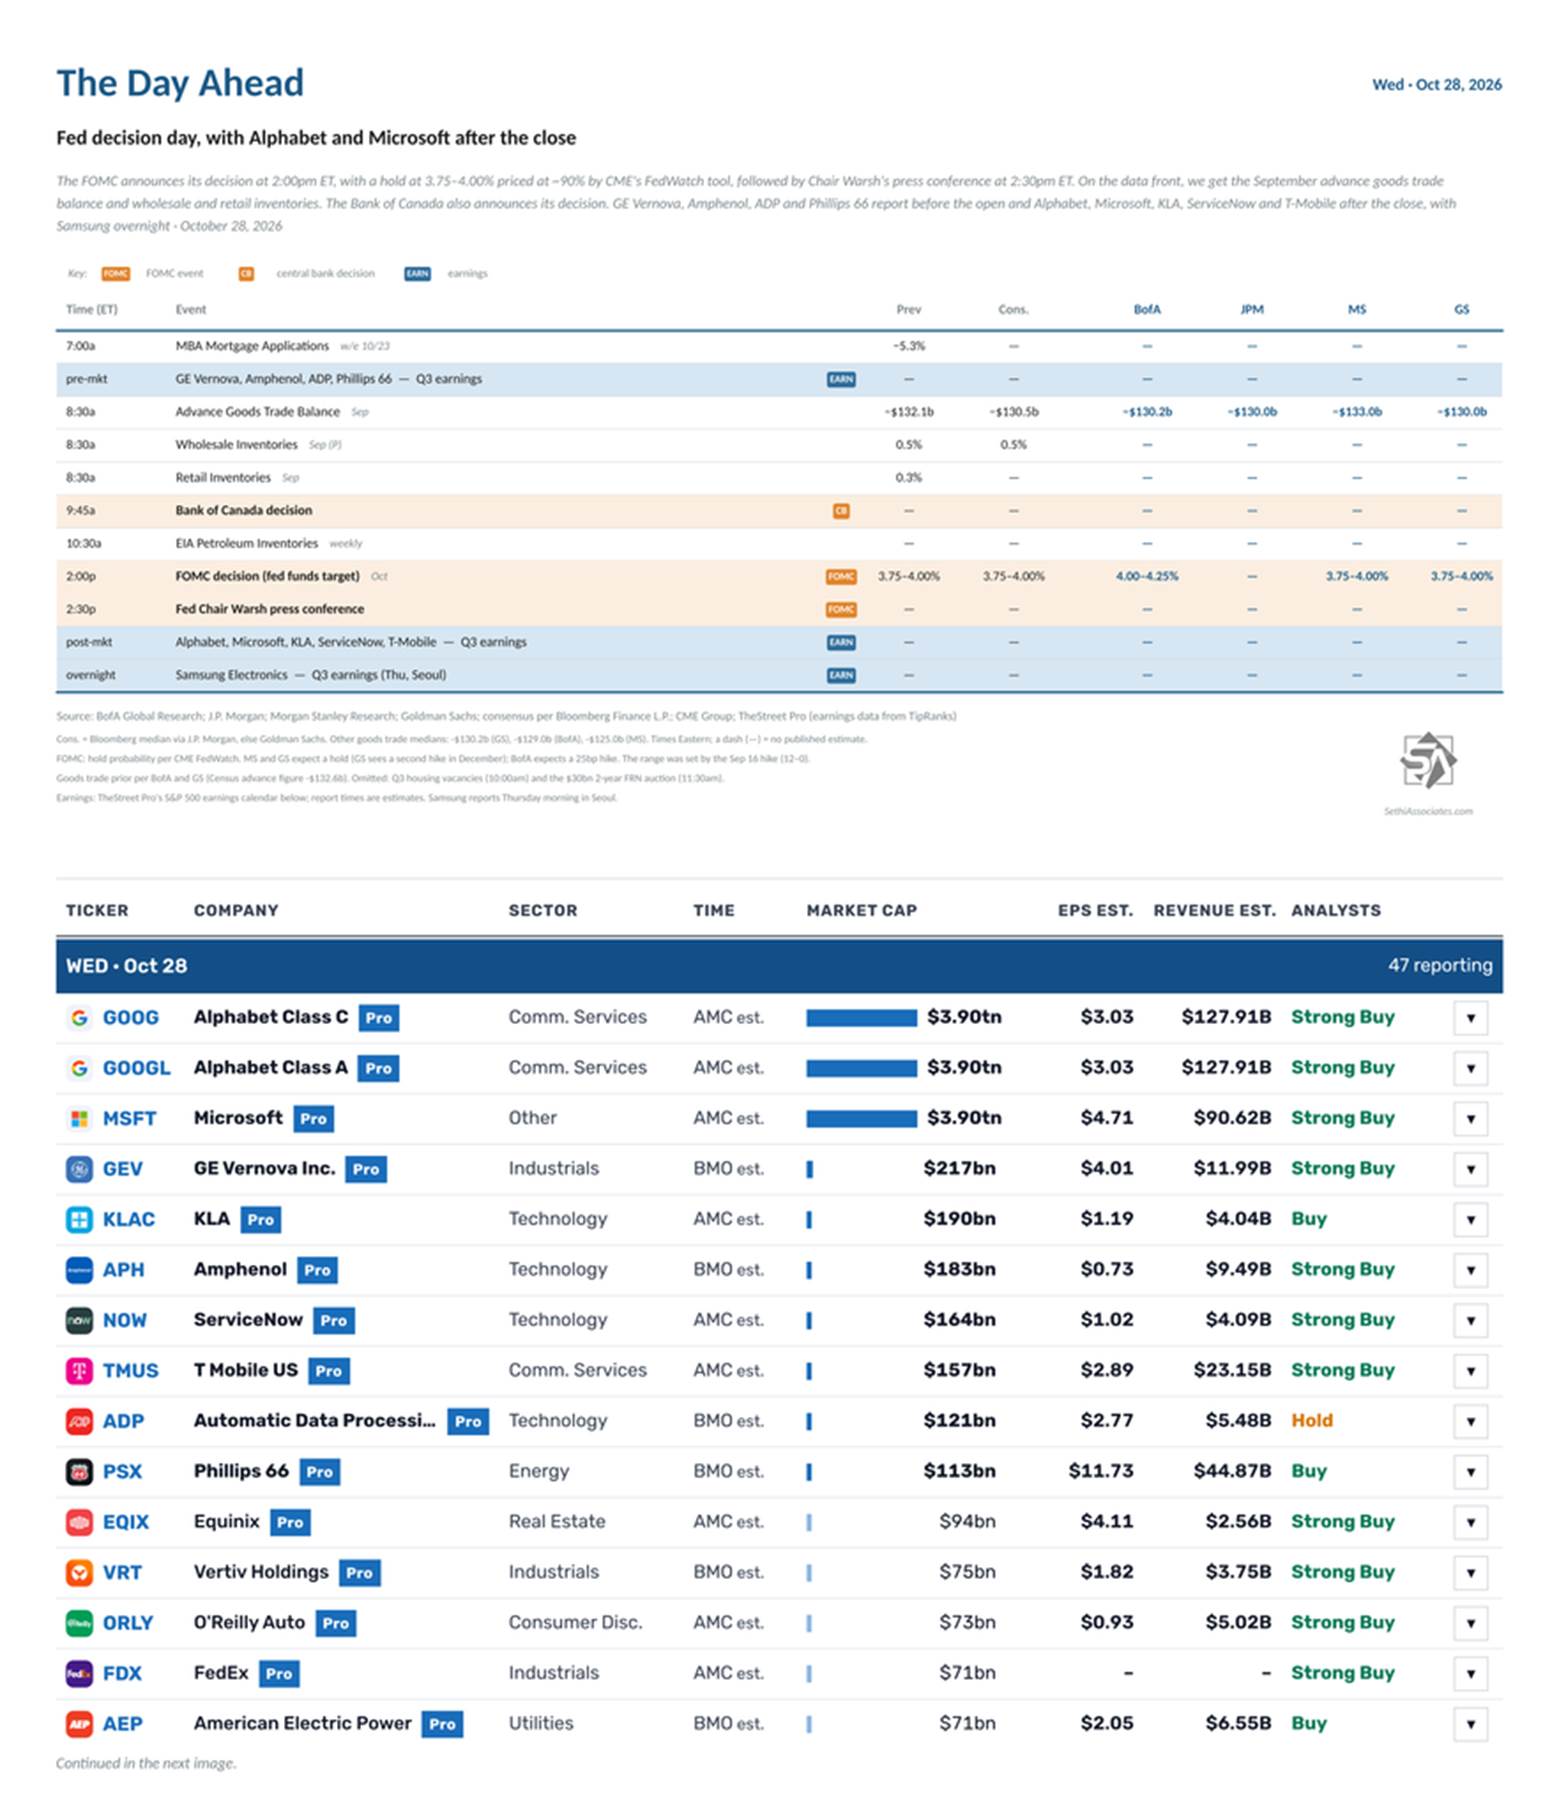
US economic data is light Wednesday, with just the September advance goods trade balance and wholesale and retail inventories plus weekly MBA mortgage applications and EIA petroleum inventories.
The FOMC takes center stage announcing its decision at 2pm ET, with a hold priced at ~93% by CME’s FedWatch tool, followed by Chair Warsh’s press conference at 2:30pm ET.
The only Non-Bill (>1yr in maturity) US Treasury auction is a $30B 2-year floating-rate note (not followed due to its floating nature).
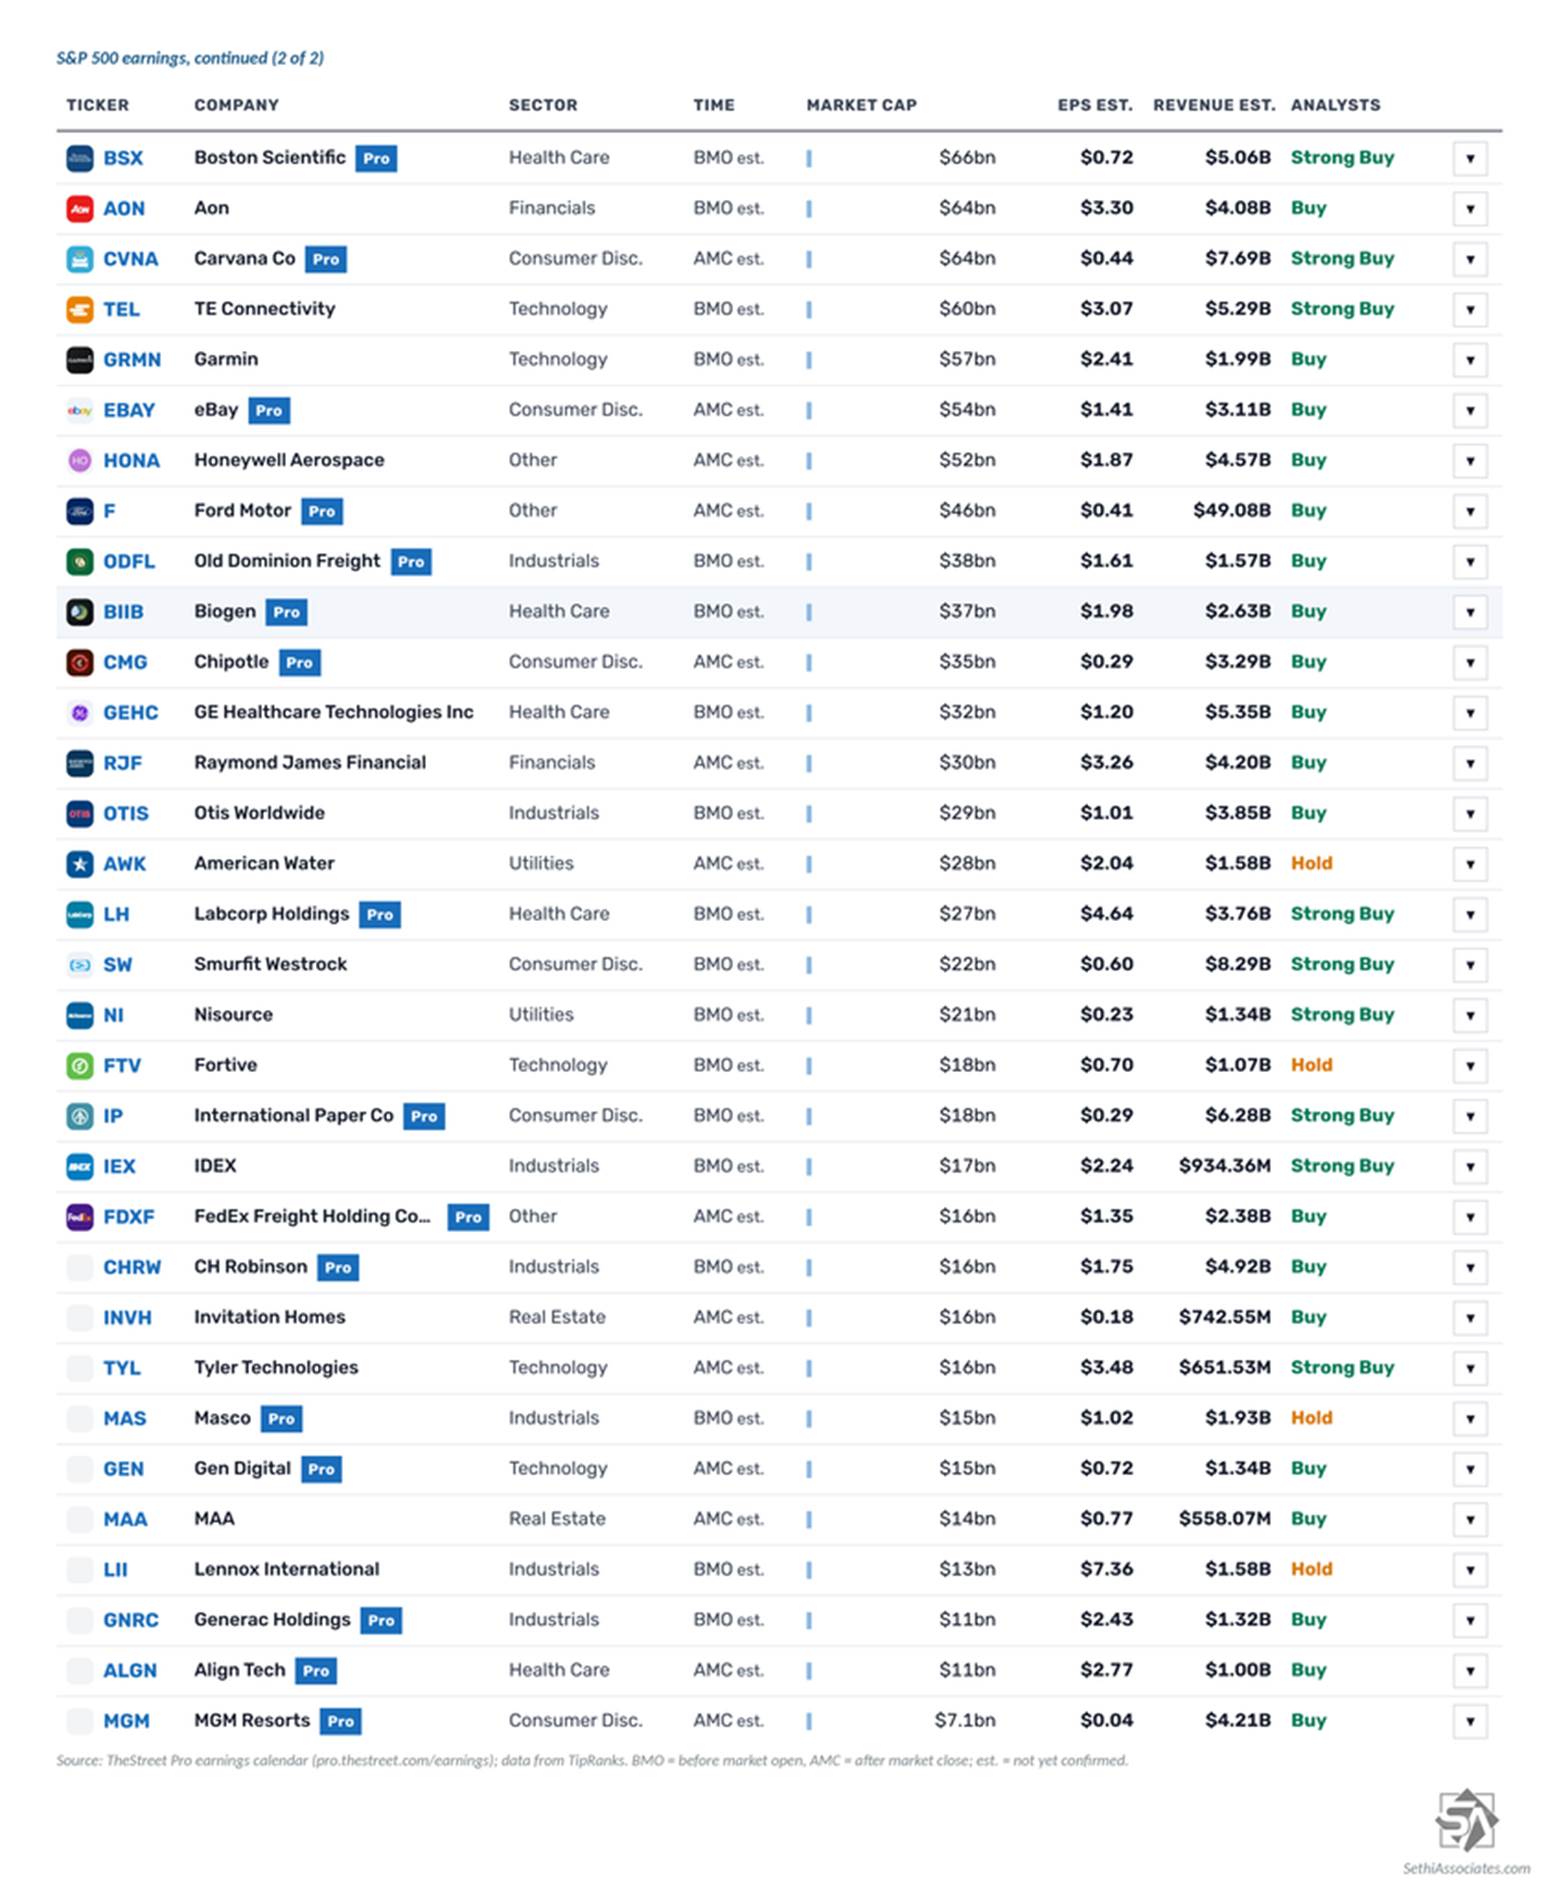
Alphabet and Microsoft lead 46 S&P 500 components reporting, nine of them with market caps over $100B:
Before the open: GE Vernova ($GEV), Amphenol ($APH), ADP ($ADP), Phillips 66 ($PSX), Vertiv ($VRT), American Electric Power ($AEP), Boston Scientific ($BSX), Aon ($AON), TE Connectivity ($TEL), Garmin ($GRMN), Old Dominion Freight Line ($ODFL), Biogen ($BIIB), GE HealthCare ($GEHC), Otis Worldwide ($OTIS), Labcorp ($LH), Smurfit Westrock ($SW), NiSource ($NI), Fortive ($FTV), International Paper ($IP), IDEX ($IEX), C.H. Robinson ($CHRW), Masco ($MAS), Lennox International ($LII) and Generac ($GNRC)
After the close: Alphabet ($GOOGL), Microsoft ($MSFT), KLA ($KLAC), ServiceNow ($NOW), T-Mobile ($TMUS), Equinix ($EQIX), O’Reilly Automotive ($ORLY), FedEx ($FDX), Carvana ($CVNA), eBay ($EBAY), Honeywell Aerospace ($HONA), Ford ($F), Chipotle ($CMG), Raymond James ($RJF), American Water Works ($AWK), FedEx Freight ($FDXF), Invitation Homes ($INVH), Tyler Technologies ($TYL), Gen Digital ($GEN), MAA ($MAA), Align Technology ($ALGN) and MGM Resorts ($MGM)
Ex-US highlights include decisions from central banks in Canada and New Zealand, Germany November GfK consumer confidence, France Q3 total jobseekers, Italy August industrial sales and September PPI, and Australia September CPI.
The Conference Board’s index jumped to 91.7, the highest since June and far above the 81.0 expected, even as consumers planned less spending on services and durable goods.
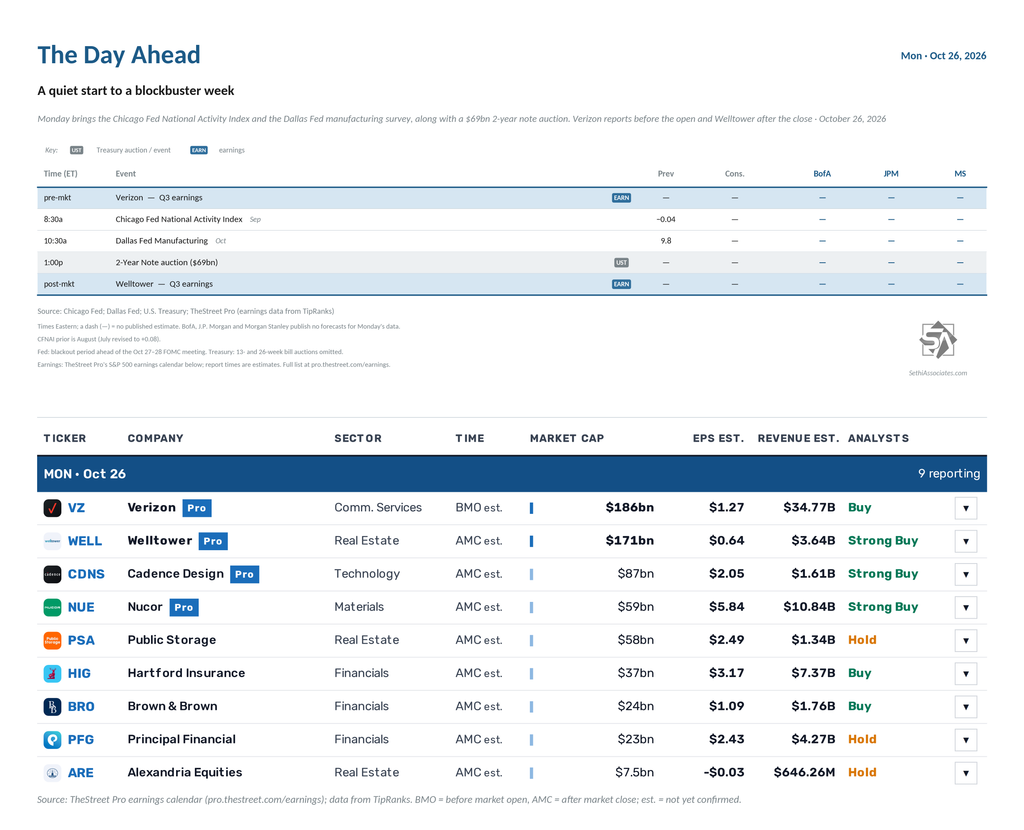
It’s a quiet start to a busy week for US economic data, with October’s Dallas Fed manufacturing survey and September’s Chicago Fed National Activity Index the only reports.
The Fed remains in its blackout period ahead of the October 27–28 FOMC meeting, so there are no Fed speakers.
Non-Bill (>1yr in maturity) US Treasury auctions include a $69bn 2-year note auction.
Nine S&P 500 components report, two of them with market caps over $100bn:
Before the open: Verizon ($VZ)
After the close: Welltower ($WELL), Cadence Design Systems ($CDNS), Nucor ($NUE), Public Storage ($PSA), The Hartford ($HIG), Brown & Brown ($BRO), Principal Financial ($PFG) and Alexandria Real Estate Equities ($ARE)