Deckers Down, Nokia Up: Upside, Downside Movers in the Morning

Upside
– $CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)
– $NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)
– $LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)
– $BAH +1.9% (Q2 profit beat offset a slight revenue miss)
– $TECK +1.7% (copper-linked stocks rise as copper prices advance)
Downside
– $FLG -8.3% (Q3 profit and revenue missed expectations)
– $DECK -8.2% (quarterly sales missed and the FY sales outlook was cut, while the higher EPS guide relied partly on tariff refunds)
– $INFY -8.2% (FY revenue-growth guidance was cut to 1%-2% despite strong large-deal wins)
– $ALV -5.2% (Q3 profit and sales missed as cost headwinds weighed on results)
– $CRDO -4.6% (AI-infrastructure hardware weakness continues amid concerns over the pace and returns of sector spending)
– $TMUS -4.5%, T -4.4%, VZ -3.9% (wireless carriers fall after a report that SpaceX is pursuing a nationwide cellular-infrastructure program)
– $BE -3.9% (record results and raised guidance were not enough after a major AI-power rally)
– $MRNA -3.7% (extends losses following leaked cancer-vaccine data that disappointed investors)
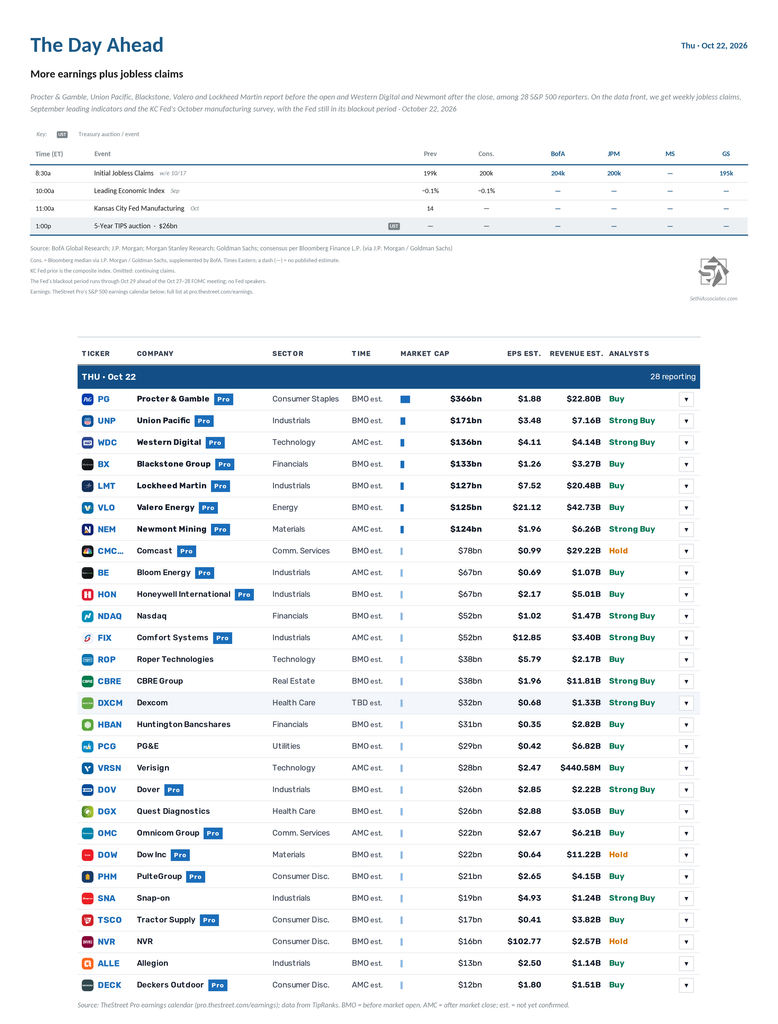
– $FIX -3.1% (earnings beat, but the CFO retirement and elevated expectations drive a sell-the-news reaction)
– $ACN -2.7%, $CTSH -2.0% (IT-services names fall after Infosys cut its FY growth outlook)
– $WDC -1.9%, STX -1.4% (storage names retreat despite WDC’s beat-and-raise report as elevated expectations trigger profit-taking)