Tech Weighs on the Market, Midterms and Inflation Data Around the Corner: 8 Key Items Shaping the Stock Market Friday

Microsoft’s debt deal, Binance’s $6.3 billion hack and other headlines moving the market this morning.
Microsoft’s debt deal, Binance’s $6.3 billion hack and other headlines moving the market this morning.
Futures are pointing to another rough session for large cap indices with the S&P 500 indicated lower by over 1% and the Nasdaq-100 ($QQQ) 2.5%. Again non-Tech is faring better with the Russell 2000 ($RUT) indicated lower by just under a half percent.
Otherwise though catalysts are light today:
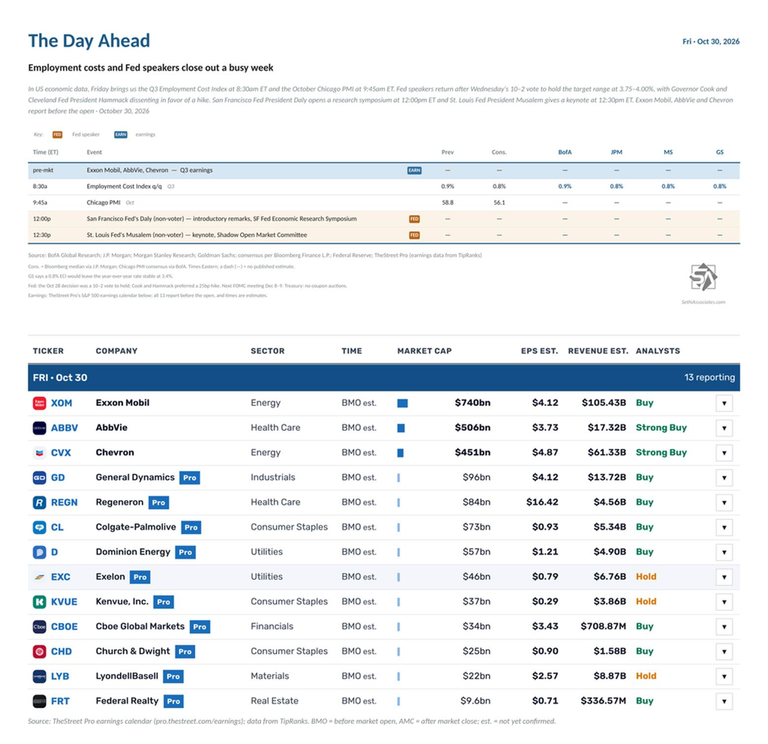
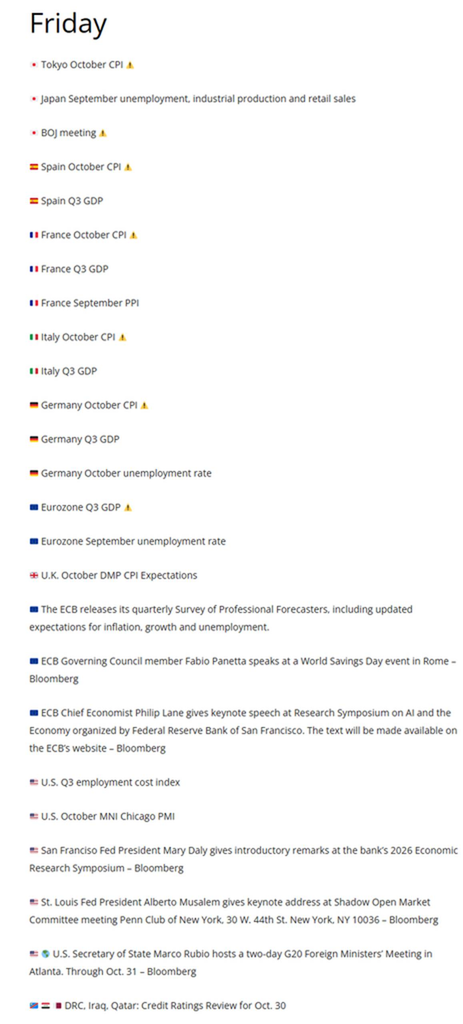
In US economic data, Friday brings us the Q3 Employment Cost Index (the Fed’s preferred wage inflation metric) and the October Chicago PMI.
Fed speakers return after Wednesday’s 10-2 decision to hold the fed funds target range at 3.75%-4%, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of a 25bp hike. San Francisco Fed President Daly gives introductory remarks at the San Francisco Fed’s Economic Research Symposium at 12pm ET, and St. Louis Fed President Musalem delivers a keynote address at the Shadow Open Market Committee meeting at 12:30pm ET.
There are no non-Bill (>1yr in maturity) US Treasury auctions.
13 S&P 500 components report, all before the open, three of them with market caps over $100bn:
Before the open: Exxon Mobil ($XOM), AbbVie ($ABBV), Chevron ($CVX), General Dynamics ($GD), Regeneron ($REGN), Colgate-Palmolive ($CL), Dominion Energy ($D), Exelon ($EXC), Kenvue ($KVUE), Cboe Global Markets ($CBOE), Church & Dwight ($CHD), LyondellBasell ($LYB) and Federal Realty ($FRT)
Outside the US, AstraZeneca ($AZN), Sanofi ($SNY) and BP ($BP) report.
Ex-US is a busier day, with highlights including a decision from the Bank of Japan, Japan October Tokyo CPI, September jobless rate, job-to-applicant ratio, retail sales, industrial production and housing starts, UK October Lloyds Business Barometer, the ECB Survey of Professional Forecasters, Germany October CPI, unemployment claims rate, Q3 GDP and September import price index, France October CPI, Q3 GDP, private sector payrolls, September consumer spending and PPI, Italy Q3 GDP and October CPI, Eurozone Q3 GDP and September unemployment rate, Spain October CPI and Canada August GDP. The G20 foreign ministers also meet in Atlanta (through October 31).
From Christophe Barraud’s international Week Ahead rundown:
Over 400 of the S&P 500’s components were higher even as the index ended lower and the Russell 2000 gained for a fourth day while Amazon and Intel dropped after hours
Schneider Electric and other M&A deals, September Service PMI inflation data and other headlines moving the market this morning.
These are the items we’re watching that could trigger a price target increase.
Euro-area inflation rises in July, Amazon soars, SpaceX-Tesla chatter, and other headlines moving stocks this morning.