The Week Ahead: CPI and Equity Flows Test a Shaken Market


After its worst week since April 2025, the S&P 500 looks to bounce back. Positioning is cleaner, but are traders ready to get back in?
After its worst week since April 2025, the S&P 500 looks to bounce back. Positioning is cleaner, but are traders ready to get back in?
A Democratic sweep of Congress supercharged the rotation trade, with hyperscalers joining a rally that lifted almost everything except semiconductors and AI power and data center names.
– $ALIT +23% (Q3 exceeded expectations for a third straight quarter and the full-year outlook was raised)
– $DUOL +20% (bookings beat, daily-user growth accelerated to 29% and full-year guidance was raised)
– $CPSH +19% (record Q3 revenue, margin expansion and the first tungsten-alloy order from a defense contractor)
– $HELE +16% (received a non-binding $37-per-share cash acquisition proposal)
– $RIOT +15% (signed a 910-MW AI-campus lease carrying approximately $28 billion of initial-term contract value)
– $OUST +13% (record Q3 revenue rose 50%, the Q4 outlook was strong and Cantor Fitzgerald upgraded to Overweight)
– $FTCI +12% (Q3 revenue rose 25% sequentially, backlog reached roughly $640 million and Q4 guidance implies 46% sequential growth)
– $NVTS +12% (Q3 beat, double-digit sequential Q4 growth was guided and two brokers upgraded to Buy)
– $HL +11% (Q3 profit increased and production guidance was revised as precious-metal prices rallied)
– $XYZ +9.7% (Q3 beat across key metrics, the 2026 outlook was raised and initial 2027 targets topped expectations)
– $OSCR +9.6%, $MOH +5.8%, $HCA +6.1%, $CNC +4.9% (health insurers and hospital operators rise after the Democratic sweep improved prospects for healthcare spending and ACA support)
– $CDE +7.2%, $AG +6.7%, $PAAS +6.3%, $EQX +6.7% (precious-metals miners rise as gold and silver jump on dollar weakness and lower yields)
– $CSIQ +7.1%, $FSLR +7.3%, $RUN +7.0% (solar names rally after the Democratic sweep improved expectations for renewable-energy policy support)
– $SAN +6.6%, $DB +6.9%, $ING +5.7%, $LYG +5.0%, $HSBC +5.4% (European bank ADRs rise amid a post-election rotation into lenders and a weaker dollar)
– $NVO +5.3% (adjusted Q3 profit beat and the full-year sales and operating-profit outlook was raised on stronger GLP-1 demand)
– $ANET +4.5% (Q3 revenue surged 59% and substantially exceeded guidance, with a strong Q4 outlook)
– $EW +3.5% (Truist upgrades to Buy after positive PROGRESS trial results expanded the TAVR opportunity)
– $CPNG +2.6% (constant-currency sales beat guidance, Q4 margins are expected to improve and Citi upgraded to Buy)
– $MCD +2.2% (Q3 profit beat as international strength offset sluggish US sales)
– $DOX -36% (FY27 guidance was far below expectations as a dispute with a major customer threatens revenue; Oppenheimer downgraded)
– $NRIX -33% (partner discontinued the Phase 1 STAT6-degrader trial and terminated the program, eliminating related milestones and royalties)
– $FIS -22% (Q3 EPS missed despite a revenue beat, while the CFO departure added uncertainty)
– $TBLA -21% (Q3 revenue missed and Q4 and full-year sales guidance came in well below consensus)
– $CIFR -14% (KBW downgraded to Market Perform as election results increased regulatory and permitting risk for data-center expansion)
– $FIX -14%, CRWV -6.6%, VST -8.7%, VRT -6.8%, GEV -6.5%, ALAB -6.8% (AI-infrastructure and power names fall on fears of tighter data-center oversight, permitting delays and reduced buildout)
– $DDOG -12% (Q3 beat, but the Q4 revenue guide was only in line and implied sharp growth deceleration versus elevated expectations)
– $NICE -12% (Q3 beat, but margins compressed sharply, revenue guidance was merely reiterated and a 5% workforce reduction was announced)
– $SWKS -12% (first combined outlook following the Qorvo transaction disappointed as handset softness outweighed expected synergies)
– $DJT -11% (positions tied to Trump’s political fortunes unwind after Democrats swept both chambers of Congress)
– $SEDG -9.1% (Q3 EPS beat, but Q4 revenue guidance was far below consensus)
– $HUT -8.2%, $CLSK -11%, $IREN -5.6% (digital-infrastructure names fall as Democratic victories in key states raise risks to planned data-center capacity)
– $GEO -6.7%, $CXW -5.0% (private-prison operators fall as the Democratic sweep threatens immigration-enforcement spending expectations)
– $TSLA -4.6% (Musk-linked shares absorb a political-risk premium after Democratic victories, including a Texas governor upset)
– $LMT -4.2%, $NOC -3.2%, $RTX -3.1% (defense names fall on expectations that a Democratic Congress may constrain planned military-spending growth)
– $TOST -3.6% (strong operating metrics were offset by mixed EPS headlines and the announced CFO departure)
– $CVS -3.5% (earnings beat and guidance rose, but the anticipated breakup announcement triggered a sell-the-news reaction amid execution and star-rating concerns)
AMD and Super Micro crush earnings, CVS Health splits, and other headlines moving the market this morning.
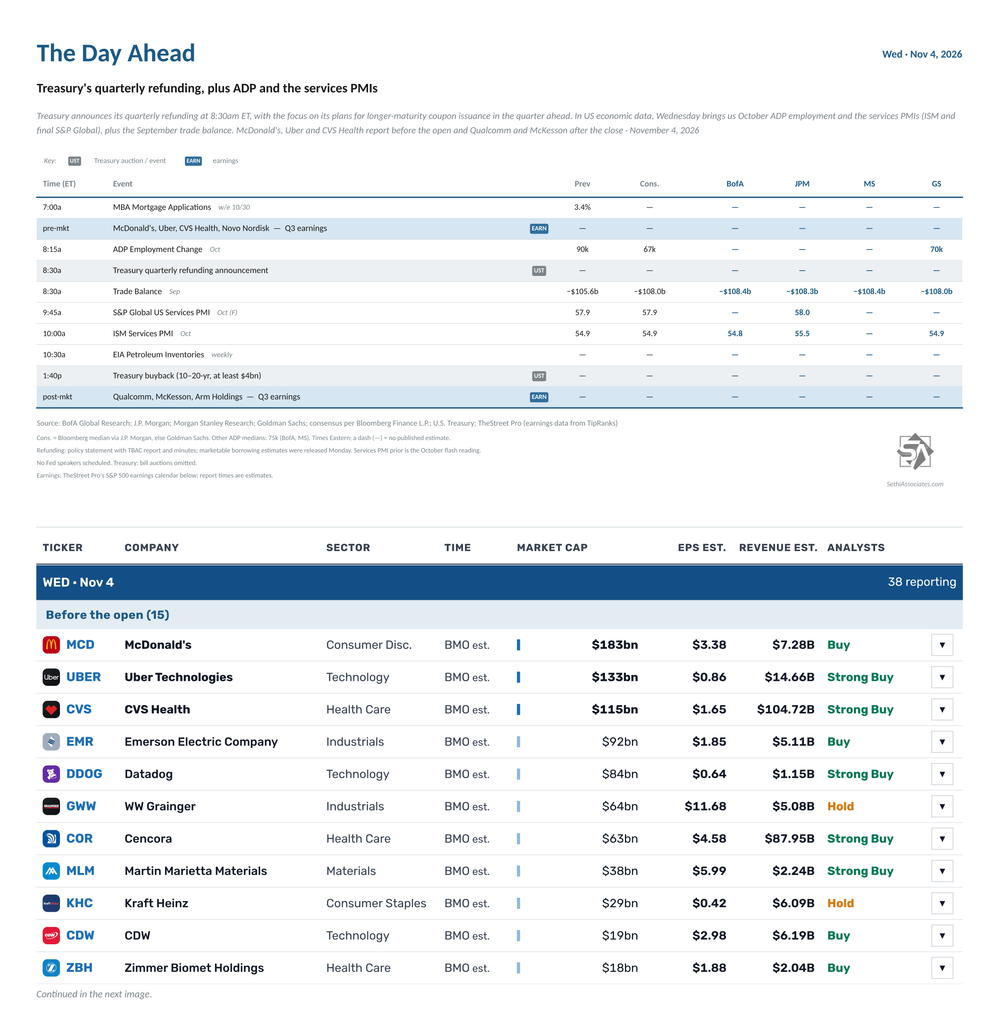
In US economic data, Wednesday brings us October ADP private employment growth and the services PMIs (ISM and final S&P Global), plus the September trade balance. We’ll also get weekly MBA mortgage applications and EIA petroleum inventories.
There are no Fed speakers scheduled.
There are no non-Bill (>1yr in maturity) US Treasury auctions, but Treasury announces its quarterly refunding at 8:30am ET, with the focus on its plans for longer-maturity coupon issuance in the quarter ahead. It also holds a buyback of 10- to 20-year securities in the afternoon.
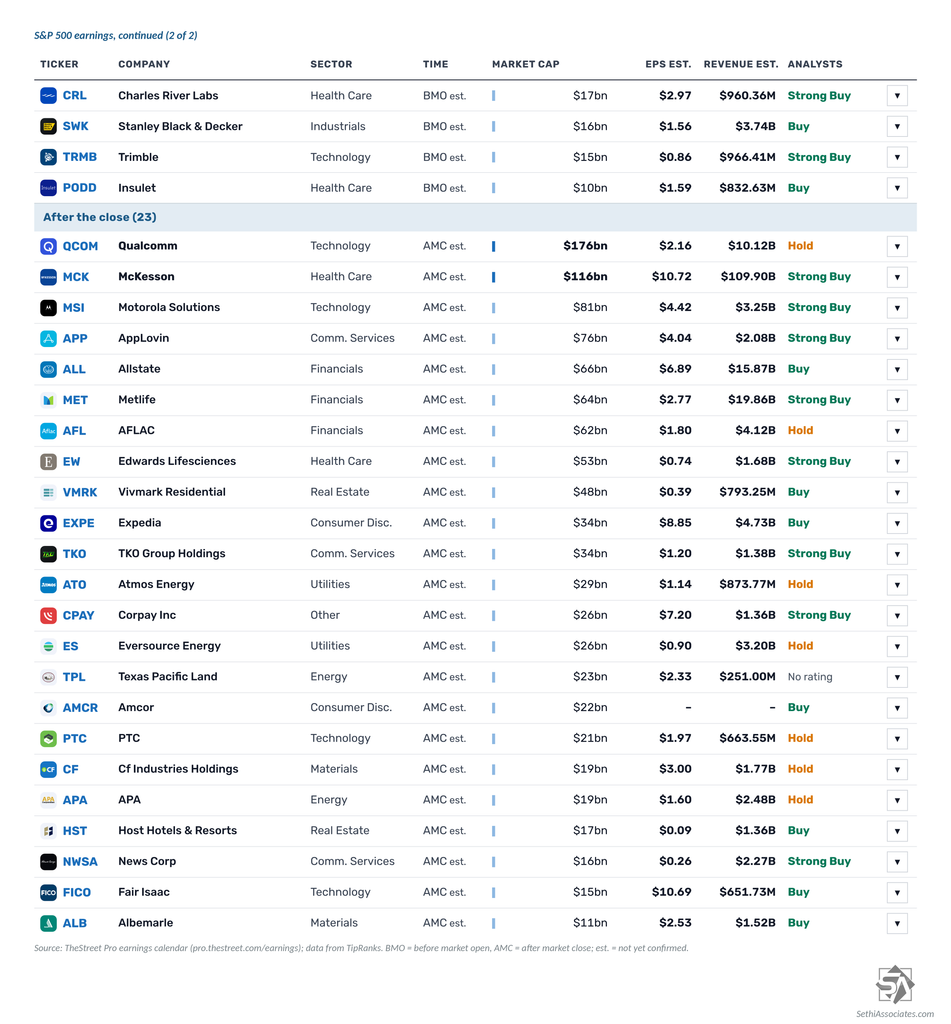
38 S&P 500 components report, five of them with market caps over $100B:
Before the open: McDonald’s ($MCD), Uber ($UBER), CVS Health ($CVS), Emerson Electric ($EMR), Datadog ($DDOG), W.W. Grainger ($GWW), Cencora ($COR), Martin Marietta Materials ($MLM), Kraft Heinz ($KHC), CDW ($CDW), Zimmer Biomet ($ZBH), Charles River Laboratories ($CRL), Stanley Black & Decker ($SWK), Trimble ($TRMB) and Insulet ($PODD)
After the close: Qualcomm ($QCOM), McKesson ($MCK), Motorola Solutions ($MSI), AppLovin ($APP), Allstate ($ALL), MetLife ($MET), Aflac ($AFL), Edwards Lifesciences ($EW), Vivmark Residential ($VMRK), Expedia ($EXPE), TKO Group ($TKO), Atmos Energy ($ATO), Corpay ($CPAY), Eversource Energy ($ES), Texas Pacific Land ($TPL), Amcor ($AMCR), PTC ($PTC), CF Industries ($CF), APA ($APA), Host Hotels & Resorts ($HST), News Corp ($NWSA), Fair Isaac ($FICO) and Albemarle ($ALB)
Outside the S&P 500, Novo Nordisk ($NVO) reports before the open and Arm Holdings ($ARM) and MercadoLibre ($MELI) after the close.
Also, opening arguments are scheduled in a Los Angeles trial over claims that Meta ($META) and Snap ($SNAP) designed their platforms to be addictive and harmful to young users, per Bloomberg.
Ex-US highlights include the final October services PMIs (including China’s RatingDog services PMI), Eurozone October CPI, Spain’s October unemployment rate, UK October official reserves changes and Canada’s September trade balance. There are rate decisions from Sweden’s Riksbank, Poland and Brazil, the ECB releases its wage tracker, ECB Chief Economist Lane and Bank of France Governor Moulin speak, and the Bank of Japan releases the minutes of its September meeting.
Semiconductors led a rebound that broke the S&P 500’s three-day losing streak, but the average stock fell.
Let’s examine the responses to Alphabet’s and Amazon’s earnings and the other factors that led to last week’s ugliness. Also, a bright spot on the charts?
The rotation out of Tech continued last week. Now a packed week headlined by Apple on Monday, Tuesday’s midterm elections, and Friday’s jobs report test a market with thin gamma and CTAs near their sell triggers.
Intel’s record drop leads a cascade in chip names with the S&P 500 and Nasdaq seeing their worst session since June, while defensive buying gave the Consumer Staples ETF its best month on record.
– $VEEA +45.0% (regained full Nasdaq listing compliance following its reverse stock split)
– $XRTX +21.0% (outlined planned FDA IND and Health Canada clinical-trial filings for XRx-026 in gout)
– $SAIQ +19.5% (confirmed an October satellite launch advancing its post-quantum secure-communications roadmap)
– $HUM +14.5% (2027 CMS Star Ratings exceeded its top-quartile revenue goal, with its largest contract returning above the bonus-payment threshold)
– $CLOV +11.5% (PPO plans earned 5 stars and the HMO plan earned 4.5 stars for 2027, strengthening 2028 payment and enrollment economics)
– $CCI +9.5%, SBAC +7.0%, AMT +7.0% (tower operators rally as SPCX’s low-band spectrum deal implies a terrestrial buildout and potential new-tenant demand)
– $FSLY +7.0% (Oppenheimer upgrades to Outperform with a $35 target on AI-traffic growth)
– $AAOI +6.0%, LITE +6.0%, COHR +4.5%, GLW +3.5% (optical names rise after LITE said AI-data-center demand has booked component capacity through early 2029)
– $ECHO +5.0% (SPCX’s additional spectrum purchase reinforces the value of ECHO’s existing spectrum and equity partnership)
– $SPCX +4.0% (agrees to acquire a nationwide 800 MHz spectrum portfolio for about $8B, strengthening its direct-to-device mobile push)
– $ALHC -23.0% (key California HMO contract fell to 3.5 stars, below the CMS quality-bonus threshold)
– $TMUS -7.5%, T -6.5%, VZ -6.0% (wireless carriers slide as SPCX’s nationwide low-band spectrum acquisition raises the threat of direct mobile competition)
– ASTS -3.0% (falls after SPCX acquired spectrum ASTS had pursued, increasing competitive and spectrum-access concerns)
– $CVS -3.0% (only about 69% of Medicare Advantage members are in 4-star-plus plans for 2027, down from 81% for 2026)
– $AAPL -2.5% (no clear fresh catalyst identified; unusually large mega-cap decline despite higher Nasdaq futures)
– $DAL -1.5%, LUV -2.0%, $UAL -1.5% ($DAL missed Q3 profit expectations and sharply cut its FY outlook as surging fuel costs overwhelmed strong demand)