Blue Wave Pops Market, But Can It Overcome Technical Hurdles?: 8 Key Items Shaping the Stock Market Wednesday

AMD and Super Micro crush earnings, CVS Health splits, and other headlines moving the market this morning.
AMD and Super Micro crush earnings, CVS Health splits, and other headlines moving the market this morning.
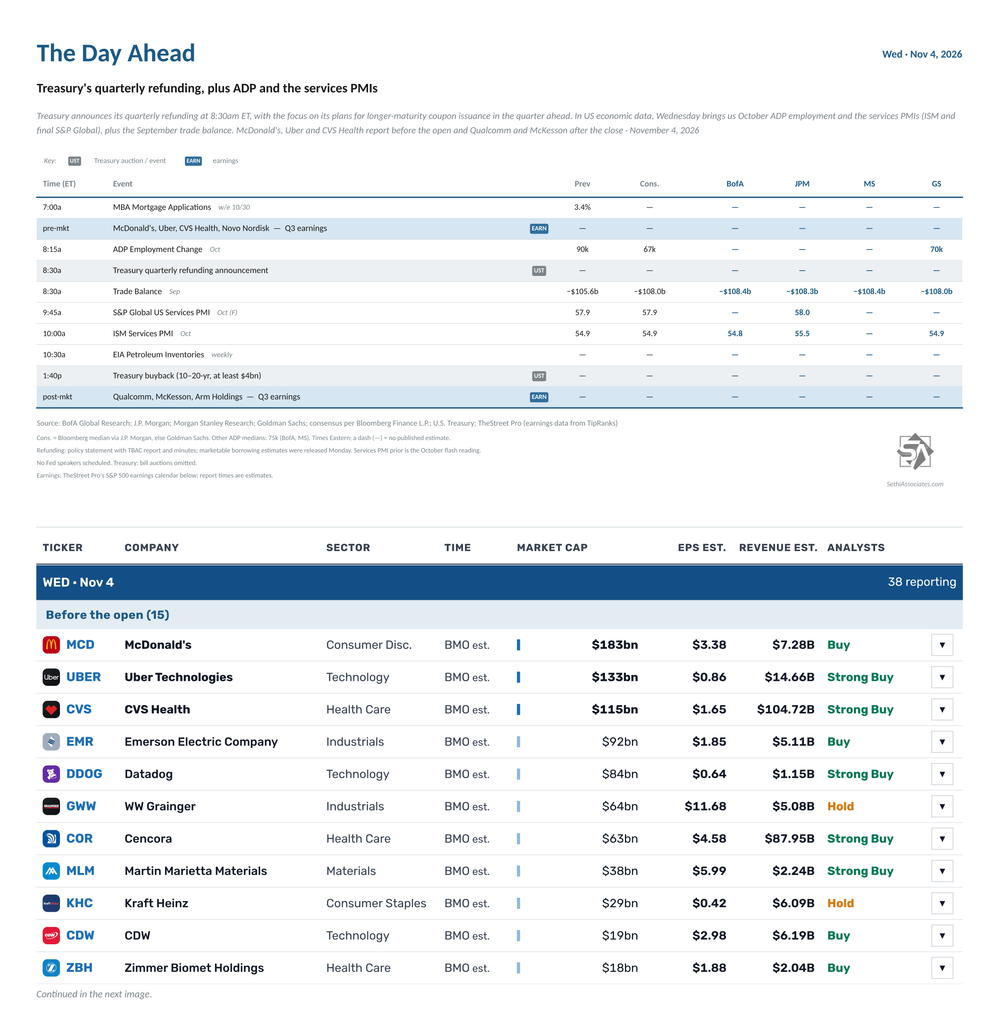
In US economic data, Wednesday brings us October ADP private employment growth and the services PMIs (ISM and final S&P Global), plus the September trade balance. We’ll also get weekly MBA mortgage applications and EIA petroleum inventories.
There are no Fed speakers scheduled.
There are no non-Bill (>1yr in maturity) US Treasury auctions, but Treasury announces its quarterly refunding at 8:30am ET, with the focus on its plans for longer-maturity coupon issuance in the quarter ahead. It also holds a buyback of 10- to 20-year securities in the afternoon.
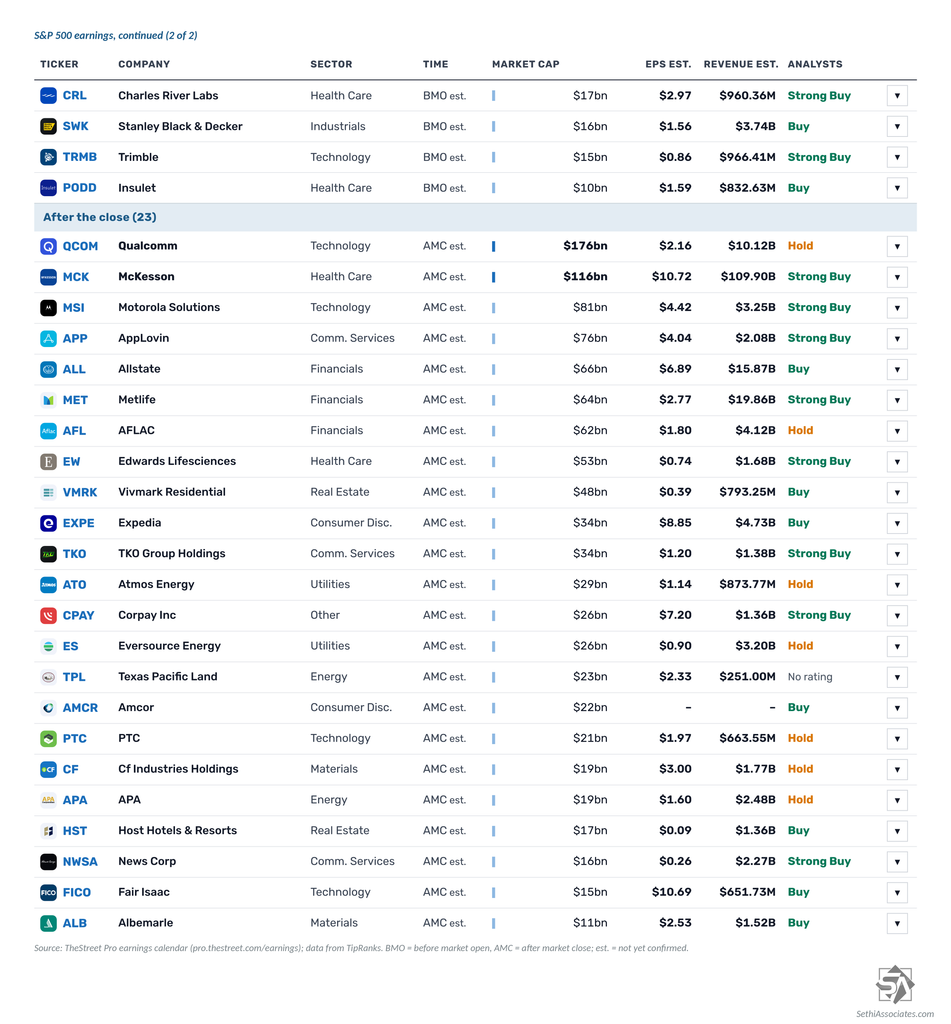
38 S&P 500 components report, five of them with market caps over $100B:
Before the open: McDonald’s ($MCD), Uber ($UBER), CVS Health ($CVS), Emerson Electric ($EMR), Datadog ($DDOG), W.W. Grainger ($GWW), Cencora ($COR), Martin Marietta Materials ($MLM), Kraft Heinz ($KHC), CDW ($CDW), Zimmer Biomet ($ZBH), Charles River Laboratories ($CRL), Stanley Black & Decker ($SWK), Trimble ($TRMB) and Insulet ($PODD)
After the close: Qualcomm ($QCOM), McKesson ($MCK), Motorola Solutions ($MSI), AppLovin ($APP), Allstate ($ALL), MetLife ($MET), Aflac ($AFL), Edwards Lifesciences ($EW), Vivmark Residential ($VMRK), Expedia ($EXPE), TKO Group ($TKO), Atmos Energy ($ATO), Corpay ($CPAY), Eversource Energy ($ES), Texas Pacific Land ($TPL), Amcor ($AMCR), PTC ($PTC), CF Industries ($CF), APA ($APA), Host Hotels & Resorts ($HST), News Corp ($NWSA), Fair Isaac ($FICO) and Albemarle ($ALB)
Outside the S&P 500, Novo Nordisk ($NVO) reports before the open and Arm Holdings ($ARM) and MercadoLibre ($MELI) after the close.
Also, opening arguments are scheduled in a Los Angeles trial over claims that Meta ($META) and Snap ($SNAP) designed their platforms to be addictive and harmful to young users, per Bloomberg.
Ex-US highlights include the final October services PMIs (including China’s RatingDog services PMI), Eurozone October CPI, Spain’s October unemployment rate, UK October official reserves changes and Canada’s September trade balance. There are rate decisions from Sweden’s Riksbank, Poland and Brazil, the ECB releases its wage tracker, ECB Chief Economist Lane and Bank of France Governor Moulin speak, and the Bank of Japan releases the minutes of its September meeting.
Semiconductors led a rebound that broke the S&P 500’s three-day losing streak, but the average stock fell.
– $KOD +60% (pivotal Phase 3 DAYBREAK wet-AMD trial met its primary noninferiority endpoints, with most patients reaching a 24-week dosing interval)
– $ARAY +39% (agrees to explore integrating Samsung NeuroLogica volumetric imaging technology with the CyberKnife platform)
– $MEDS +28% (launches a GLP-1 care app offering telehealth consultations and access to branded medications)
– $WBUY +27% (first-half revenue nearly doubled, gross profit rose 132% and the net loss narrowed)
– $MTEK +21% (receives a record $10 million order for advanced video systems on next-generation airborne defense platforms)
– $AMPX +12% (wins a Defense Department grant of up to $75 million for domestic high-energy-density battery production, with about $22 million obligated initially)
– $SRFM +7.1% (selected as a participating airspace user in the FAA SMART program)
– $NTES +4.6% (no clear fresh catalyst identified; unusually large, liquid premarket move)
– $SM +2.6%, FRO +2.9%, APA +2.5%, OXY +1.7%, XOM +1.5%, CVX +1.5% (energy names rise as crude advances after the US rejected Iran’s conditions for reopening the Strait of Hormuz)
– $CF +2.4% (Rothschild Redburn upgrades to Neutral from Sell, citing a tighter nitrogen-market outlook)
– $GFI -13% (confirms a rejected A$27-per-share cash-and-stock proposal for Northern Star that would leave target holders owning about 33% of the combined company)
– $MNOV -12% (Phase 2 trial failed to show a statistically significant triglyceride benefit versus placebo at Week 24)
– $AU -5.6%, AG -4.5%, CDE -5.1%, HL -4.9%, EGO -4.6%, NEM -4.0% (precious-metals miners fall as gold and silver tumble on a stronger dollar, rising yields and increased Fed rate-hike expectations)
– $FCX -3.3%, SCCO -3.4%, HBM -3.8% (base-metal miners fall as the stronger dollar and rising yields pressure commodity prices)
– $META -2.7% (pulls back after last week’s sharp AI-led rally as rising Treasury yields pressure megacap growth stocks)
– $BE -2.6%, GLW -2.0%, MOD -3.0% (data-center infrastructure names retreat in the higher-yield risk-off tape)
– $CRCL -2.0% (crypto-linked shares weaken as Bitcoin falls about 2%)
– $TTMI -1.8%, CRDO -2.5%, SKHY -3.3%, INTC -2.4%, ARM -2.1%, SNDK -2.7% (high-beta chip and memory names retreat as oil-driven inflation fears lift Treasury yields and pressure the Nasdaq tape)