Deckers Down, Nokia Up: Upside, Downside Movers in the Morning

Upside

– $CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)

– $NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)

– $LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)

– $BAH +1.9% (Q2 profit beat offset a slight revenue miss)

– $TECK +1.7% (copper-linked stocks rise as copper prices advance)

Downside

– $FLG -8.3% (Q3 profit and revenue missed expectations)

– $DECK -8.2% (quarterly sales missed and the FY sales outlook was cut, while the higher EPS guide relied partly on tariff refunds)

– $INFY -8.2% (FY revenue-growth guidance was cut to 1%-2% despite strong large-deal wins)

– $ALV -5.2% (Q3 profit and sales missed as cost headwinds weighed on results)

– $CRDO -4.6% (AI-infrastructure hardware weakness continues amid concerns over the pace and returns of sector spending)

– $TMUS -4.5%, T -4.4%, VZ -3.9% (wireless carriers fall after a report that SpaceX is pursuing a nationwide cellular-infrastructure program)

– $BE -3.9% (record results and raised guidance were not enough after a major AI-power rally)

– $MRNA -3.7% (extends losses following leaked cancer-vaccine data that disappointed investors)

– $FIX -3.1% (earnings beat, but the CFO retirement and elevated expectations drive a sell-the-news reaction)

– $ACN -2.7%, $CTSH -2.0% (IT-services names fall after Infosys cut its FY growth outlook)

– $WDC -1.9%, STX -1.4% (storage names retreat despite WDC’s beat-and-raise report as elevated expectations trigger profit-taking)

A Look at Wednesday

From my evening update:

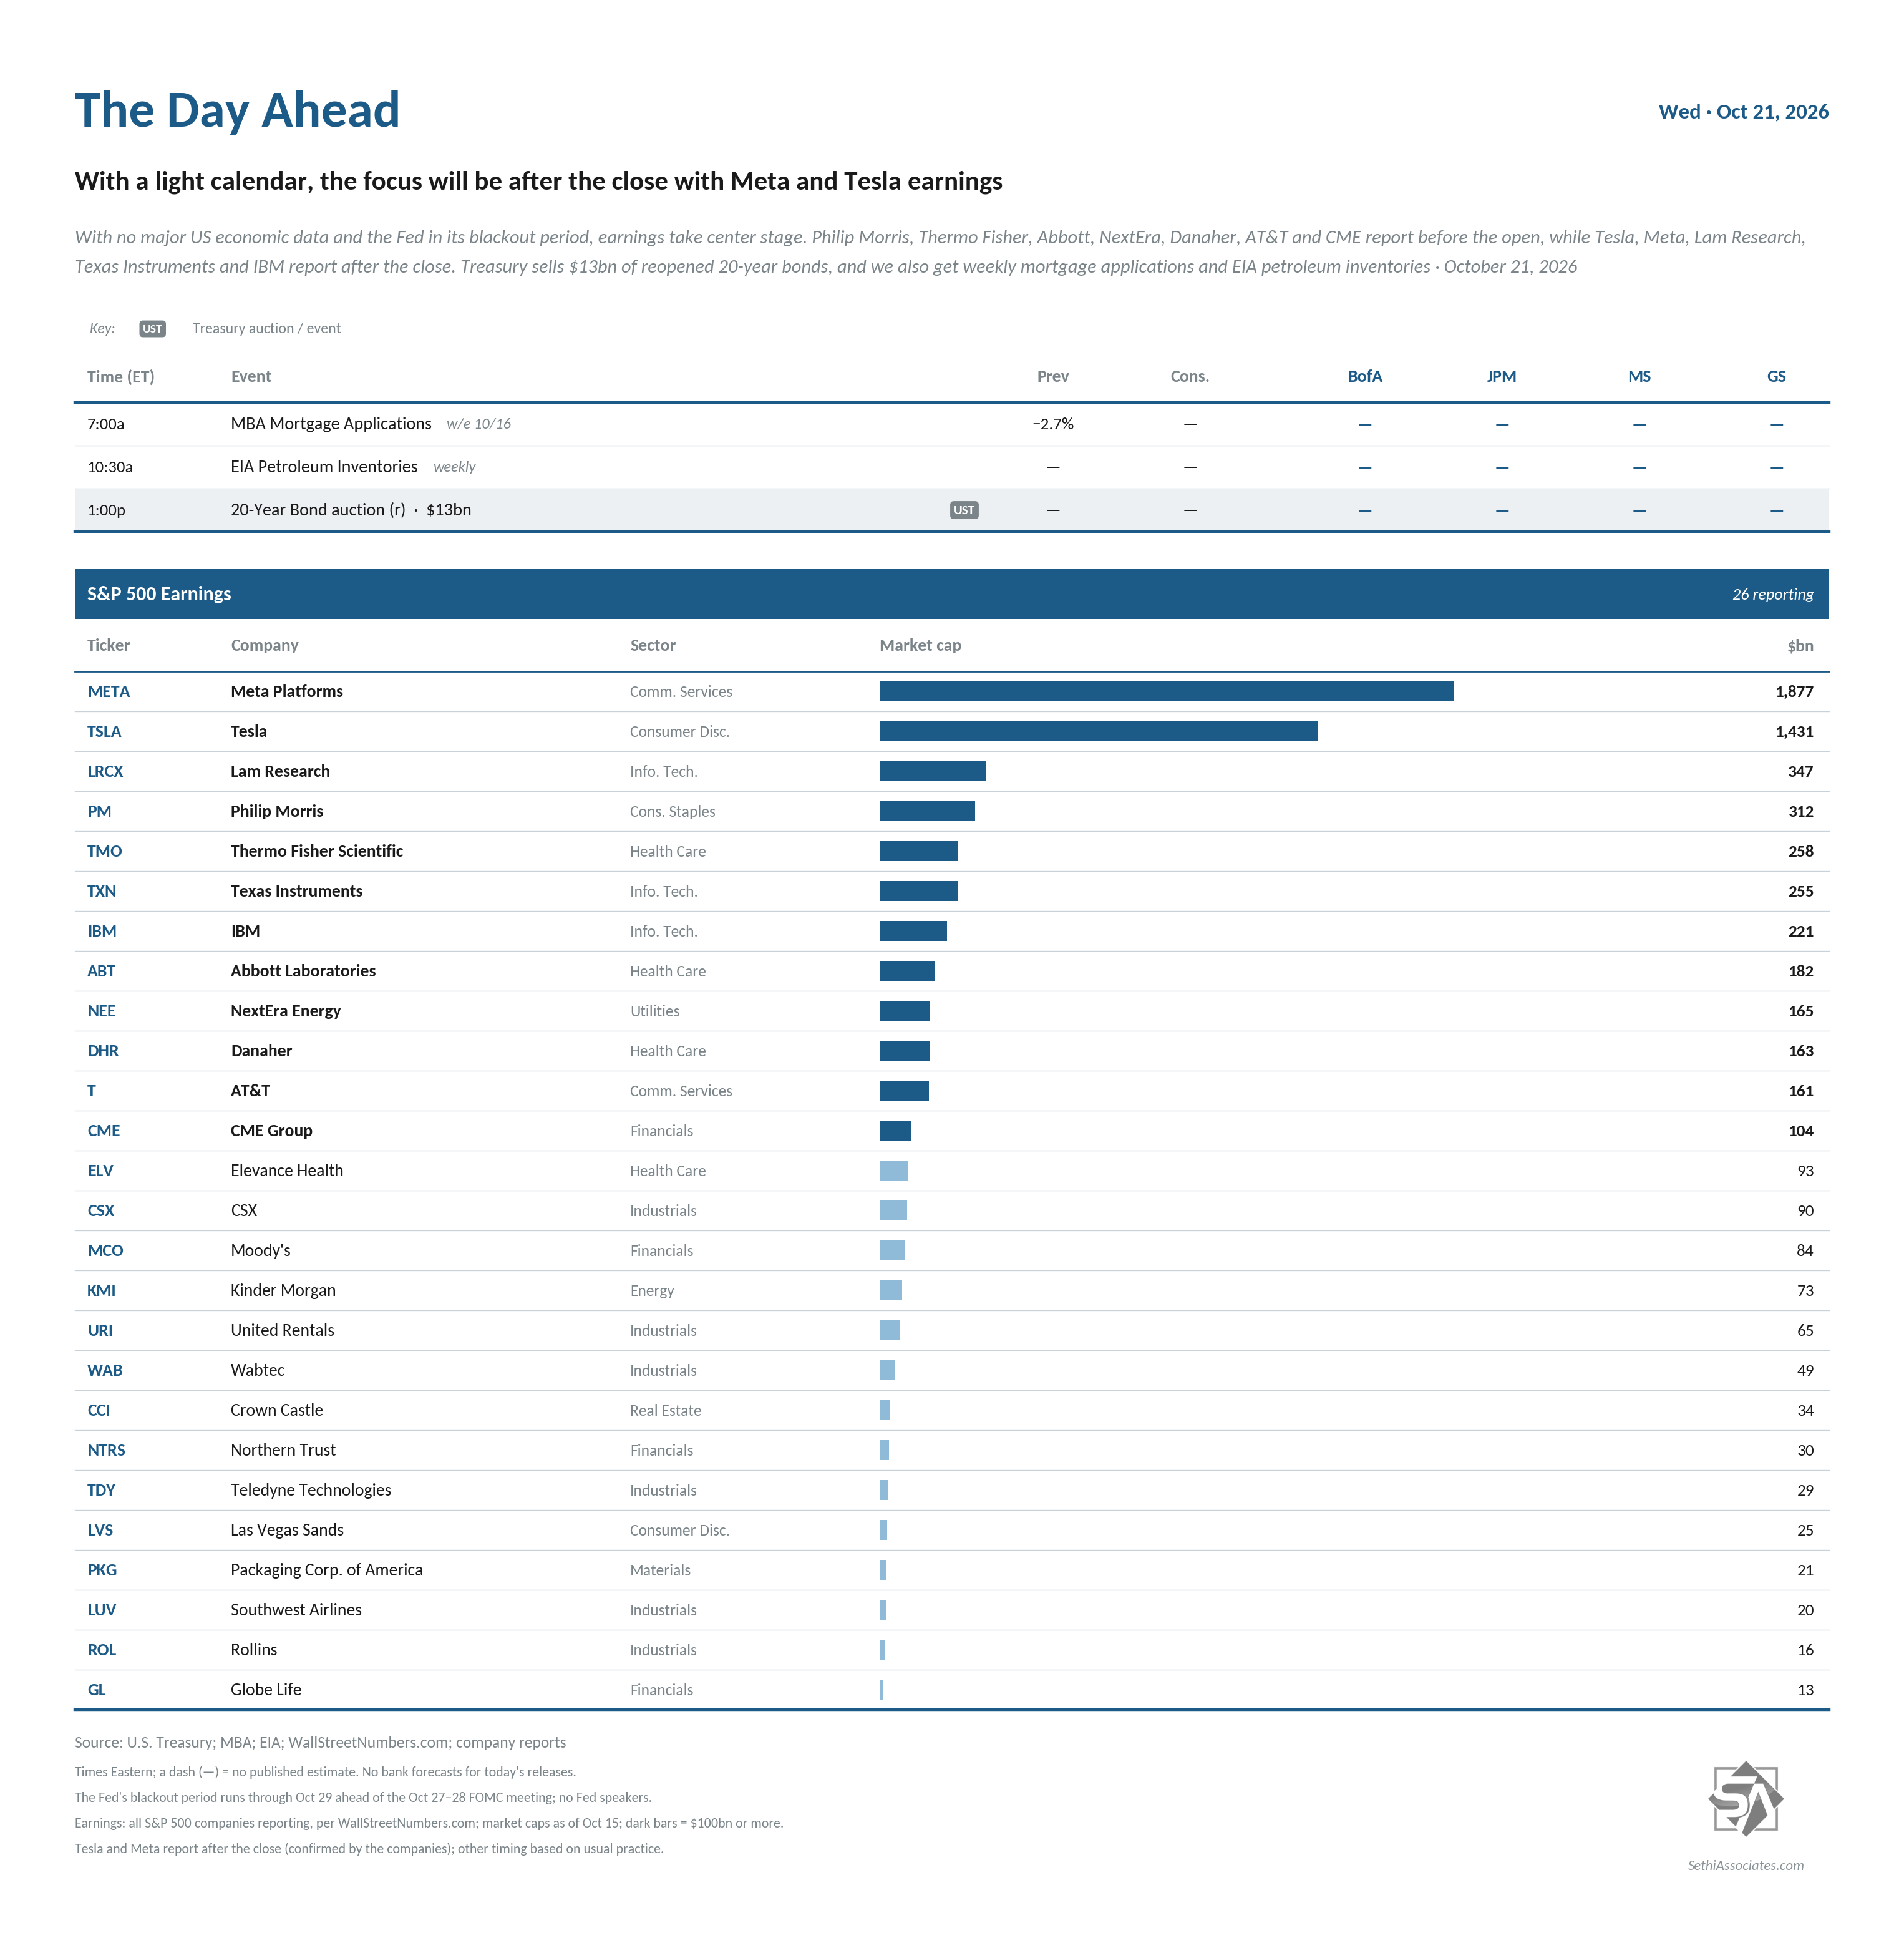
US economic data is light Wednesday, with only weekly mortgage applications and EIA petroleum inventories.

The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.

Non-Bill (>1yr in maturity) US Treasury auctions resume with a $13B 20-year bond reopening.

Q3 earnings season continues with 26 S&P 500 components including a number of AI-related names: Meta Platforms ($META), Tesla ($TSLA), Lam Research ($LRCX), Philip Morris ($PM), Thermo Fisher Scientific ($TMO), Texas Instruments ($TXN), IBM ($IBM), Abbott Laboratories ($ABT), NextEra Energy ($NEE), Danaher ($DHR), AT&T ($T), CME Group ($CME), Elevance Health ($ELV), CSX ($CSX), Moody’s ($MCO), Kinder Morgan ($KMI), United Rentals ($URI), Wabtec ($WAB), Crown Castle ($CCI), Northern Trust ($NTRS), Teledyne Technologies ($TDY), Las Vegas Sands ($LVS), Packaging Corp. of America ($PKG), Southwest Airlines ($LUV), Rollins ($ROL) and Globe Life ($GL).

Ex-US highlights are UK September CPI, PPI, RPI, public finances, August house price index, Japan September trade balance, New Zealand Q3 CPI.

Upside, Downside Movers in the Morning

Upside

– $VEEA +45.0% (regained full Nasdaq listing compliance following its reverse stock split)

– $XRTX +21.0% (outlined planned FDA IND and Health Canada clinical-trial filings for XRx-026 in gout)

– $SAIQ +19.5% (confirmed an October satellite launch advancing its post-quantum secure-communications roadmap)

– $HUM +14.5% (2027 CMS Star Ratings exceeded its top-quartile revenue goal, with its largest contract returning above the bonus-payment threshold)

– $CLOV +11.5% (PPO plans earned 5 stars and the HMO plan earned 4.5 stars for 2027, strengthening 2028 payment and enrollment economics)

– $CCI +9.5%, SBAC +7.0%, AMT +7.0% (tower operators rally as SPCX’s low-band spectrum deal implies a terrestrial buildout and potential new-tenant demand)

– $FSLY +7.0% (Oppenheimer upgrades to Outperform with a $35 target on AI-traffic growth)

– $AAOI +6.0%, LITE +6.0%, COHR +4.5%, GLW +3.5% (optical names rise after LITE said AI-data-center demand has booked component capacity through early 2029)

– $ECHO +5.0% (SPCX’s additional spectrum purchase reinforces the value of ECHO’s existing spectrum and equity partnership)

– $SPCX +4.0% (agrees to acquire a nationwide 800 MHz spectrum portfolio for about $8B, strengthening its direct-to-device mobile push)

Downside

– $ALHC -23.0% (key California HMO contract fell to 3.5 stars, below the CMS quality-bonus threshold)

– $TMUS -7.5%, T -6.5%, VZ -6.0% (wireless carriers slide as SPCX’s nationwide low-band spectrum acquisition raises the threat of direct mobile competition)

– ASTS -3.0% (falls after SPCX acquired spectrum ASTS had pursued, increasing competitive and spectrum-access concerns)

– $CVS -3.0% (only about 69% of Medicare Advantage members are in 4-star-plus plans for 2027, down from 81% for 2026)

– $AAPL -2.5% (no clear fresh catalyst identified; unusually large mega-cap decline despite higher Nasdaq futures)

– $DAL -1.5%, LUV -2.0%, $UAL -1.5% ($DAL missed Q3 profit expectations and sharply cut its FY outlook as surging fuel costs overwhelmed strong demand)