Deckers Down, Nokia Up: Upside, Downside Movers in the Morning

Upside

– $CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)

– $NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)

– $LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)

– $BAH +1.9% (Q2 profit beat offset a slight revenue miss)

– $TECK +1.7% (copper-linked stocks rise as copper prices advance)

Downside

– $FLG -8.3% (Q3 profit and revenue missed expectations)

– $DECK -8.2% (quarterly sales missed and the FY sales outlook was cut, while the higher EPS guide relied partly on tariff refunds)

– $INFY -8.2% (FY revenue-growth guidance was cut to 1%-2% despite strong large-deal wins)

– $ALV -5.2% (Q3 profit and sales missed as cost headwinds weighed on results)

– $CRDO -4.6% (AI-infrastructure hardware weakness continues amid concerns over the pace and returns of sector spending)

– $TMUS -4.5%, T -4.4%, VZ -3.9% (wireless carriers fall after a report that SpaceX is pursuing a nationwide cellular-infrastructure program)

– $BE -3.9% (record results and raised guidance were not enough after a major AI-power rally)

– $MRNA -3.7% (extends losses following leaked cancer-vaccine data that disappointed investors)

– $FIX -3.1% (earnings beat, but the CFO retirement and elevated expectations drive a sell-the-news reaction)

– $ACN -2.7%, $CTSH -2.0% (IT-services names fall after Infosys cut its FY growth outlook)

– $WDC -1.9%, STX -1.4% (storage names retreat despite WDC’s beat-and-raise report as elevated expectations trigger profit-taking)

A Look at Thursday

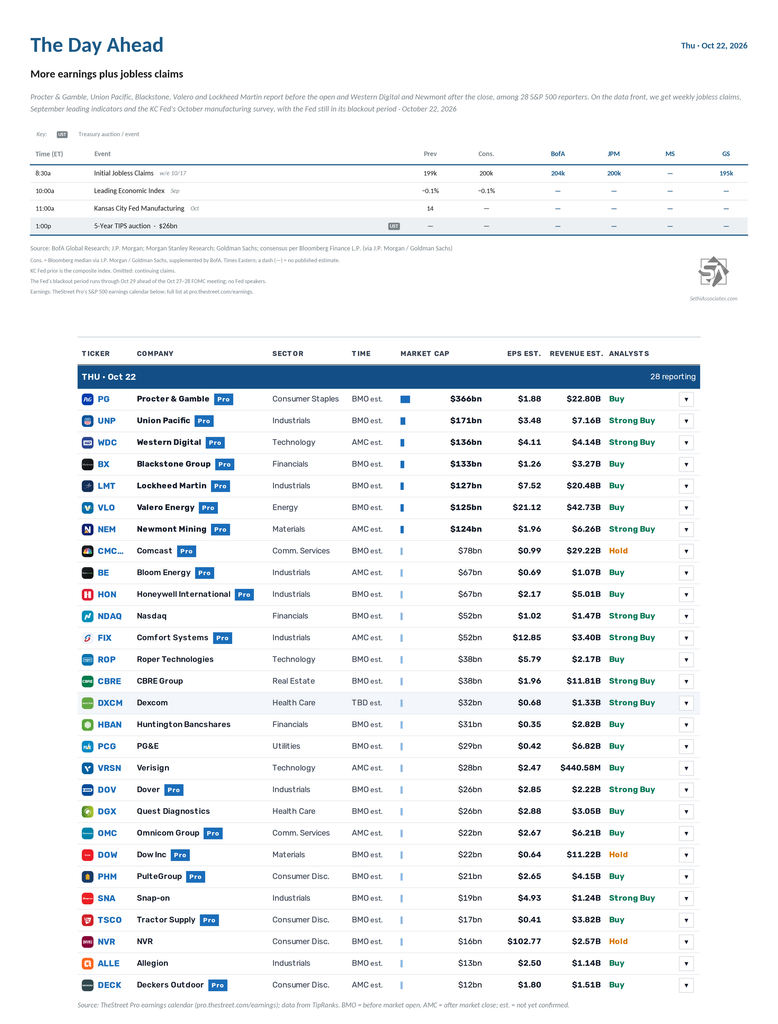
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.

The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.

Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.

Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble ($PG), Union Pacific ($UNP), Western Digital ($WDC), Blackstone ($BX), Valero Energy ($VLO), Lockheed Martin ($LMT), Newmont ($NEM), Comcast ($CMCSA), Norfolk Southern ($NSC), Bloom Energy ($BE), Honeywell ($HON), Nasdaq ($NDAQ), Comfort Systems USA ($FIX), CBRE Group ($CBRE), PG&E ($PCG), Roper Technologies ($ROP), Huntington Bancshares ($HBAN), VeriSign ($VRSN), Quest Diagnostics ($DGX), Dover ($DOV), PulteGroup ($PHM), Dow ($DOW), Snap-on ($SNA), Tractor Supply ($TSCO), NVR ($NVR), Allegion ($ALLE) and Deckers Outdoor ($DECK).

Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.

Select Upside, Downside Movers in the Morning

Upside

– $IRON +52% (Phase 3 APOLLO trial met all primary and secondary endpoints in erythropoietic protoporphyria)

– $AAME +41% (long-delayed 2025 annual report was filed, showing a return to annual profitability)

– $XLAB +24% (extends rally after securing an $8.2M AI-server order)

– $TCRT +20% (extends volatile rally tied to a proposed acquisition and financing of up to $350M)

– $MEDS +15% (extends rally after outlining peptide-compounding expansion and licensing a direct-to-consumer GLP-1 platform)

– $CLF +11% (Q3 profit and EBITDA beat expectations, Q4 EBITDA was guided higher and 2027 EBITDA is expected to exceed $4B)

– $NBIS +7.5%, $CRWV +7.7%, $BE +5.2%, $SMCI +4.1%, $IREN +5.9% (AI-infrastructure names rebound from last week’s financing-driven selloff as Treasury yields ease)

– $CRDO +4.7%, $TER +5.1%, $LRCX +4.6%, $AMD +3.7%, $MU +3.7%, $AVGO +3.1% (chip names rebound from last week’s AI-led selloff ahead of key sector earnings)

– $INTC +4.3% (JPMorgan upgrades to Neutral from Underweight as confidence in the turnaround improves)

– $VAI +4.0% (agrees to acquire an 18MW Ohio computing center)

– $DDOG +3.9% (Bernstein upgrades to Outperform and sharply raises its price target on stronger AI-consumption trends)

Downside

– $ACTU -9.1% (files to sell 40M shares with 20M warrants)

Upside, Downside Movers in the Morning

Upside

– $LPCN +40% (Health Canada approves TLANDO for testosterone replacement therapy)

– $APUS +9.4% (extends a high-volume rally tied to the BlockAssure agreement to build and operate the AssureChain insurance network)

– $PENG +4.3% (Q4 beat and FY27 sales and EPS outlook topped prior guidance and Street expectations on accelerating AI-infrastructure demand)

– CNQ +1.6%, APA +1.2%, OXY +1.0%, COP +1.0% (oil producers rise as crude climbs back above $100 a barrel)

Downside

– $CRBU -42% (launches a strategic-alternatives review, discontinues two allogeneic CAR-T programs and plans substantial workforce reductions)

– $BULL -30% (bipartisan House panel report says structural China ties pose national-security and US-user-data risks)

– $STM -5.4%, $TER -3.0%, $ASML -3.0%, $AMAT -2.7%, $LRCX -3.0%, $MU -2.8% (chip stocks fall in the risk-off technology tape as oil-driven inflation concerns pressure rate-sensitive growth shares)

– $BMNR -5.0%, $CRCL -4.0%, $MSTR -3.8%, $COIN -3.1%, $HOOD -3.0% (crypto-linked stocks fall as digital-asset prices weaken)

– $AAOI -4.8%, $CIEN -3.8%, $MTSI -3.0%, $COHR -3.2%, $GLW -3.3% (AI-networking and optical winners pull back after sharp recent rallies as technology exposure is reduced)

– $DB -4.7%, $SAN -4.2%, $HSBC -3.9%, $NWG -3.5%, $BCS -3.3% (European-bank ADRs fall as oil-driven inflation and sovereign-bond stress deepen fiscal concerns, with UK lenders also facing budget-tax fears)

– $STZ -3.9% (quarter beat, but adjusted FY guidance was merely reiterated and beer depletions declined)

– $BE -3.8%, $CEG -3.5%, $EME -1.9% (AI-power and data-center infrastructure winners give back part of recent gains amid the broader risk-off rotation)