AI Rout Sends the Tech Sector to Its Worst Day Since the Covid Crash

Worries that Democrat political gains will slow the AI buildout morphed into a broader selloff Thursday pulling every sector lower, led by Tech.
Worries that Democrat political gains will slow the AI buildout morphed into a broader selloff Thursday pulling every sector lower, led by Tech.
This time, investors didn’t rotate, they ran for the safety of cash.
– $SEZL +30% (Q3 revenue and transaction volume surged, FY guidance was raised for the fourth time and preliminary 2027 EPS guidance was introduced)
– $ARQ +26% (record Q3 revenue, sharp margin expansion and the low end of FY EBITDA guidance was raised)
– $APP +22% (Q3 profit beat and revenue came in $100 million above the top of the company’s forecast)
– $RUN +21% (Q3 beat as direct installations returned to growth and storage attachment reached a record)
– $WRBY +21% (raised the low end of FY sales guidance and confirmed November 12 preorders for its first Intelligent Eyewear collection)
– $ADMA +20% (ASCENIV sales rose 31%, gross margin expanded sharply and the adjusted earnings outlook was raised)
– $U +20% (strongest quarter on record, with Vector revenue up 126% and the first GAAP profit since its IPO)
– $TPR +14% (Q1 beat with strong Coach growth and FY revenue, margin and EPS guidance raised)
– $EPAM +12% (Q3 beat alongside a $1.5 billion buyback expansion and planned $500 million accelerated repurchase)
– $TM +8.8% (first-half profit strengthened and the full-year operating-income and net-income forecasts were raised)
– $SONY +6.0% (Q2 profit surged on gaming and film strength, prompting higher full-year sales, profit and dividend forecasts)
– $BABA +5.3%, $TCOM +4.3%, $NTES +3.9%, $PDD +3.7%, $JD +4.2% (China ADRs rise with an overnight rebound in Hong Kong technology shares)
– $GFI +4.4% (gold producer gains as bullion prices rally)
– $CELH +2.7% (record Q3 revenue rose 17% as the expanded beverage portfolio sustained growth)
– $UBER +2.4% (Amazon Prime members can now order Uber Eats with free delivery on qualifying purchases)
– $MNTN -46% (slashed FY revenue and EBITDA guidance after sales-team execution problems and named a new CEO)
– $BZFD -34% (Q3 revenue plunged 44%, adjusted EBITDA turned negative and the FY outlook was deferred)
– $VCYT -32% (lowered near-term Decipher Prostate expectations, narrowed FY guidance below consensus and forecast only mid-single-digit 2027 revenue growth)
– $ANVS -29% (proposed a dilutive stock-and-warrant offering while disclosing limited cash, going-concern risk and expanded authorized shares)
– $AKBA -25% (Q3 revenue fell sharply as Auryxia sales were hit by generic competition and pricing pressure)
– $HIMX -25% (guided Q4 revenue down 22% to 26% sequentially on abrupt automotive-display order corrections)
– $GIL -23% (Q3 missed expectations, FY sales and EPS guidance was cut sharply and 2026–2028 objectives were withdrawn)
– $WMS -13% (organic stormwater sales declined, demand softened and the FY revenue outlook was reduced)
– $QCOM -11% (smartphone-chip sales missed expectations on sluggish demand and declining Apple-related revenue)
– $FICO -10% (withheld FY27 guidance amid mortgage-pricing uncertainty and was downgraded by RBC despite a quarterly beat)
– $SNAP -10% (Q3 revenue missed expectations)
– $MELI -9.2% (earnings missed and logistics investment compressed operating margin despite strong revenue growth)
– $AMCR -8.1% (profit missed and the six-month EPS outlook was cut as energy and distribution costs outpaced pricing recovery)
– $ASX -7.6%, $SNDK -5.8%, $SKHY -6.2%, $STX -4.5% (Asian and memory-chip names extend the semiconductor selloff as election results intensify concerns over slower data-center construction)
– $ARM -7.4% (quarter beat, but current-quarter guidance failed to clear elevated expectations and shares joined the broader chip selloff)
– $HUBS -6.5% (Q3 beat, but Q4 profit guidance came in below expectations)
– $BDX -5.4% (Q4 beat, but low-single-digit FY27 revenue growth and modest EPS growth guidance disappointed)
Let’s see how and why the midterms gave a boost to Wall Street, and examine why even some tech giants surged — while others dropped.
A Democratic sweep of Congress supercharged the rotation trade, with hyperscalers joining a rally that lifted almost everything except semiconductors and AI power and data center names.
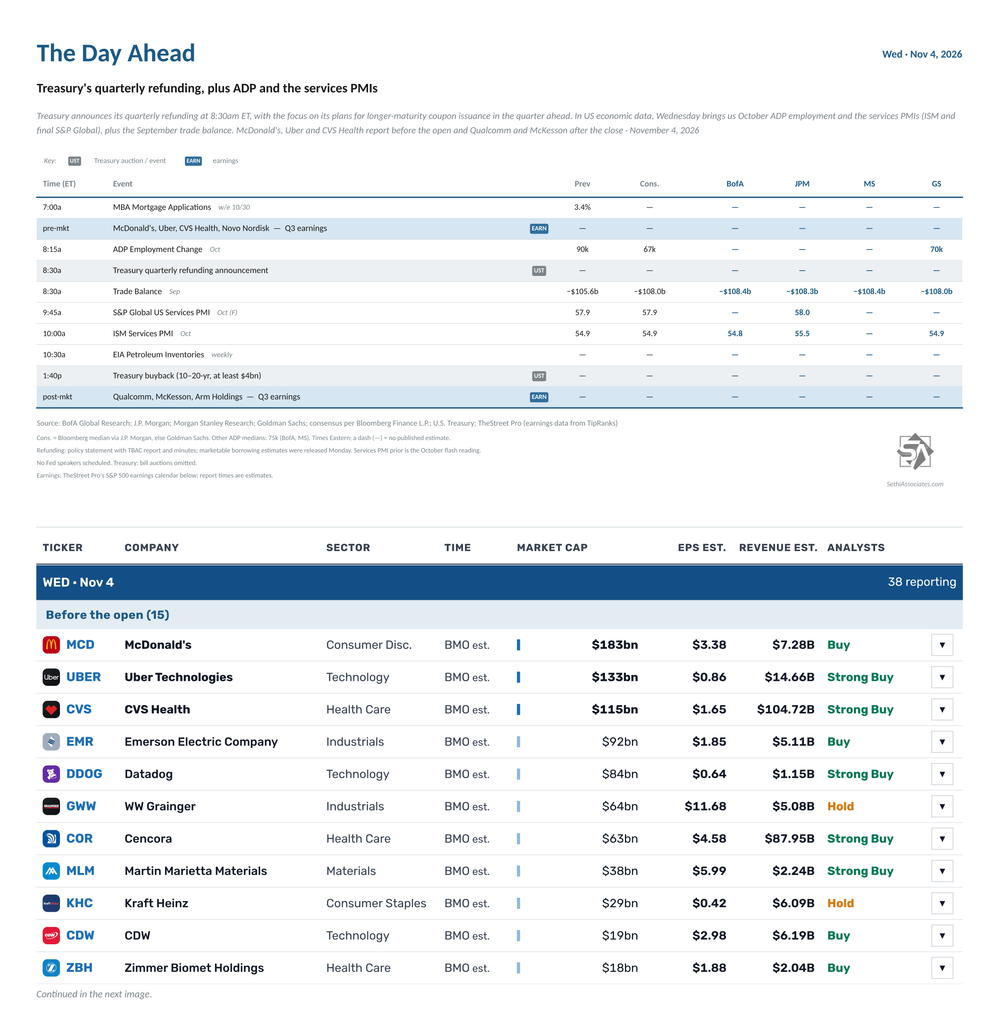
In US economic data, Wednesday brings us October ADP private employment growth and the services PMIs (ISM and final S&P Global), plus the September trade balance. We’ll also get weekly MBA mortgage applications and EIA petroleum inventories.
There are no Fed speakers scheduled.
There are no non-Bill (>1yr in maturity) US Treasury auctions, but Treasury announces its quarterly refunding at 8:30am ET, with the focus on its plans for longer-maturity coupon issuance in the quarter ahead. It also holds a buyback of 10- to 20-year securities in the afternoon.
38 S&P 500 components report, five of them with market caps over $100B:
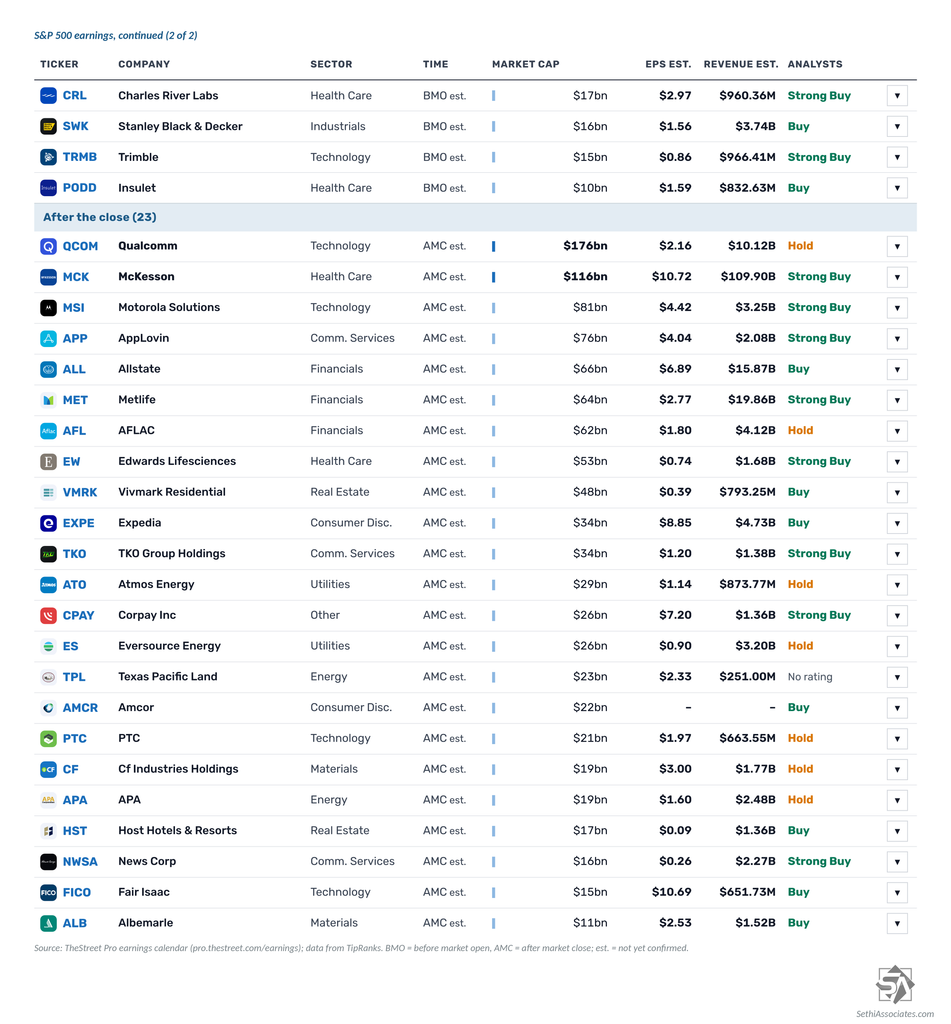
Before the open: McDonald’s ($MCD), Uber ($UBER), CVS Health ($CVS), Emerson Electric ($EMR), Datadog ($DDOG), W.W. Grainger ($GWW), Cencora ($COR), Martin Marietta Materials ($MLM), Kraft Heinz ($KHC), CDW ($CDW), Zimmer Biomet ($ZBH), Charles River Laboratories ($CRL), Stanley Black & Decker ($SWK), Trimble ($TRMB) and Insulet ($PODD)
After the close: Qualcomm ($QCOM), McKesson ($MCK), Motorola Solutions ($MSI), AppLovin ($APP), Allstate ($ALL), MetLife ($MET), Aflac ($AFL), Edwards Lifesciences ($EW), Vivmark Residential ($VMRK), Expedia ($EXPE), TKO Group ($TKO), Atmos Energy ($ATO), Corpay ($CPAY), Eversource Energy ($ES), Texas Pacific Land ($TPL), Amcor ($AMCR), PTC ($PTC), CF Industries ($CF), APA ($APA), Host Hotels & Resorts ($HST), News Corp ($NWSA), Fair Isaac ($FICO) and Albemarle ($ALB)
Outside the S&P 500, Novo Nordisk ($NVO) reports before the open and Arm Holdings ($ARM) and MercadoLibre ($MELI) after the close.
Also, opening arguments are scheduled in a Los Angeles trial over claims that Meta ($META) and Snap ($SNAP) designed their platforms to be addictive and harmful to young users, per Bloomberg.
Ex-US highlights include the final October services PMIs (including China’s RatingDog services PMI), Eurozone October CPI, Spain’s October unemployment rate, UK October official reserves changes and Canada’s September trade balance. There are rate decisions from Sweden’s Riksbank, Poland and Brazil, the ECB releases its wage tracker, ECB Chief Economist Lane and Bank of France Governor Moulin speak, and the Bank of Japan releases the minutes of its September meeting.
Semiconductors led a rebound that broke the S&P 500’s three-day losing streak, but the average stock fell.
Source: TradeTheNews
– $VTGN +59.5% (extends the prior-session rally after preliminary PALISADE-4 open-label extension data for fasedienol in social anxiety disorder)
– $GRML +24.0% (no clear fresh catalyst identified; exceptionally heavy-volume small-cap move)
– $WOR +15.5% (Q1 beat as stronger Building Products results and data-center demand lifted performance)
– $TLSI +15.0% (FDA grants 510(k) clearance for the TriNav Advance drug-delivery device)
– $IONQ +13.0% (demonstrates an end-to-end real-time quantum error-correction decoder running on a standard CPU)
– $CBRL +9.0% (Q4 profit beat and FY27 EBITDA outlook pointed to a sharp recovery despite lower sales)
– $QUBT +4.0% (quantum-computing sympathy following IONQ’s error-correction milestone)
– $CART +3.0% (expands its AI-shopping partnership network)
– $APH +3.0% (Bernstein initiates coverage at Outperform)
– $JAGX -48.0% (reverses sharply after the prior session’s roughly twelvefold FDA-fee-waiver-driven surge)
– $INNV -8.5% (10M-share secondary offering by selling stockholders creates a near-term stock overhang)
– $VOYG -7.5% ($350M convertible-senior-notes offering raises dilution concerns)
– $ASTH -7.5% (no clear fresh catalyst identified; renewed selling follows the recent short report questioning accounting estimates)
– $BMEA -7.0% (launches an underwritten common-stock and pre-funded-warrant offering)
– $AU -4.5%, GFI -4.5%, AG -3.0%, NEM -2.0% (precious-metals miners fall as gold and silver prices retreat)
– $BABA -3.0% (China ADR weakness ahead of the U.S.-China summit as mainland equities decline)
– $APP -2.5% (extends the AI-disruption selloff on concern consumer agents could pressure ad-tech economics)
These small-cap biotechs offer core businesses that fund a much bigger opportunity.