New Microsoft Price Target as $33 Billion Cloud Update Turns Heads


Waiting for answers on 2027 free cash flow and capex questions could keep the shares capped near term.
Waiting for answers on 2027 free cash flow and capex questions could keep the shares capped near term.
Mag 7 names are being sold — and that is good news for the rest of the market.
After last night’s earnings and cloud details, we must ask if GOOGL shares will be higher one year from now or not….
Marvell’s potential Lumentum bid, Samsung’s comments on chip capacity, and other headlines are moving the market this morning.
Microsoft is rewarded for trimming its spending plans. Alphabet is hit on profitability, and it may be its worst earnings reaction ever.
* Bona fide business threats had emerged but were ignored as passive and relentless buying of Google’s shares masked a growing AI headwind
* Is Amazon as vulnerable as Google?
Google ($GOOGL) is not only an example that the threat to its search business is real…
Price Is Not Truth
… But it is also testimony to the threat represented by market structure.
What do I mean by that? Let me explain…
Well, passive price momentum-based products and strategies carried Google’s shares ever higher in recent months — and the blind monkeys in the business media (without any or with limited analytical rigor), confidently took the price increases as a sign of fundamental progress. Indeed Google became the darling of the hyperscalers based principally on chart gazing.
Here is perennial bull Gene Munster voicing his concerns:
This gets me back to Amazon ($AMZN).
What has kept me from buying AMZN at seemingly an attractive price-earnings multiple is what has threatened Google. Is the utility of using Amazon markedly reduced as AI/Personal Bots expand their tasks?
Again from Gene Munster:
Finally, about two years ago we observed the dramatic change in the hyperscaler from capital light to capital intensive — suggesting that this was not market friendly and that it was price-earnings multiple altering/contracting:
Position: None
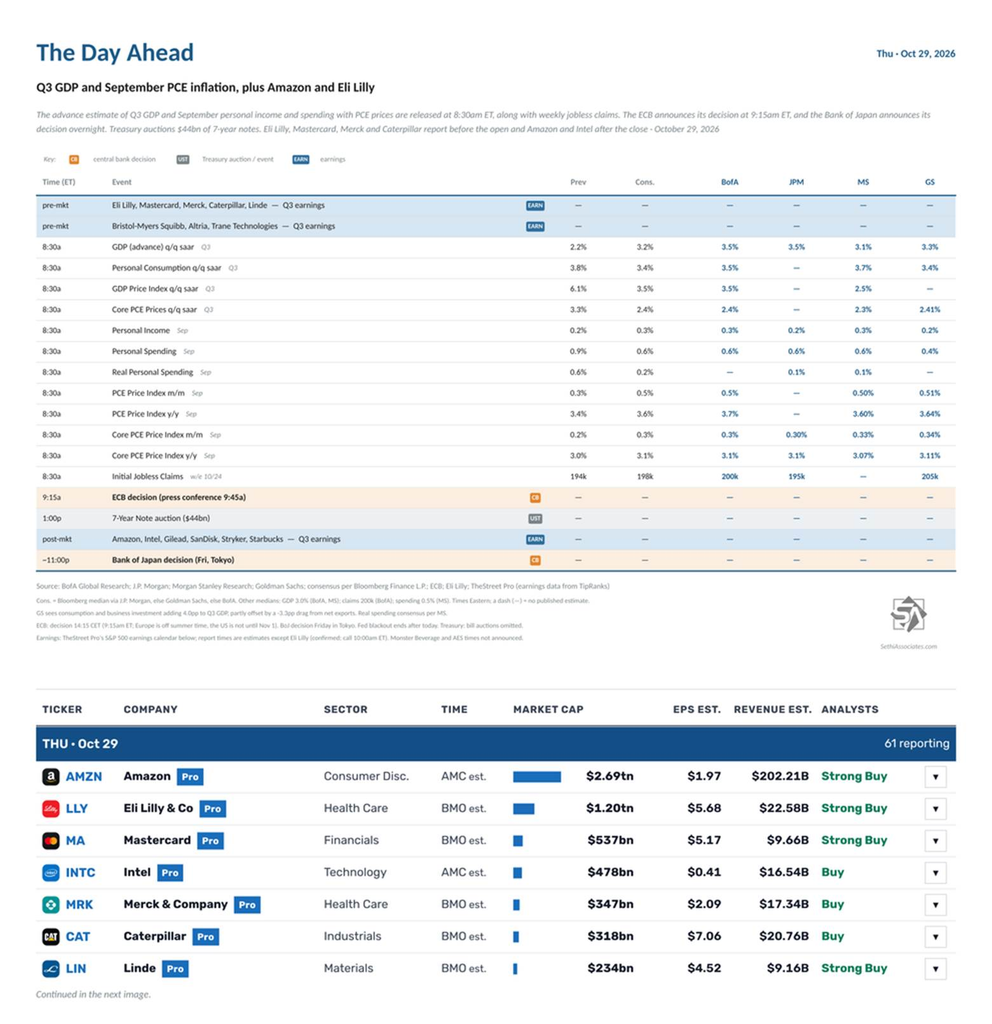
US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.
The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.
The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.
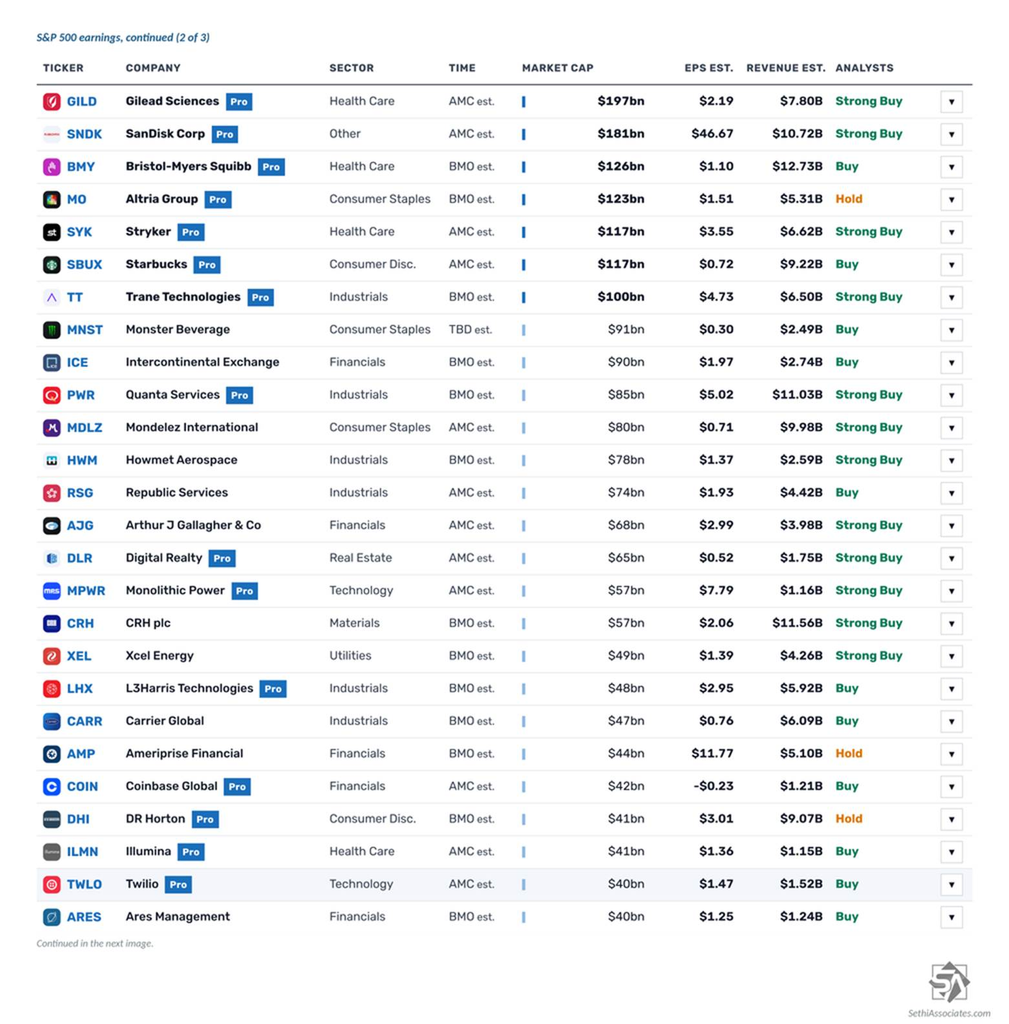
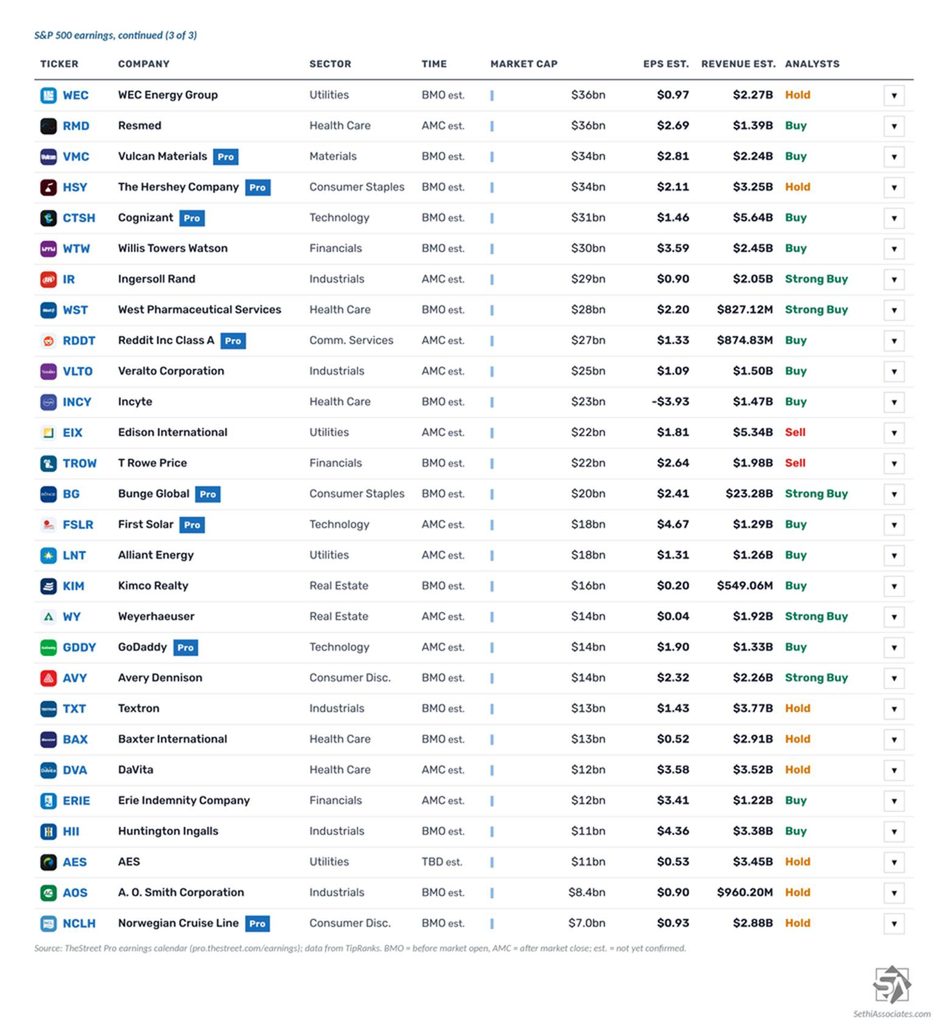
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:
Before the open: Eli Lilly ($LLY), Mastercard ($MA), Merck ($MRK), Caterpillar ($CAT), Linde ($LIN), Bristol Myers Squibb ($BMY), Altria ($MO), Trane Technologies ($TT), Intercontinental Exchange ($ICE), Quanta Services ($PWR), Howmet Aerospace ($HWM), CRH ($CRH), Xcel Energy ($XEL), L3Harris ($LHX), Carrier ($CARR), Ameriprise ($AMP), D.R. Horton ($DHI), Ares Management ($ARES), WEC Energy ($WEC), Vulcan Materials ($VMC), Hershey ($HSY), Cognizant ($CTSH), WTW ($WTW), West Pharmaceutical ($WST), Incyte ($INCY), T. Rowe Price ($TROW), Bunge ($BG), Kimco Realty ($KIM), Avery Dennison ($AVY), Textron ($TXT), Baxter ($BAX), Huntington Ingalls ($HII), A.O. Smith ($AOS) and Norwegian Cruise Line ($NCLH)
After the close: Amazon ($AMZN), Intel ($INTC), Gilead ($GILD), SanDisk ($SNDK), Stryker ($SYK), Starbucks ($SBUX), Mondelez ($MDLZ), Republic Services ($RSG), Arthur J. Gallagher ($AJG), Digital Realty ($DLR), Monolithic Power ($MPWR), Coinbase ($COIN), Illumina ($ILMN), Twilio ($TWLO), ResMed ($RMD), Ingersoll Rand ($IR), Reddit ($RDDT), Veralto ($VLTO), Edison International ($EIX), First Solar ($FSLR), Alliant Energy ($LNT), Weyerhaeuser ($WY), GoDaddy ($GDDY), DaVita ($DVA) and Erie Indemnity ($ERIE)
Time not announced: Monster Beverage ($MNST) and AES ($AES)
Outside the US, Shell ($SHEL), TotalEnergies ($TTE) and Volkswagen ($VWAGY) report.
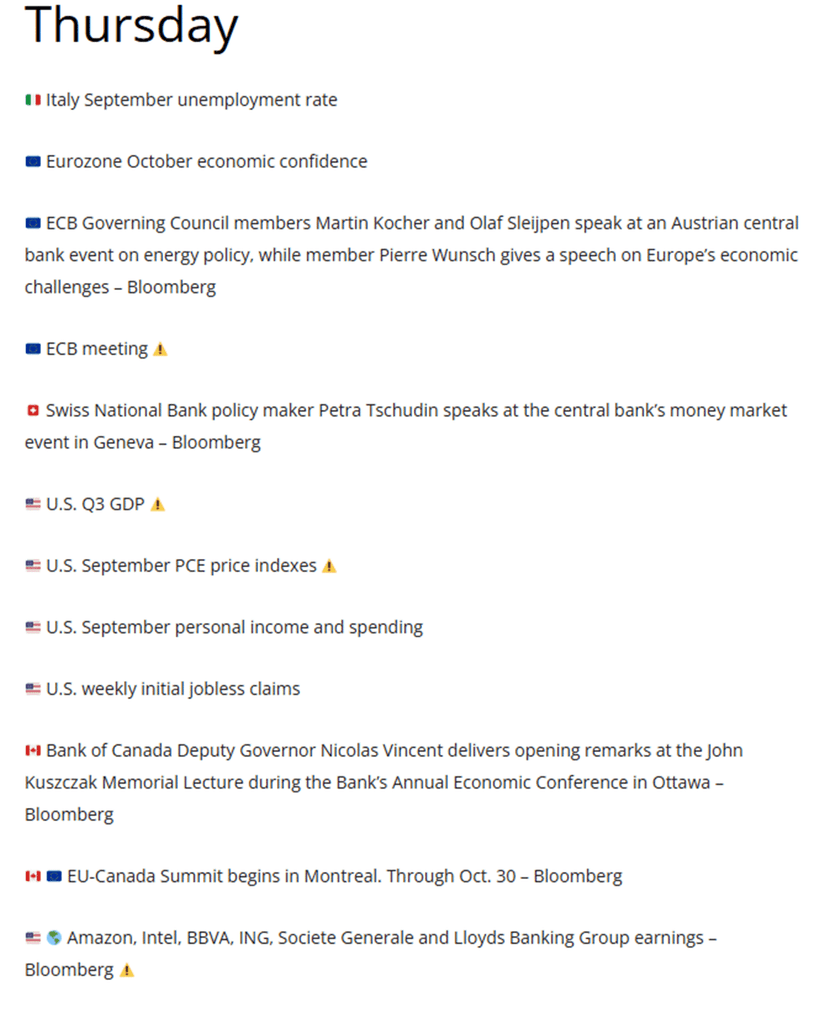
Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.
From Christophe Barraud’s international Week Ahead rundown:
The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
* Here are my thoughts following the plethora of EPS releases after the close…
With Google’s ($GOOGL) miss (the deceleration in its core business was unanticipated by every panelist on “the show”), Meta’s ($META) continued awful share price action, Nvidia’s ($NVDA) price rollover threatening chart support, Amazon’s ($AMZN) lackluster share price action (and underperformance) and some possible toppiness in Apple’s ($AAPL) share price, we are left with one… Microsoft ($MSFT).
Meanwhile, ServiceNow’s ($NOW) disappointing results (the company cut subscription revenues for the full year) will likely weigh heavily on software stocks (which were market leaders) tomorrow morning.
I remain independent in view.
As I said in response to subscriber jryan, most stocks do not meet my standards to buy and I won’t change my process or discipline — even if Perma Bulls Tom Lee and Dan Ives (confidently) see clear skies ahead…
The S&P Short Range Oscillator registered 1.84% (more overbought than the prior day) and I ended the day with a large short positioin in $SPY.
Position: Short SPY (L)
Oracle reassurance moved the market more than the Fed did.