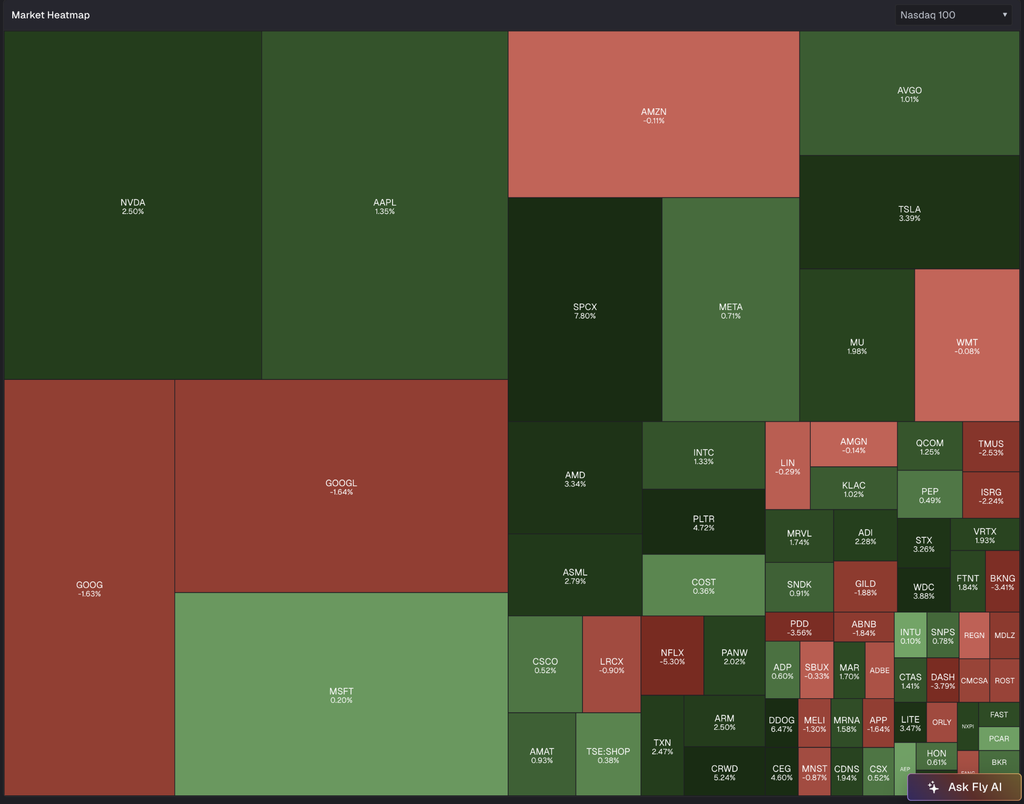
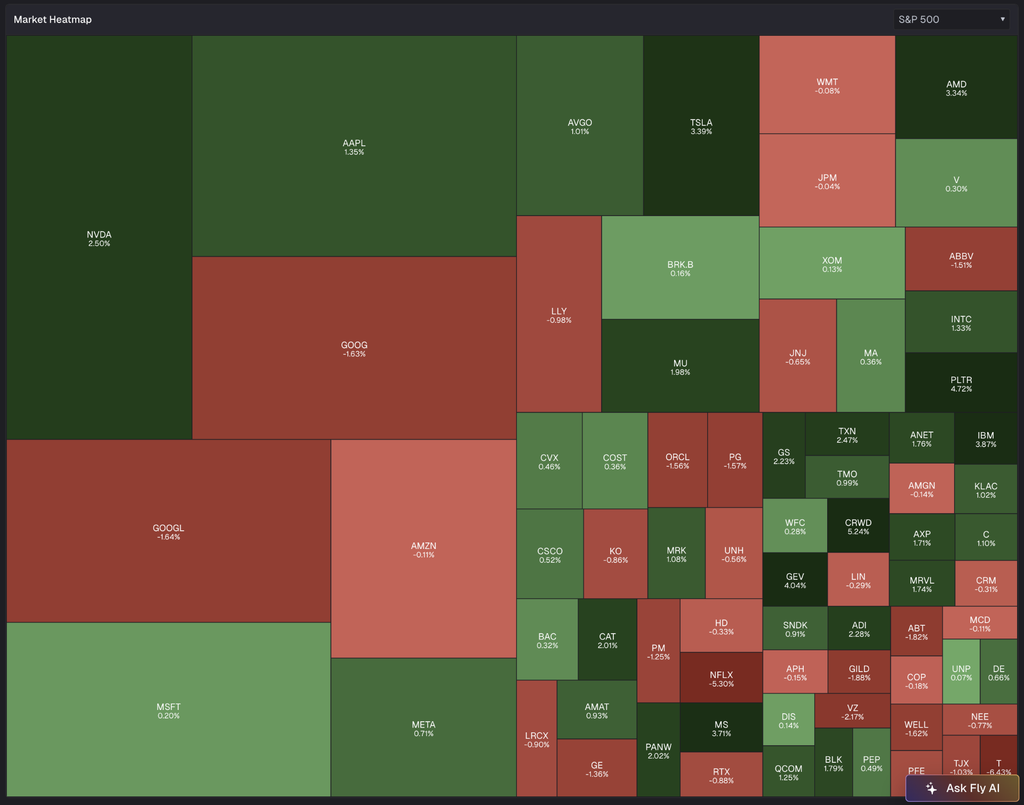
A Look at Thursday

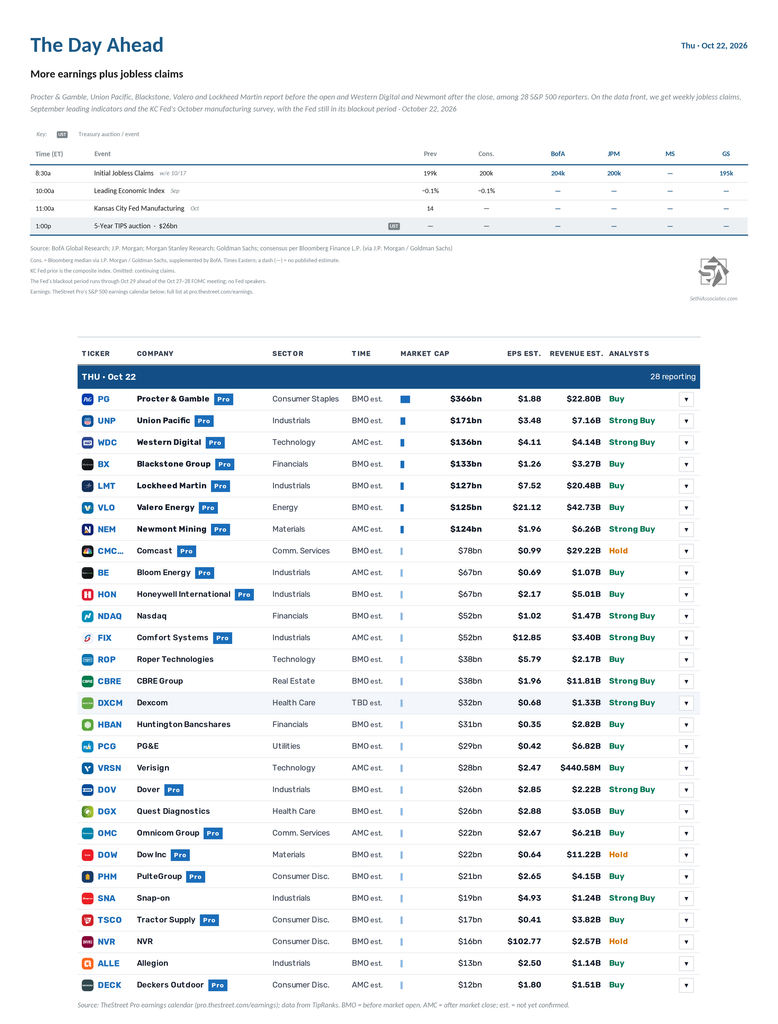
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.
Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble ($PG), Union Pacific ($UNP), Western Digital ($WDC), Blackstone ($BX), Valero Energy ($VLO), Lockheed Martin ($LMT), Newmont ($NEM), Comcast ($CMCSA), Norfolk Southern ($NSC), Bloom Energy ($BE), Honeywell ($HON), Nasdaq ($NDAQ), Comfort Systems USA ($FIX), CBRE Group ($CBRE), PG&E ($PCG), Roper Technologies ($ROP), Huntington Bancshares ($HBAN), VeriSign ($VRSN), Quest Diagnostics ($DGX), Dover ($DOV), PulteGroup ($PHM), Dow ($DOW), Snap-on ($SNA), Tractor Supply ($TSCO), NVR ($NVR), Allegion ($ALLE) and Deckers Outdoor ($DECK).
Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.