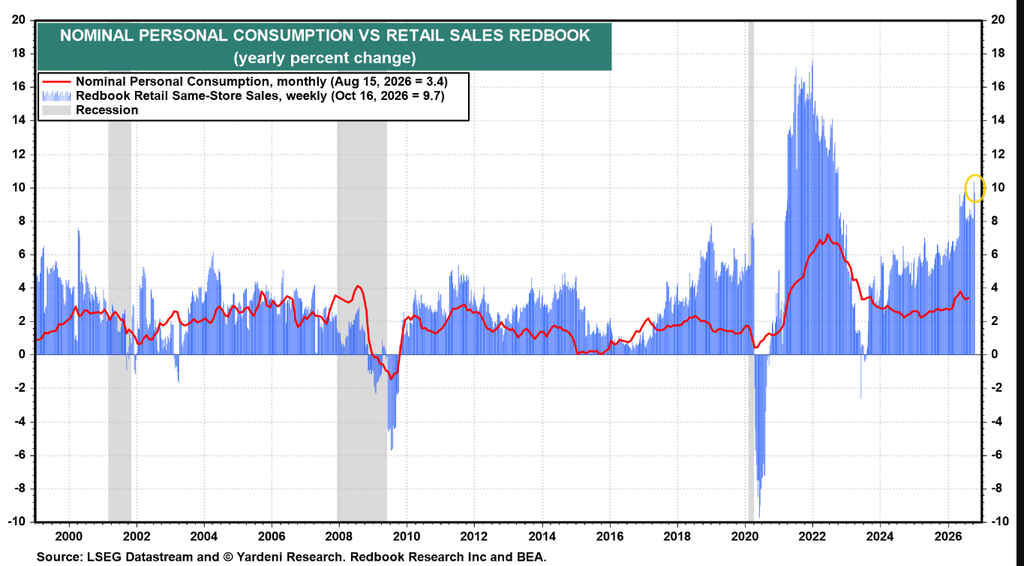
Redbook sales*in the week of October 16th decelerated but remained very healthy at +9.7% y/y growth, after hitting +10.4% the prior week, which was the best since 2022, well above the 2025 average of +5.8% y/y.
*Redbook sales are same-store sales across a panel of large general-merchandise retailers, such as department stores, discount chains, apparel retailers, drugstores, and warehouse clubs.
Chief Administrative Law Judge Derek Julius’ cannabis decision was a singular victory for the industry (and rescheduling).
Here are some examples of responses from some learned cannabis observers:
$MSOS What is not being talked about enough is the following reply from ALJ Derek Julius after his receipt from the DEA and now directly to the opponents!
TICK TOCK! – they have essentially until the end of today October 21st to respond!
$MSOS Based on this, the 7-to-14 day delay threat Is dead, all filings are in the judge's hands, and the order closing the record is imminent IMHO pic.twitter.com/YJHv9PGmSL
"The judge limited the response to five pages and required it to be submitted that same day… Julius said he was allowing the additional filing “in the interest of fairness and due process,” but emphasized that the timeframe would be expedited “to avoid further delay.”" https://t.co/hkPTuxKSwK
BofA says their clients sold US equities last week (-$9.1B), led by institutions in their 10th-biggest selling week in BofA’s data since 2008.
October is typically institutions’ heaviest selling month as mutual funds harvest tax losses ahead of their 10/31 fiscal year-ends, and BofA says institutional single-stock sales this month, relative to market cap, are already the largest of any October in its data, with two weeks still to go.
Retail sold after two weeks of buying, and hedge funds for the first time in five weeks.
The S&P Short Range Oscillator shifted back into an overbought state at 1.56% vs. -0.09%.
Note that with S&P futures -84 handles (6:01 AM) I have covered my medium-sized $SPY short at $764.96 for a quick and sizeable profit from yesterday afternoon and last night.
I plan to reshort on any rally.
From last night:
Double Down
I double downed on my SPY short at $772.97 after the close and upon closer analysis of the Tesla (TSLA) and Meta (META) releases.
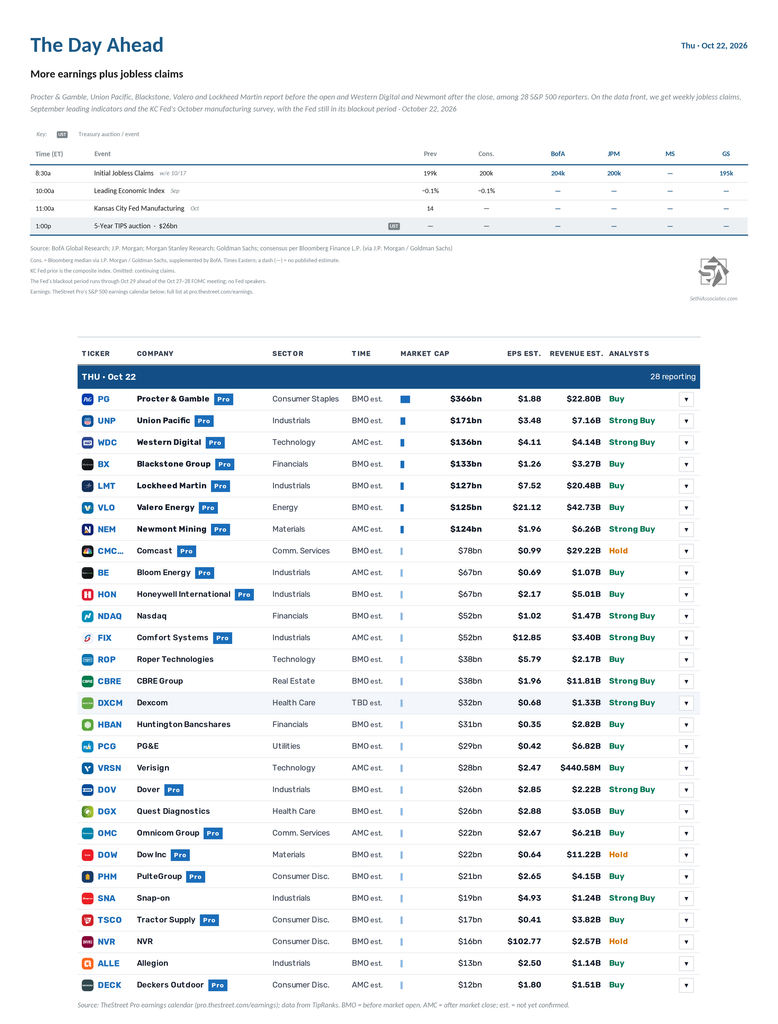
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.
Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble ($PG), Union Pacific ($UNP), Western Digital ($WDC), Blackstone ($BX), Valero Energy ($VLO), Lockheed Martin ($LMT), Newmont ($NEM), Comcast ($CMCSA), Norfolk Southern ($NSC), Bloom Energy ($BE), Honeywell ($HON), Nasdaq ($NDAQ), Comfort Systems USA ($FIX), CBRE Group ($CBRE), PG&E ($PCG), Roper Technologies ($ROP), Huntington Bancshares ($HBAN), VeriSign ($VRSN), Quest Diagnostics ($DGX), Dover ($DOV), PulteGroup ($PHM), Dow ($DOW), Snap-on ($SNA), Tractor Supply ($TSCO), NVR ($NVR), Allegion ($ALLE) and Deckers Outdoor ($DECK).
Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.