Upside, Downside Movers in the Morning

Upside

– $LPCN +40% (Health Canada approves TLANDO for testosterone replacement therapy)

– $APUS +9.4% (extends a high-volume rally tied to the BlockAssure agreement to build and operate the AssureChain insurance network)

– $PENG +4.3% (Q4 beat and FY27 sales and EPS outlook topped prior guidance and Street expectations on accelerating AI-infrastructure demand)

– CNQ +1.6%, APA +1.2%, OXY +1.0%, COP +1.0% (oil producers rise as crude climbs back above $100 a barrel)

Downside

– $CRBU -42% (launches a strategic-alternatives review, discontinues two allogeneic CAR-T programs and plans substantial workforce reductions)

– $BULL -30% (bipartisan House panel report says structural China ties pose national-security and US-user-data risks)

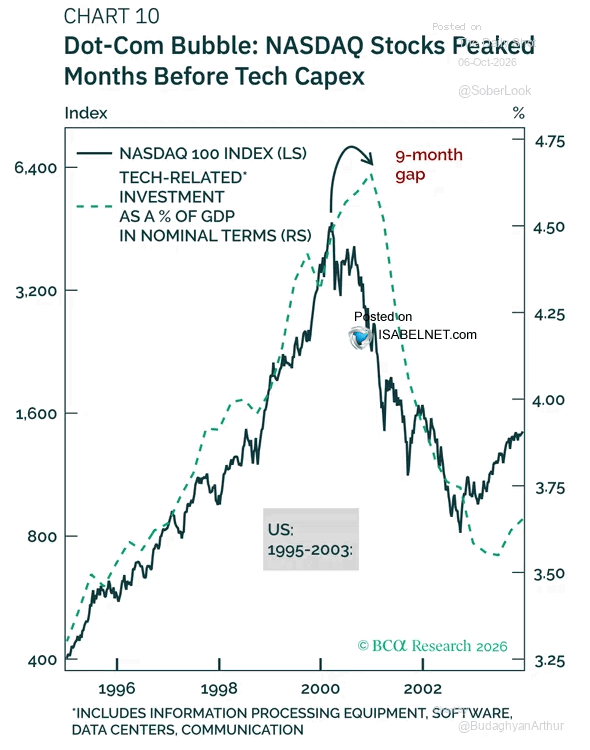
– $STM -5.4%, $TER -3.0%, $ASML -3.0%, $AMAT -2.7%, $LRCX -3.0%, $MU -2.8% (chip stocks fall in the risk-off technology tape as oil-driven inflation concerns pressure rate-sensitive growth shares)

– $BMNR -5.0%, $CRCL -4.0%, $MSTR -3.8%, $COIN -3.1%, $HOOD -3.0% (crypto-linked stocks fall as digital-asset prices weaken)

– $AAOI -4.8%, $CIEN -3.8%, $MTSI -3.0%, $COHR -3.2%, $GLW -3.3% (AI-networking and optical winners pull back after sharp recent rallies as technology exposure is reduced)

– $DB -4.7%, $SAN -4.2%, $HSBC -3.9%, $NWG -3.5%, $BCS -3.3% (European-bank ADRs fall as oil-driven inflation and sovereign-bond stress deepen fiscal concerns, with UK lenders also facing budget-tax fears)

– $STZ -3.9% (quarter beat, but adjusted FY guidance was merely reiterated and beer depletions declined)

– $BE -3.8%, $CEG -3.5%, $EME -1.9% (AI-power and data-center infrastructure winners give back part of recent gains amid the broader risk-off rotation)

Another Signpost That Rescheduling of Cannabis Is Likely

The IRS proclamation that they will looking at 280E guidelines (earlier this week) and the DEA info below seem to be concrete signposts that rescheduling of adult-use cannabis is very likely over the near term:

DEA Launches New Registration Forms For Medical Marijuana Manufacturers, Distributors And Testing Labs – Marijuana Moment

I added to $MSOS, $GLAS and $GTBIF yesterday.

Positions: MSOS common VL calls S GLAS S GTBIF S

Still On The Sidelines With Gold

* As we treat it as a “trading sardine”… and not as a foundational long

I treat all commodities and commodity-related equities as “trading sardines.”

While I view gold as a prime beneficiary of the profilgate spending in Washington, D.C. (and continued currency debasement) – I still see precious metals as a trade and not (yet) as a foundational position, particularly with interest rates on the ascent.

We traded in and out (profitably) three times in $GLD over the last 45 days or so – buying weakness and selling strength.

This morning is GLD is down by almost  five beaners as the US dollar advances higher and rates resume their rise:

  Positions: None

First Time, Long Time

Positions: None.

My GRNY Short and Bitcoin

I am clueless and not an authority about the price of bitcoin but this drop (last night) was abrupt:

I have been adding to my @GRNY short – which has a lot of crypto exposure.

Positions: Short GRNY M 

Diesel Prices Continue North

In my consumer is spent up and not pent up series I have discussed the impending weakness in the consumer — sticky and cumulative inflation (since 2020), a five month decline in real wages, a drawdown in the savings rate and the weakness in housing prices. 

Should energy prices continue their ascent I am fearful of an abrupt drop in personal consumption.

Moreover, the price of oil is likely to be a meaningful political issue in the mid terms.

Positions: None.

The Stench of Bad Breadth

I have been recently highlighting the deterioration in market breadth.

The stench of bad breadth was conspicuous yesterday:

For now, the S&P and the Nasdaq don’t care that the Russell isn’t crowing. 

My guess/bet is that this is not a permanent condition.

Position: Short SPY (M), QQQ (M)

El-Erian on the Global Rise in Interest Rates

The rise in interest rates is a global phenomenon which few are focused on.

Again, today, rates are on the rise:

Many in the Comments section are asking about buying Treasuries now.

However, given the stickiness of inflation, the continued mad rush of the AI spend, a sovereign retreat away from our Treasuries from non-U.S. nations (for political and non-political reasons), the (still) lack of fiscal discipline in Washington D.C. and the massive supply of Treasury and (AI) related corporate offerings, I am not there yet, even as the real interest rate expands.

Stay tuned on this…

Position: None