Wednesday’s Closing Market Stats

Closing Volume
– NYSE volume 4% below its one-month average
– NASDAQ volume 11% below its one-month average
– VIX index: up 0.53% to 15.09
Breadth
S&P 500 Sectors
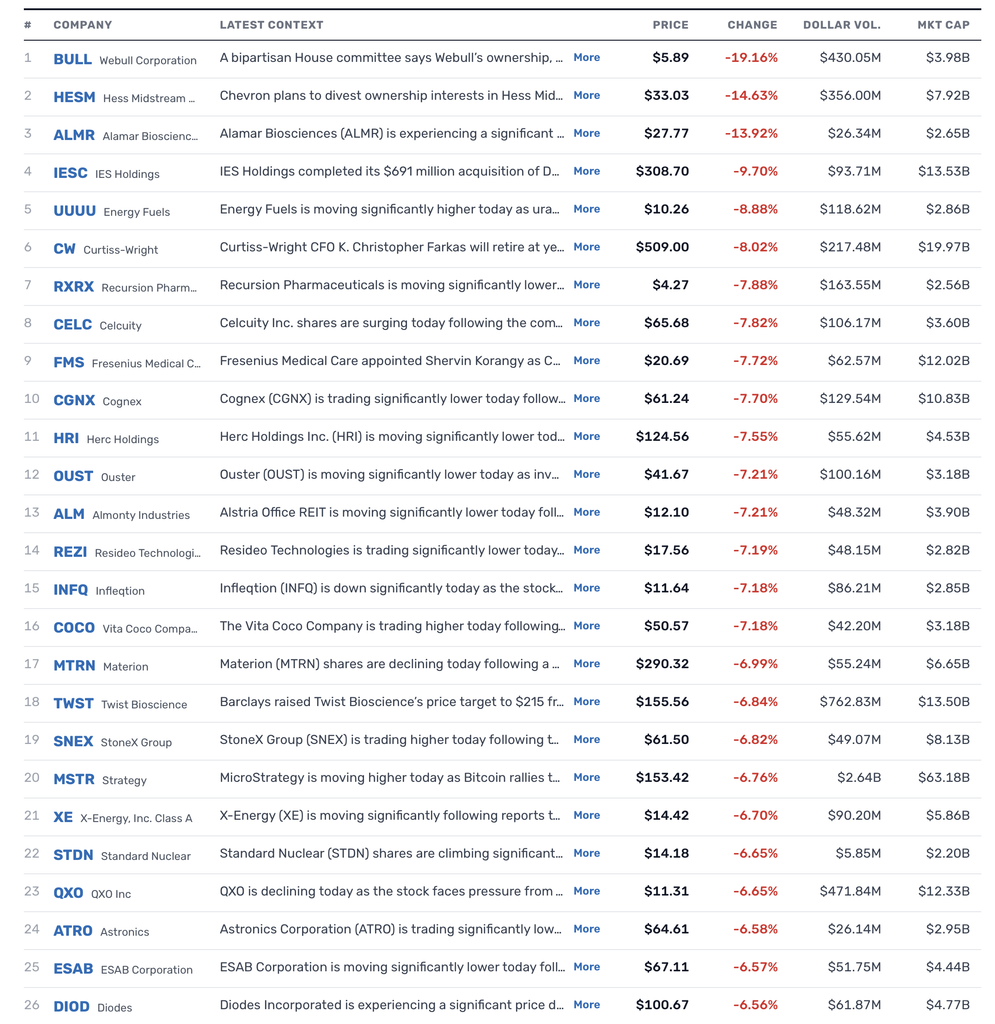
% Movers
Heat Maps
Position: None
Closing Volume
– NYSE volume 4% below its one-month average
– NASDAQ volume 11% below its one-month average
– VIX index: up 0.53% to 15.09
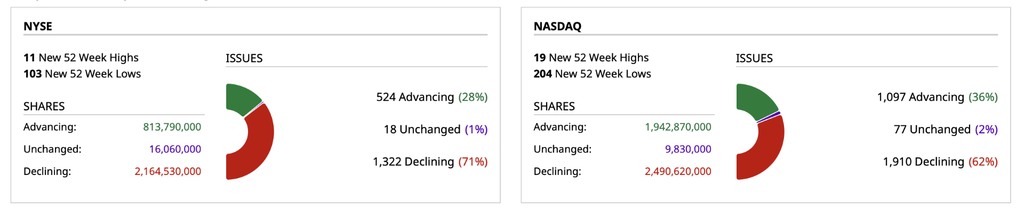
Breadth
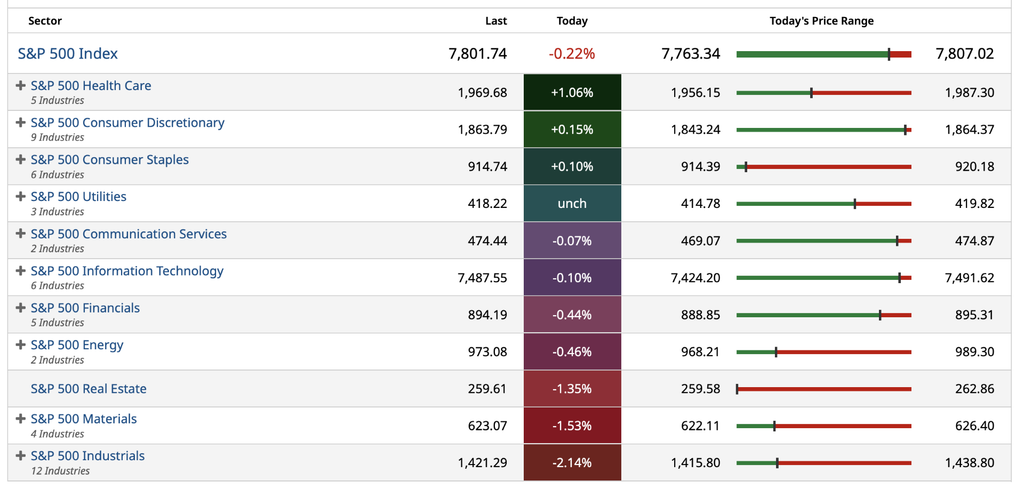
S&P 500 Sectors
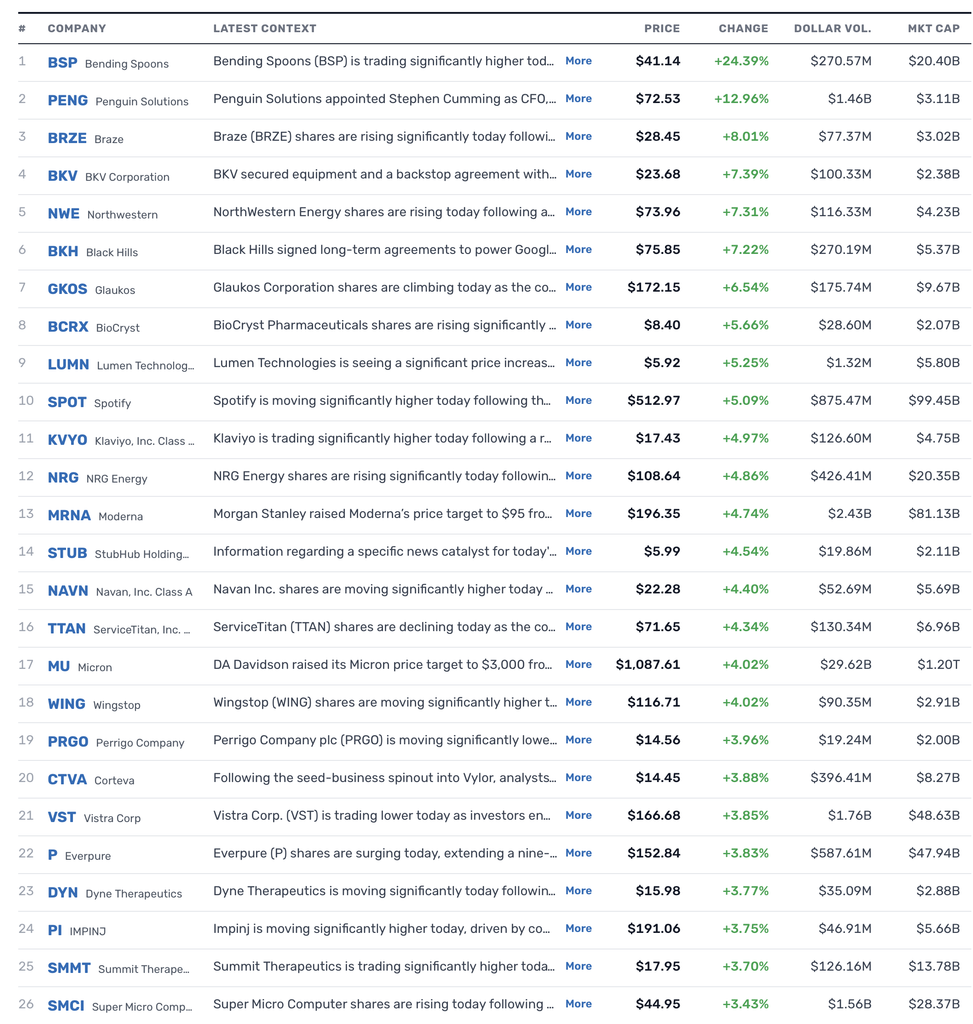
% Movers
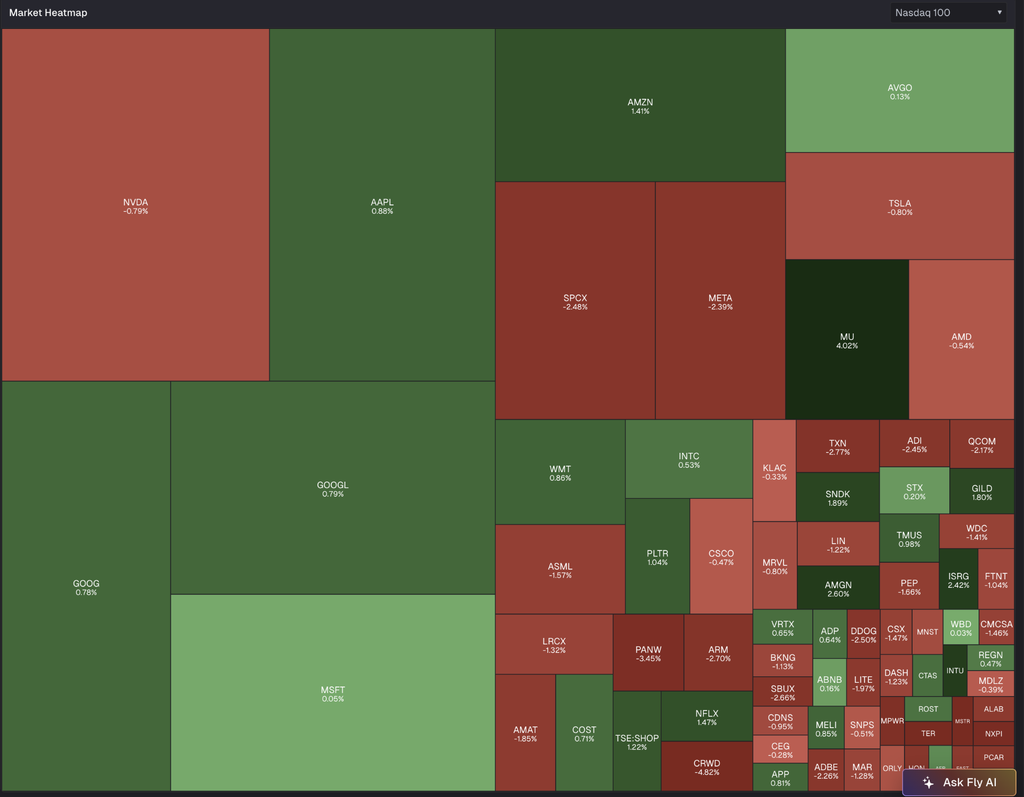
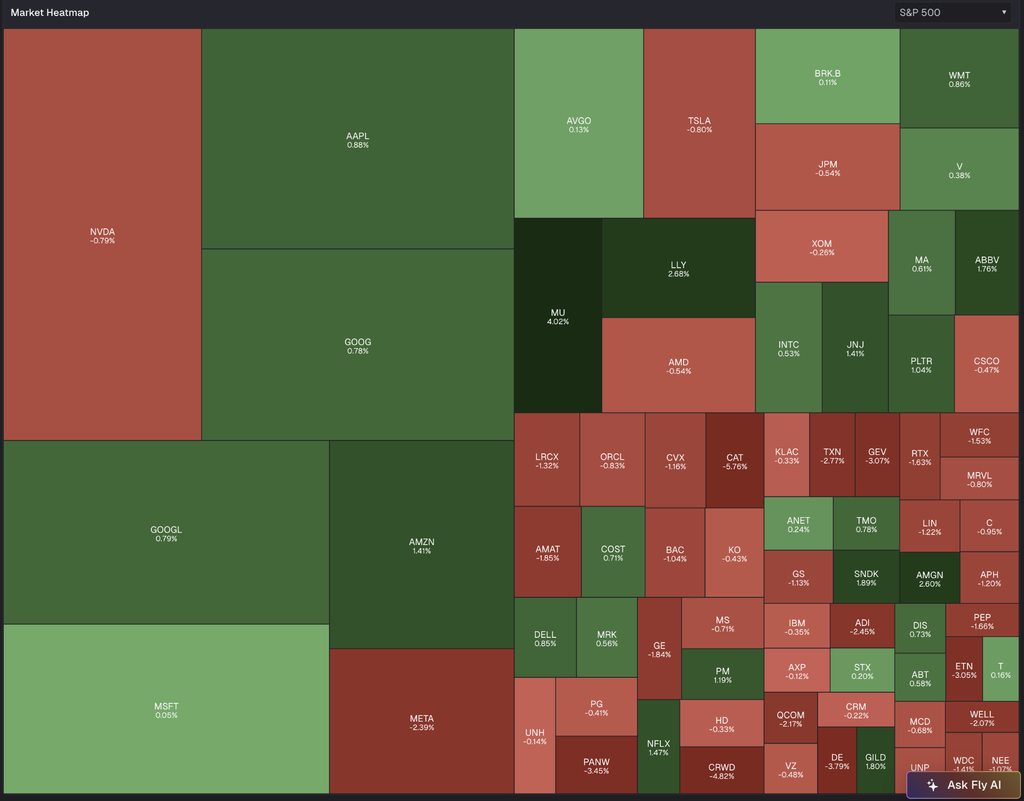
Heat Maps
Position: None
Breadth collapses, new lows swamp new highs and the Russell 2000 sits on its 200-day average.
The September minutes reflected a material hawkish shift from the July meeting with all backing the increase and ‘most’ expecting another hike before the end of the year
Res ipsa loquitor:
$SPY -0.27%
$QQQ -0.31%
$RSP -0.71%
$IWM -1.32%
Fortunately I have FIN TV turned off and I don’t have to hear about the market’s broadening (not!) — and how healthy the top heavy market is.
Position: Short SPY (VS), QQQ (VS)
* Play along with me on this one!
As I have mentioned recently I have noticed that on a very short-term basis $GLD has led $SPY.
GLD has rallied about +$2.50 from the lows after being -$8.
As GLD rallied so did the SPY.
But GLD seems to be making no headway after the dead cat bounce. Will SPY resume its downtrend over the balance of the day?
Maybe.
But I have still not reloaded on the short side, save the additional short in $GRNY.
And I have certainly not replaced my covered index shorts from the whoosh lower in the AM.
Position: Short SPY (VS), QQQ (VS), GRNY (M)
Wolf Street howls about the drag of high mortgage rates.
Mortgage Rates Jump to 7.5%, Home Buyers Pull Back Further, Demand Sags | Wolf Street
Position: None
P.S. I am not yet bottom-fishing in financials/banks.
P.P.S. I estimate that Bank of America ($BAC) has unrealized losses in its investment portfolio (mainly U.S. Treasuries) of about $92 billion. The other major money center banks have also been “dinged” by the decimation in fixed-income prices.
Position: None
I will be back in my office at 2 p.m.
That was a quick trip to NYC and back!
Positions: None
There are two major risks that investors seem more than happy to underweigh.
By Peter Boockvar:
The 10 yr note auction, with yields hovering around 24 year highs, was solid. The yield of 5.30% was almost 2 bps below the when issued pricing. The bid to cover of 2.77 was well above the one year average of 2.51 and that matches the highest since late 2014. Also, direct and indirect buyers took down 97.5% of the auction which is the most I’ve seen.
Bottom line, for whatever reason, likely the 24 yr highs in rates, brought out the buyers and resulted in a great auction. In response, the 10 yr yield has backed off to 5.27% from 5.31% just prior to the results.
Positions: None