New Apple Price Target as HomeView Comes Into View


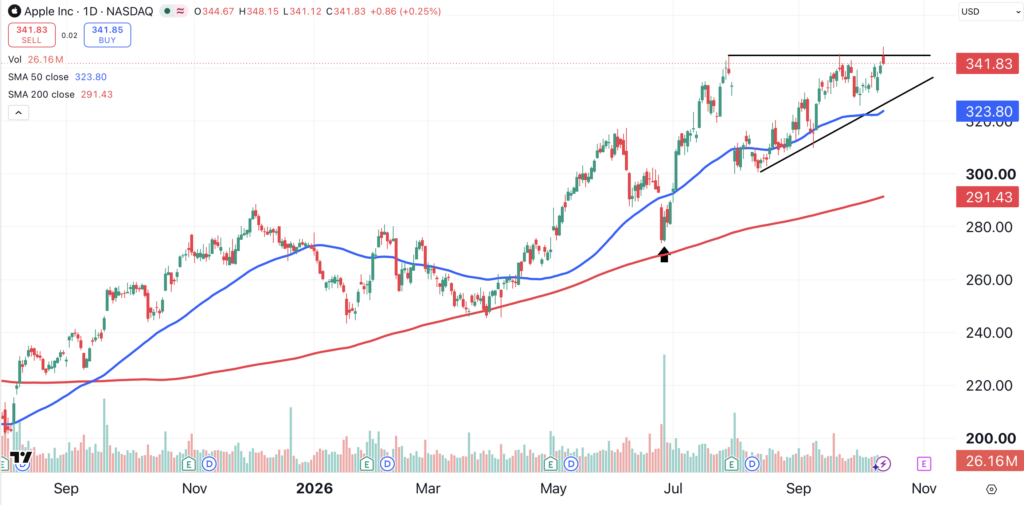
Shares of Apple ($AAPL) reached $348, their highest intraday price ever, Tuesday after the company announced a new home-based consumer product.
Apple is now accepting orders for HomeView. The new device, which can be free-standing or wall-mounted, will have a seven-inch screen.
HomeView can be used to monitor home camera systems, adjust the temperature, lock and unlock doors, and perform a variety of entertainment functions. The product, designed to compete with Amazon’s ($AMZN) Alexa and Google ($GOOGL) Nest, costs $299, and will become available on November 13.
HomeView also opens the door to as-yet unannounced future services. The product is designed to pull the user further into the Cupertino tech giant’s ecosystem by interacting with other Apple products and services.
Apple Services
Like any new Apple product, HomeView will be marketed to the company’s huge installed base. The company boasts 1.5 billion unique iPhone users worldwide, and 2.5 billion iOS devices.
HomeView could generate a flood of recurring revenue for Apple Services. That’s good news for the company’s bottom line, as Services products on average have gross margins of about 75%. Meanwhile, Apple hardware products have a gross margin of about 40%.
Apple’s New Price Target
Apple has formed an ascending triangle pattern (black lines) and is attempting to break out. Based on this pattern, along with the stock’s relative strength vs. the major indexes, our new price target for Apple is $390.
Home Security
While no announcement has been made, providing home security services seems like a no-brainer for Apple via HomeView. With new competition entering a crowded field, it should come as no surprise that several companies that specialize in residential security have already been routed.
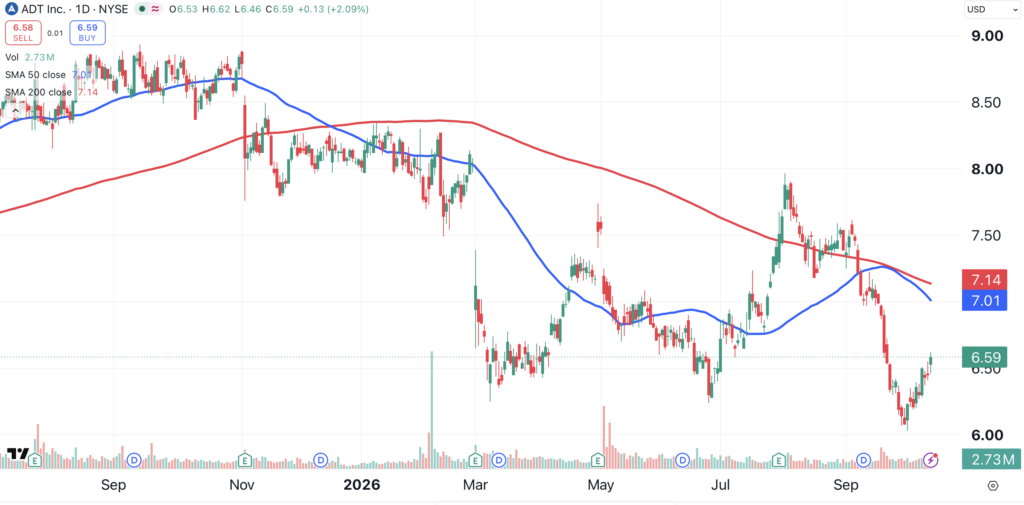
One of the leaders in that field, ADT ($ADT), has seen its stock fall 17.7% year-to-date, and 22.6% over the past 12 months.
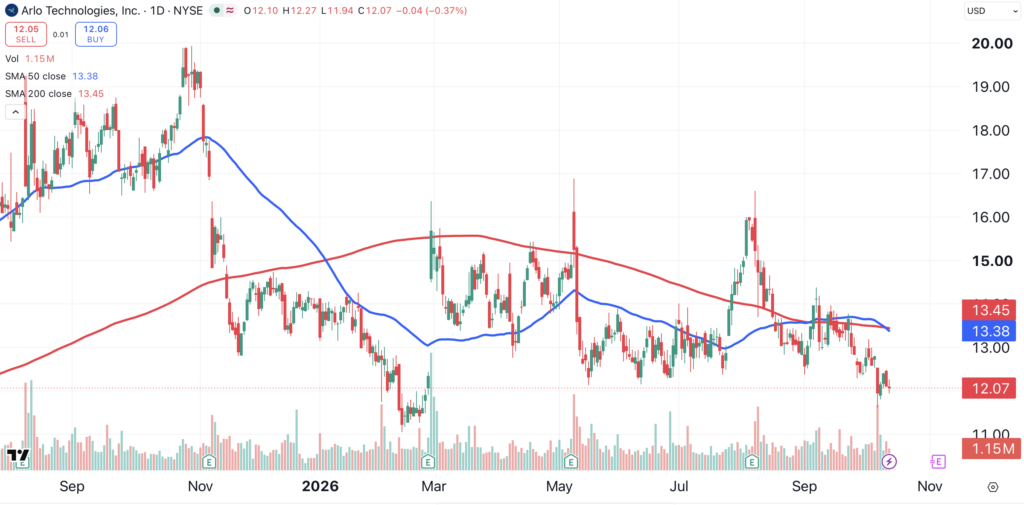
Arlo Technologies ($ARLO), another residential security company, has seen its stock fall by nearly 30% over the past year.
Bottom Line
Back in June, with Apple trading at $275 and falling, we described selling in the stock as overdone. In the three months since then, Apple has gained nearly 25%.
At the time, the stock was plunging due to higher component prices and supply bottlenecks. Three months later, those same issues, which also affect all of Apple’s competitors, are simply accepted as part of the reality of doing business in 2026.
Apple’s nearly 25% gain since that writing outpaces the S&P 500’s 8% return, and the Nasdaq Composite’s 9% gain. Apple continues to be a unique company that inspires fierce loyalty among its customers.
At the time of publication, Ponsi was long AAPL.
