Intel Sinks as PC Slump, Supply Snags Swamp 78% Data Center Surge

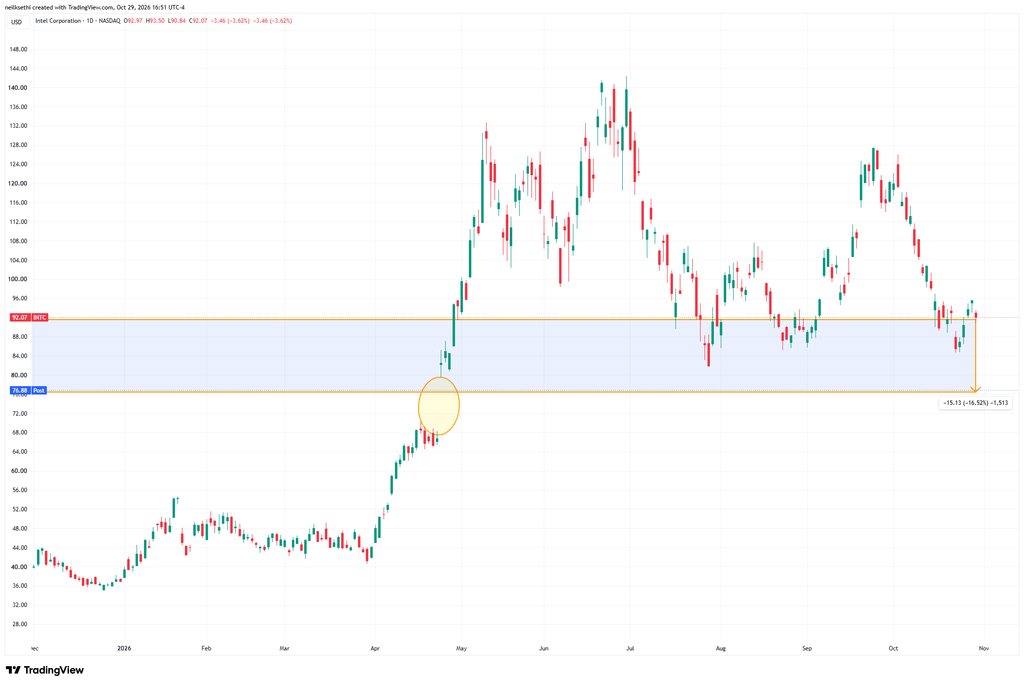
Intel ($INTC) shares are down over 16% after hours Thursday after the chipmaker forecast fourth-quarter revenue and profit well below Wall Street estimates, blaming a deepening PC slump and supply problems, even as its data center business posted its fastest growth in 15 years.
Notably, this would put Intel into a gap formed from its April earnings which extends down another 8% from where it was trading as of 4.50 p.m. ET.
Third-quarter adjusted EPS of 52 cents beat the TipRanks consensus of 41 cents. Revenue rose 21% to $16.51 billion, a hair below TipRanks’ $16.56 billion estimate, Intel said in its earnings release.
Beat on profit, ahead of its own guidance
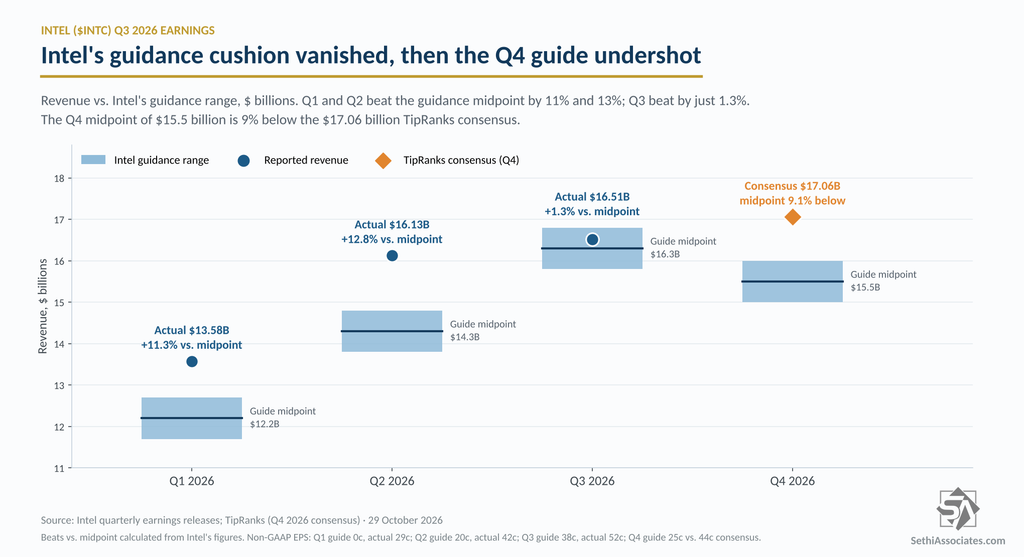
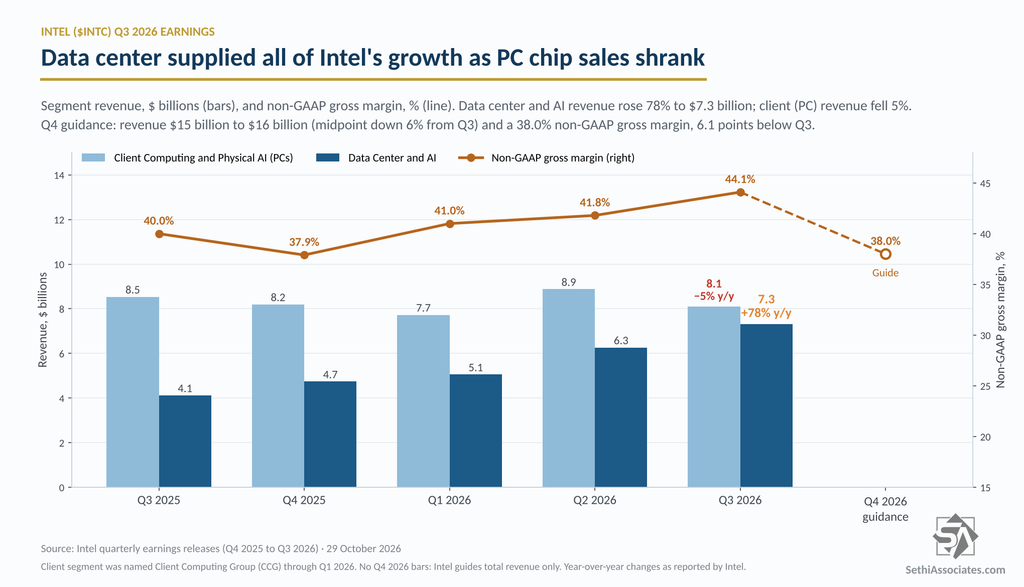
Intel topped its own targets though. In July, it guided third-quarter revenue to $15.8 billion to $16.8 billion, adjusted EPS to 38 cents and a 42.0% non-GAAP gross margin. Revenue landed $213 million above the midpoint, EPS beat that guide by 14 cents and gross margin came in at 44.1%.1
Non-GAAP gross margin rose 4.1 percentage points from a year earlier and 2.3 points from the second quarter. Non-GAAP operating margin climbed to 19.6% from 11.2% a year ago and 17.2% last quarter.
Per-share growth lagged profit growth. Adjusted net income jumped 169% to $2.76 billion, but adjusted EPS rose 126% because the diluted share count grew 17% to 5.31 billion after this year’s equity raises.1 GAAP EPS of 60 cents included a $1.0 billion gain on the mark-to-market of shares held in escrow for the U.S. government, worth 17 cents a share, which Intel excludes from adjusted results.
Data center carried the whole quarter
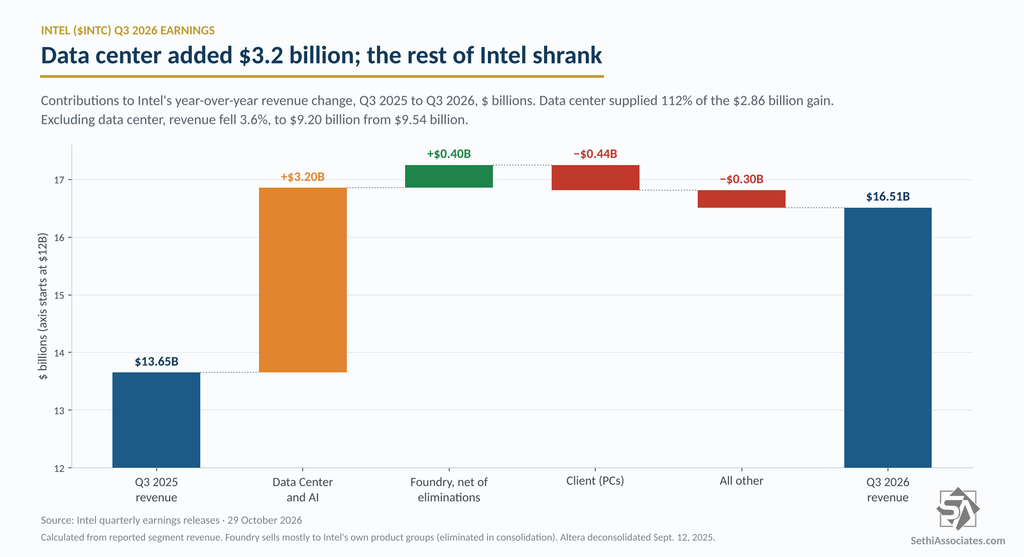
Data center and AI accounted for 112% of Intel’s $2.86 billion year-over-year revenue increase; excluding it, sales fell 3.6%.1
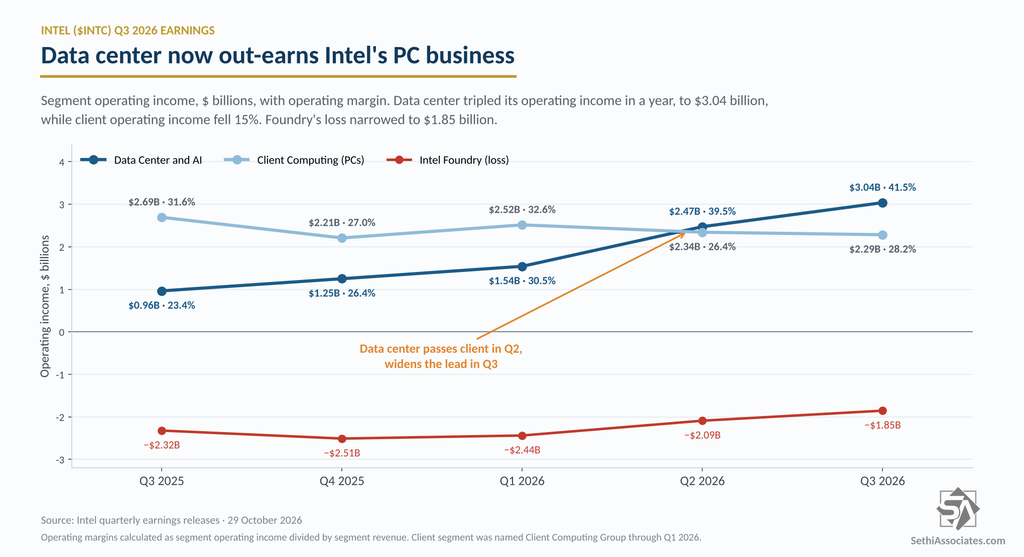
The segment’s revenue rose 78% to $7.3 billion, well above the $6.7 billion analysts expected, MarketWatch reported, and rose 17% from the second quarter. Its operating margin widened to 41.5% from 23.4% a year ago, and about 65 cents of each extra revenue dollar fell to operating income.1 Data center operating income of $3.04 billion topped the client unit’s $2.29 billion for a second straight quarter.
Client Computing and Physical AI, the PC chip unit, fell 5% to $8.1 billion, short of the $8.9 billion FactSet consensus cited by MarketWatch, and dropped 9% from the second quarter. Its operating margin slipped to 28.2% from 31.6%.1
The mix shift is stark. Data center now makes up 47.5% of Intel Products revenue, up from 32.5% a year ago and 41.4% last quarter.1
Intel Foundry revenue jumped 58% to $6.7 billion, ahead of the $6.4 billion consensus, per MarketWatch. Most of that is chips made for Intel’s own product groups and is eliminated in consolidation. The foundry operating loss narrowed to $1.85 billion from $2.32 billion a year earlier, cutting its loss margin to 27.7% from 54.8%.1 “All other” revenue fell 30%, partly because Intel deconsolidated Altera on Sept. 12, 2025.
The guide is the biggest problem
The $15.5 billion midpoint of Intel’s fourth-quarter revenue guide is $1.56 billion, or 9%, below the TipRanks consensus, and its 25-cent EPS guide is 43% below.1
Intel guided revenue to $15 billion to $16 billion, against $17.06 billion expected, and adjusted EPS to 25 cents, versus 44 cents, TipRanks reported. The midpoint implies a 6% sequential decline and slows year-over-year growth to about 13% from 21%.1
Margins take a bigger hit. Intel guided a 38.0% non-GAAP gross margin, 6.1 points below the third quarter’s 44.1%. On a GAAP basis, the guide is 37.1%, which is why some outlets reported 37% and others 38%.
Intel blamed a PC market squeezed by soaring memory prices. CFO David Zinsner said in the release that the PC slowdown will last “at least through the first half of next year.” Intel expects the PC market to shrink 10% in 2027 after a 12% drop in 2026, Bloomberg reported. CEO Lip-Bu Tan told Bloomberg data center sales would have been higher without raw-material shortages and a factory shutdown in Israel. Intel investor relations chief John Pitzer told MarketWatch an explosion at the Israel plant earlier this month weighed on the outlook.
Other issues
Inventory rose 4.6% from the second quarter to $13.1 billion, and 12.5% since year-end, while client revenue fell.1 Work-in-process inventory, at $8.8 billion, accounts for most of it. Intel says it is building working capital to increase supply, but rising inventory into a PC downturn is worth watching.
The client miss came from the bigger of Intel’s two product businesses. A segment analysts expected to grow 5% shrank 5%, and the fourth-quarter guide suggests the decline deepens.
Cash, capex and the balance sheet
Operating cash flow was $5.1 billion. Gross capital spending rose to $4.2 billion from $3.0 billion a year earlier, and adjusted free cash flow was $1.64 billion, up from $0.9 billion. Year-to-date gross capex totals $11.8 billion.1 Intel has pledged to spend $20 billion in 2026, the FT reported. If that refers to gross capex, it implies about $8.2 billion in the fourth quarter.1
The $23 billion equity offering completed in the quarter transformed the balance sheet. Cash and short-term investments reached $54.0 billion against $50.1 billion of total debt, a net cash position of $3.9 billion, compared with net debt of $9.2 billion at the end of 2025.1
The takeaway
The AI demand story for Intel held up this quarter, and the data center business is now Intel’s profit engine. But the stock had priced in a smoother transition. Expectations were high with shares up more than 140% this year coming into the print despite a more than 20% drop over the past month, per the FT. A guide that cuts revenue, margins and EPS at once, blamed on PCs, memory costs and a fab disruption, breaks that narrative for at least a quarter. Before the report, analysts’ average price target of $114.23 implied 24.1% upside, per TipRanks.
1 Calculated from figures in Intel’s third-quarter 2026 earnings release and, for prior-quarter and guidance comparisons, its second-quarter 2026 release. Segment contributions to the year-over-year increase use reported segment revenue; Intel Foundry net of intersegment eliminations added $398 million (14%), client subtracted $438 million and “all other” subtracted $301 million. Segment operating margins equal segment operating income divided by segment revenue. Net cash equals cash, cash equivalents and short-term investments minus short- and long-term debt. Consensus figures are from TipRanks unless noted; FactSet figures are via MarketWatch.