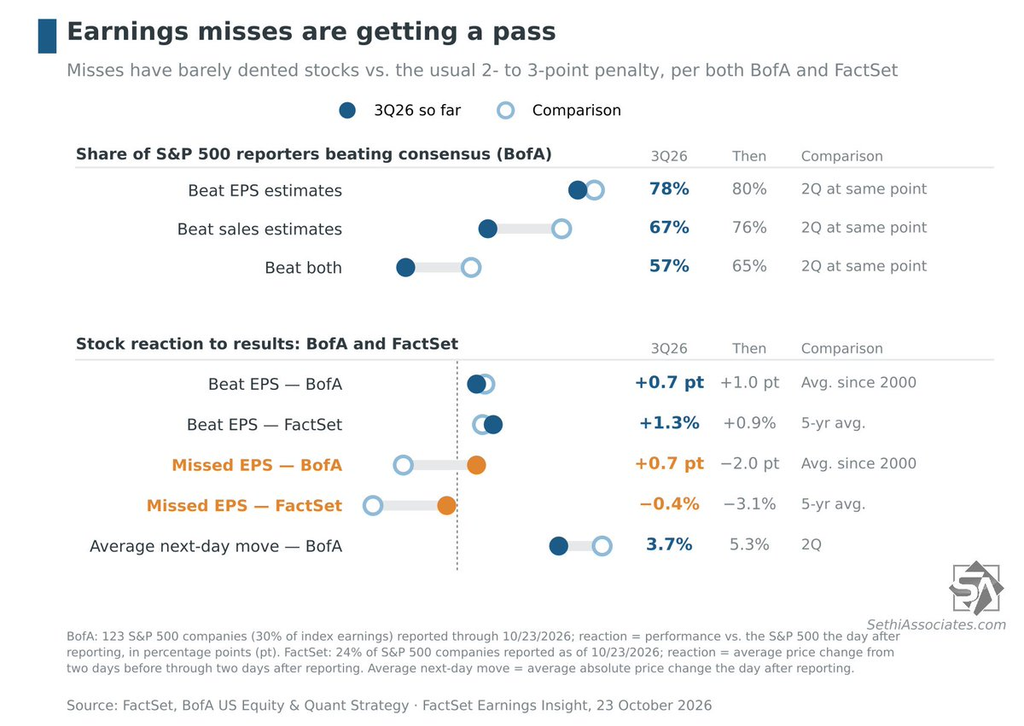
Earnings Misses Getting Light Treatment

Ahead of this week’s batch of earnings, a little surprisingly, misses have been getting a relative pass.
Per BofA, companies missing EPS estimates have outperformed the S&P 500 by 0.7 percentage points the day after reporting, vs. a typical 2-point lag since 2000.
FactSet finds the same: misses have fallen just 0.4% from two days before their reports through two days after, vs. a 3.1% five-year average.
Beats, in contrast, are being rewarded at roughly normal levels (BofA +0.7 pt vs. +1.0 average; FactSet +1.3% vs. +0.9%)
Overall, the average next-day move is 3.7% vs. 5.3% in 2Q.