BofA says their clients sold US equities last week (-$9.1B), led by institutions in their 10th-biggest selling week in BofA’s data since 2008.
October is typically institutions’ heaviest selling month as mutual funds harvest tax losses ahead of their 10/31 fiscal year-ends, and BofA says institutional single-stock sales this month, relative to market cap, are already the largest of any October in its data, with two weeks still to go.
Retail sold after two weeks of buying, and hedge funds for the first time in five weeks.
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.
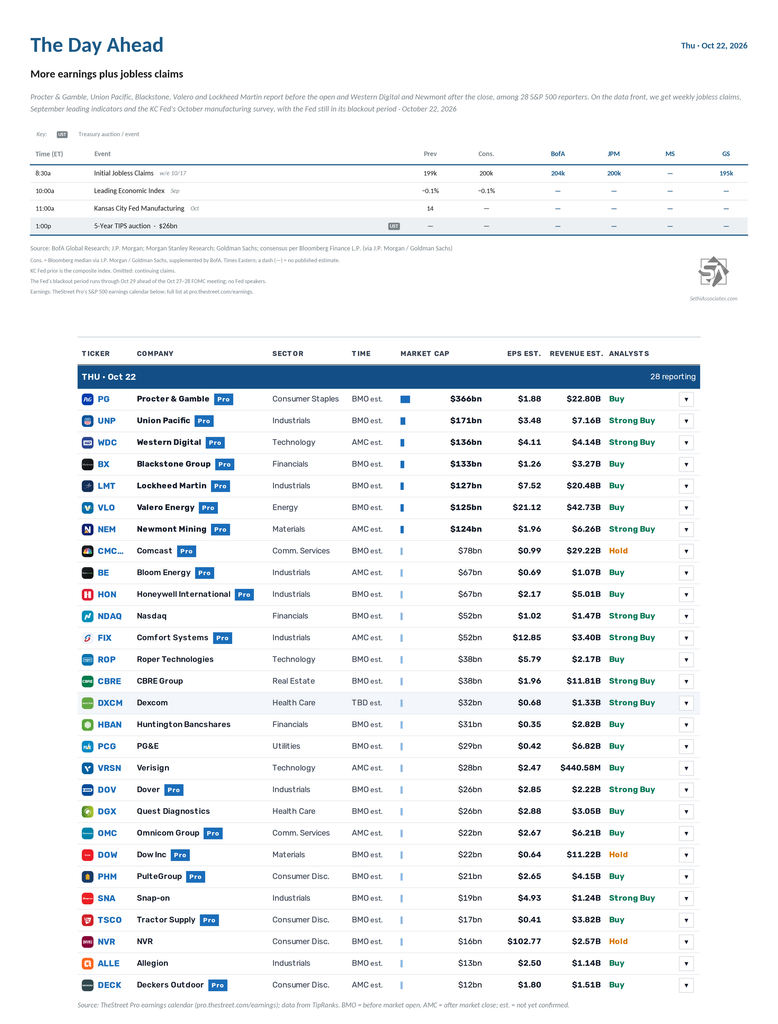
Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble ($PG), Union Pacific ($UNP), Western Digital ($WDC), Blackstone ($BX), Valero Energy ($VLO), Lockheed Martin ($LMT), Newmont ($NEM), Comcast ($CMCSA), Norfolk Southern ($NSC), Bloom Energy ($BE), Honeywell ($HON), Nasdaq ($NDAQ), Comfort Systems USA ($FIX), CBRE Group ($CBRE), PG&E ($PCG), Roper Technologies ($ROP), Huntington Bancshares ($HBAN), VeriSign ($VRSN), Quest Diagnostics ($DGX), Dover ($DOV), PulteGroup ($PHM), Dow ($DOW), Snap-on ($SNA), Tractor Supply ($TSCO), NVR ($NVR), Allegion ($ALLE) and Deckers Outdoor ($DECK).
Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.
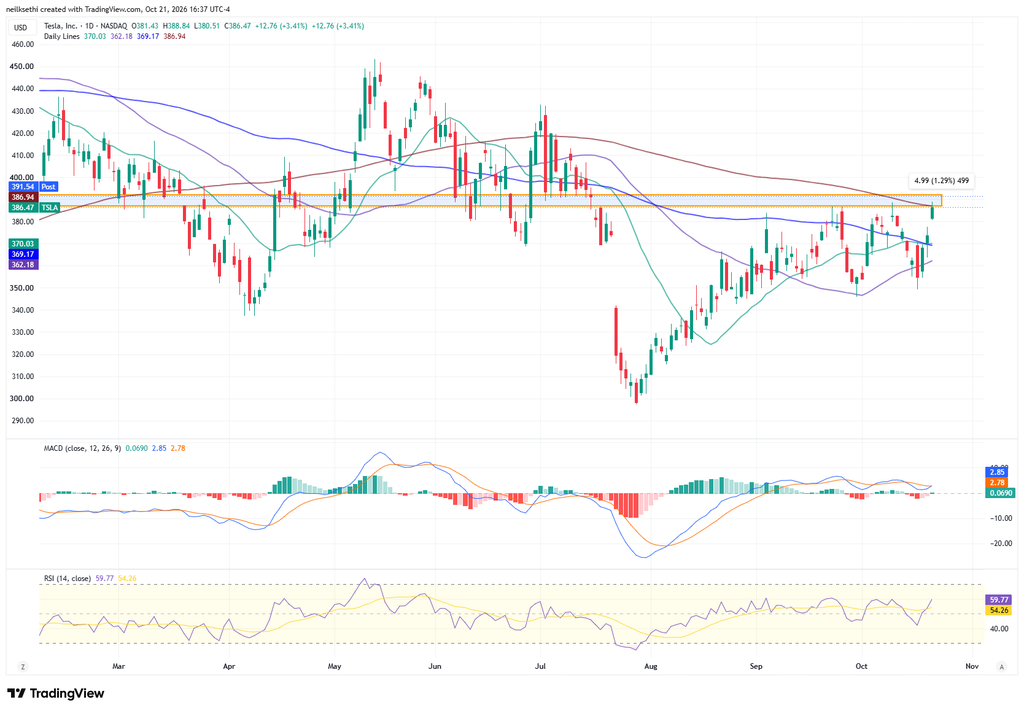
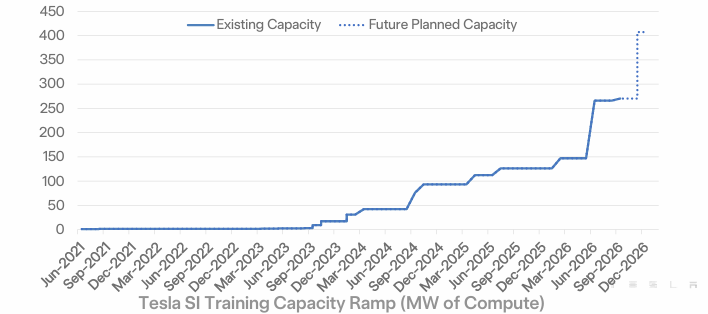
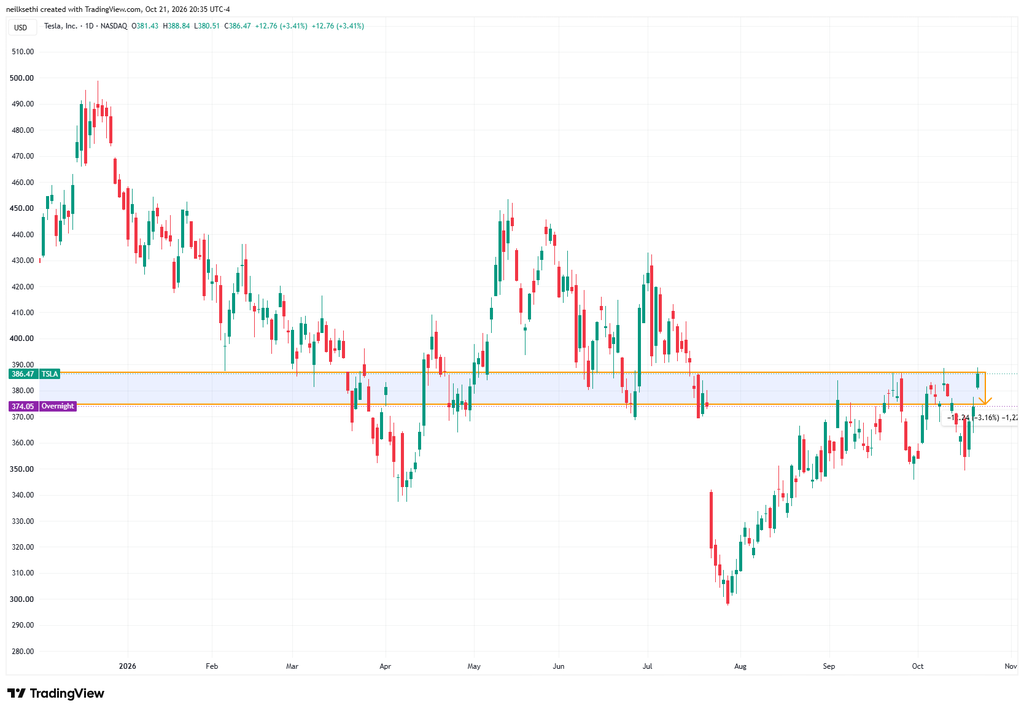
Tesla ($TSLA) shares are up a little over 1% after beating on the bottom line and reporting $1.5 billion of positive free cash flow versus expectations for a loss of $5 billion, assuaging some concerns surrounding the firm’s increased investments into robotics and AI. In that regard, capex was well under expectations at $4.73 billion (vs $2.25 billion the year-ago period). $7.95 billion was expected according to Bloomberg.
Gross margin also beat at 19.6%, while adjusted EPS of 48 cents topped estimates. Weakness was seen though in operating income which fell 56% from the year-ago quarter.
Revenue in Tesla’s core automotive business declined 3% from a year earlier, and while positive, free cash flow was down 62% year-over-year.
Active full self-driving (FSD) subscriptions rose to 1.74 million, up from 1.48 million in Q2.
Bloomberg also has an ongoing live blog for Tesla.
Update: Tesla sharesturned lower after Travis Axelrod, Tesla’s head of investor relations opened up the conference call with “We will not be addressing any questions today on a potential merger with SpaceX ($SPCX).”
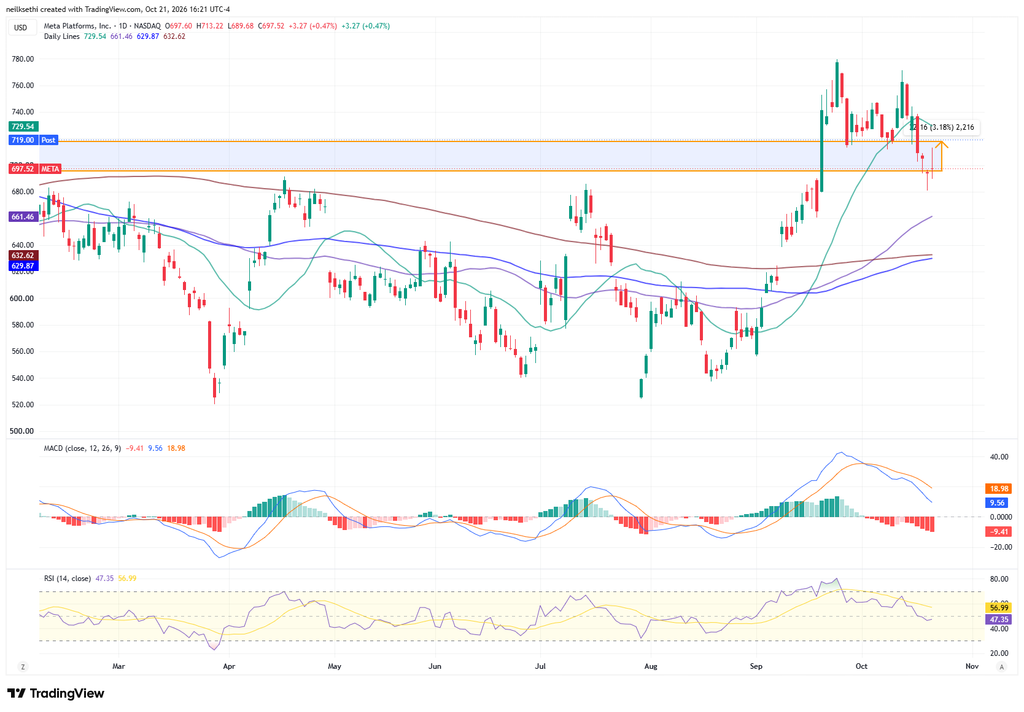
Meta Platforms ($META) shares are up 3% in the after-hours after better than expected Q3 revenues and a raise to Q4 guidance to $73 billion to $76 billion, above analyst estimates of $73.6 billion according to Bloomberg. The firm though declined to provide a 2027 outlook.
The company also lifted the bottom of its 2026 capex to $135 billion (to $145 billion) from $130 billion previously.
But the headline may be the creation of a new class of publicly listed non-voting Class C common stock, with an effective date in January 2027. The goal is to “provide Meta the ability to finance its growth and help the company remain a leader among fierce competition both domestic and international.” The new class of shares will be distributed to existing investors through a stock dividend. Holders will get one share of the new stock in what will essentially be a two-for-one stock split, Meta said.
“Our investments are paying off, the core business is strong, and we’re seeing velocity across the board,” Chief Executive Officer Mark Zuckerberg said in Wednesday’s report.
Bloomberg has a live chat ongoing if you want to follow the twists and turns of the earnings call.
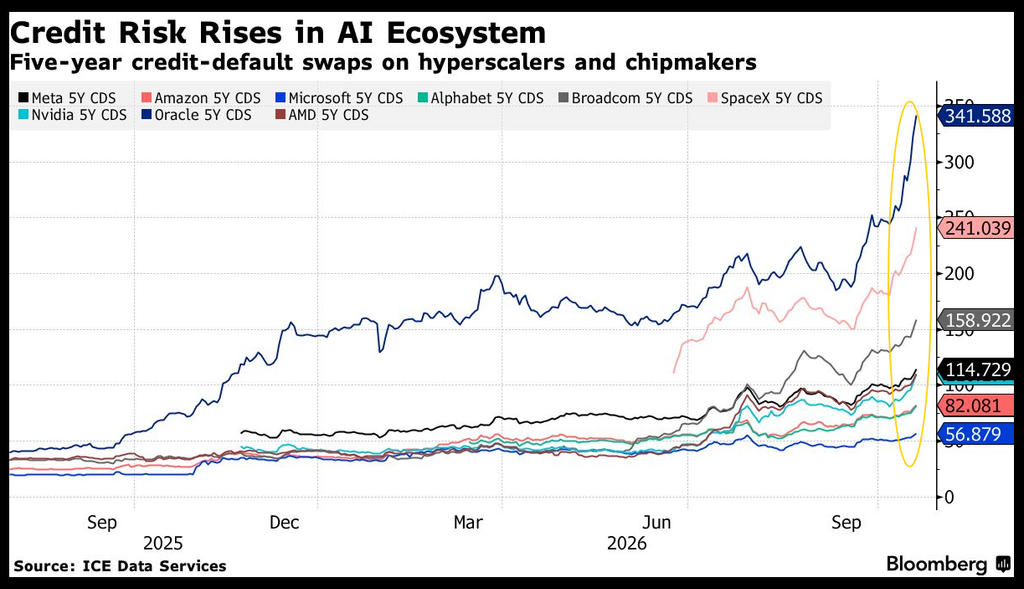
Ahead of Meta’s ($META) earnings, 5-year credit default swaps hit new record highs on Tuesday across a range of the largest Tech companies.
“Credit default swaps tied to Oracle Corp. ($ORCL), broadly seen as a barometer for AI debt risk, traded as high as a record 343 basis points, ICE Data Services data shows. A gauge of Meta’s credit risk has also touched an all-time high, soaring as much as 6.3 basis points to 114.8 basis points ahead of its earnings report Wednesday, the data shows.”
“We have yet to find some kind of a landing zone for the level of debt issuance that the market needs to absorb,” said Lotfi Karoui, multi-asset credit strategist at Pacific Investment Management Co in an interview Tuesday. “There’s still a wide range of estimates as how much debt capital this build out will end up consuming in general.”
That comes after $451 million of hyperscaler bonds were bought on Monday, the highest net buying since mid-September — likely a result of investors selling hyperscaler debt due to supply and demand concerns, according to Bank of America.
With the rise in funding costs there hasn’t been a hyperscaler bond deal in two months. We’ll see if we get news of one from Meta who previously said in April they would not issue again until the fourth quarter. Notably, Meta has moved up its normal last Wednesday of October reporting date a week, many think to do just that.
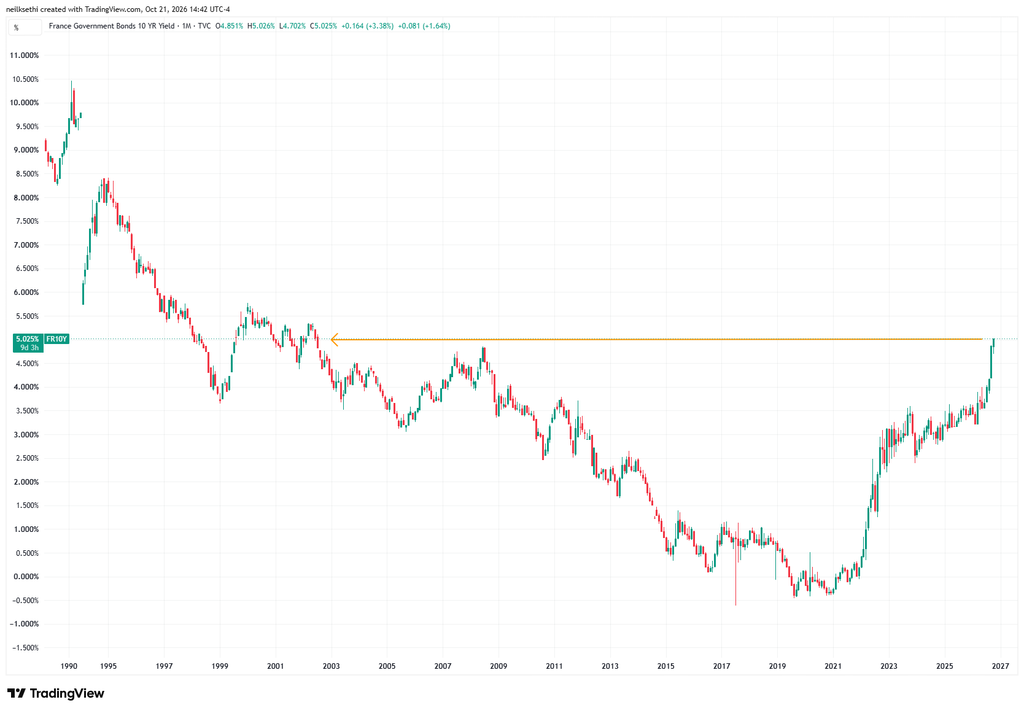
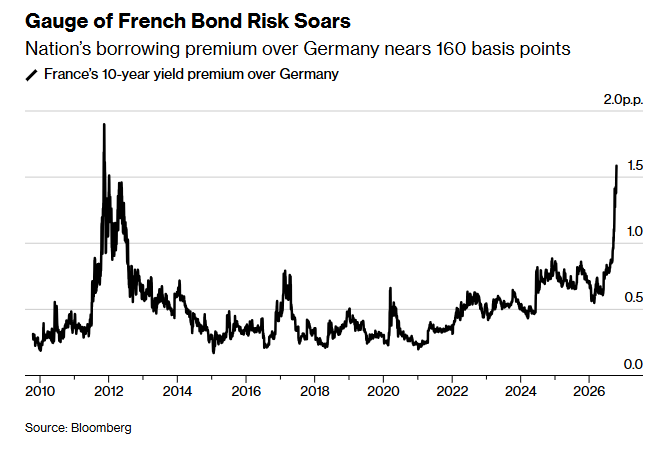
French 10-year bond yields join the U.S. in the 5% club, hitting that mark for the first time since July 2002.
While bond yields are rising globally, France has been hit especially hard by concerns over its precarious fiscal position, made worse by higher energy prices. Leadership there faces growing discontent over cost-of-living issues that have sparked violent protests, with similar unrest flaring in Italy, Belgium and Portugal. But its options are limited with the debt ratio already near 120% of GDP, almost twice Germany’s. Some investors are going so far as to draw parallels with Greece, the epicenter of the crisis that nearly splintered the euro zone early last decade.
Those worries have pushed the gap between French and German yields to nearly 160 basis points, the most in 15 years (chart via Bloomberg). That has forced policymakers to more seriously consider a proposed 2027 budget with about €43 billion ($48 billion) in deficit-cutting measures, but Prime Minister Sébastien Lecornu still lacks a majority to pass it. Moody’s is also due to rule on France’s credit rating Friday, with most economists expecting a downgrade. Oh, and presidential elections are just six months away.
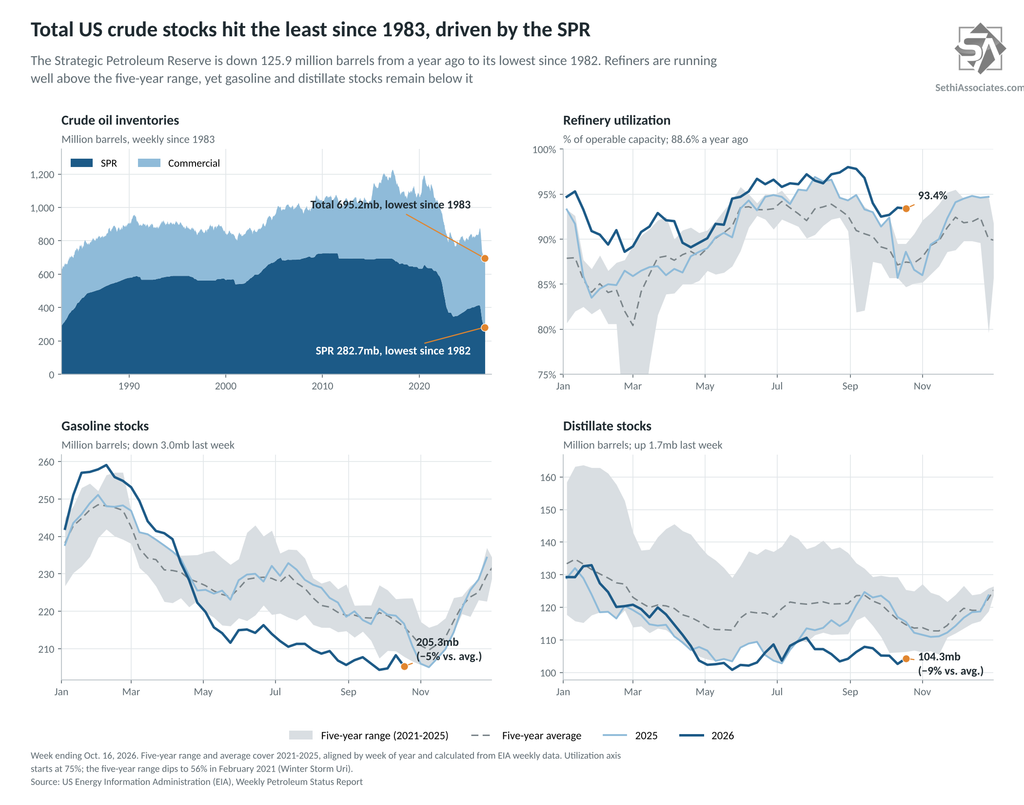
Total U.S. crude oil inventories (commercial plus the Strategic Petroleum Reserve) extended their slide to 695.2 million barrels last week, the least since October 1983, per the EIA. The SPR is driving it, accounting for 125.9 million of the 136.2 million barrel drop in total inventories from a year ago.
The SPR slipped another 0.3 million barrels to 282.7 million in the week ending October 16, its lowest since 1982 and down 30.8% from a year ago. But commercial crude drew 3.1 million barrels to 412.5 million, the third straight draw (14.8 million barrels over those three weeks). That left it 3% below the five-year average and the lowest for this time of year since 2014.
Turning to products, those also remain historically low even as refiners are running hard: ▪️ Refinery utilization was 93.4%, versus 88.6% this week last year and well above the five-year range. ▪️ Gasoline fell 3.0 million barrels, the biggest draw since early May, to 205.3 million, 5% below the five-year average. Gasoline demand rose 575,000 barrels a day to 8.98 million. ▪️ Distillates rose 1.7 million barrels, the first build in five weeks, but are still 9% below the five-year average. ▪️ Products are also being drawn down by exports which are up 6.8% from a year ago on a four-week average.
One other notable: crude production fell 410,000 barrels a day to 13.27 million, the lowest since late January, as Hurricane Isaias kept Gulf of Mexico output offline (57% was still shut in as of October 12, per BSEE). Expect a rebound as platforms restart.
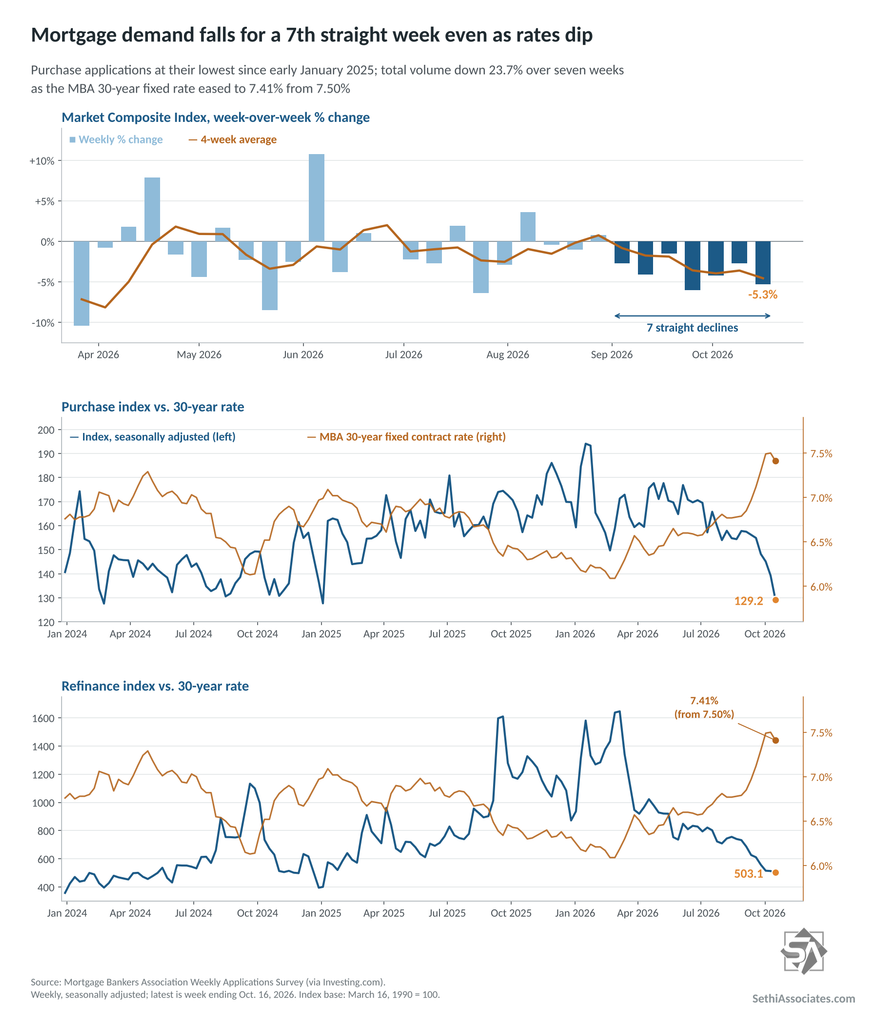
Mortgage applications fell 5.3% last week, according to the Mortgage Bankers Association (MBA), the seventh straight weekly decline, even as the 30-year fixed rate eased to 7.41% from 7.50%, its first drop in over two months. Total volume is now down 23.7% over those seven weeks.
▪️ Purchase applications fell 7% to their lowest level since early January 2025 and were 18% below a year ago. ▪️ Refinance applications fell 2% and were 59% lower than a year ago, with rates more than a full percentage point above where they were then.
MBA’s Joel Kan: “Lower rates were not enough to boost application activity, as both purchase and refinance applications continued to decline.”
CNBC’s housing reporter Diana Olick said buyers are reacting less to the weekly move in rates than to the overall higher level. The MBA’s 30-year rate has gone from 6.09% in February to 7.41% now.
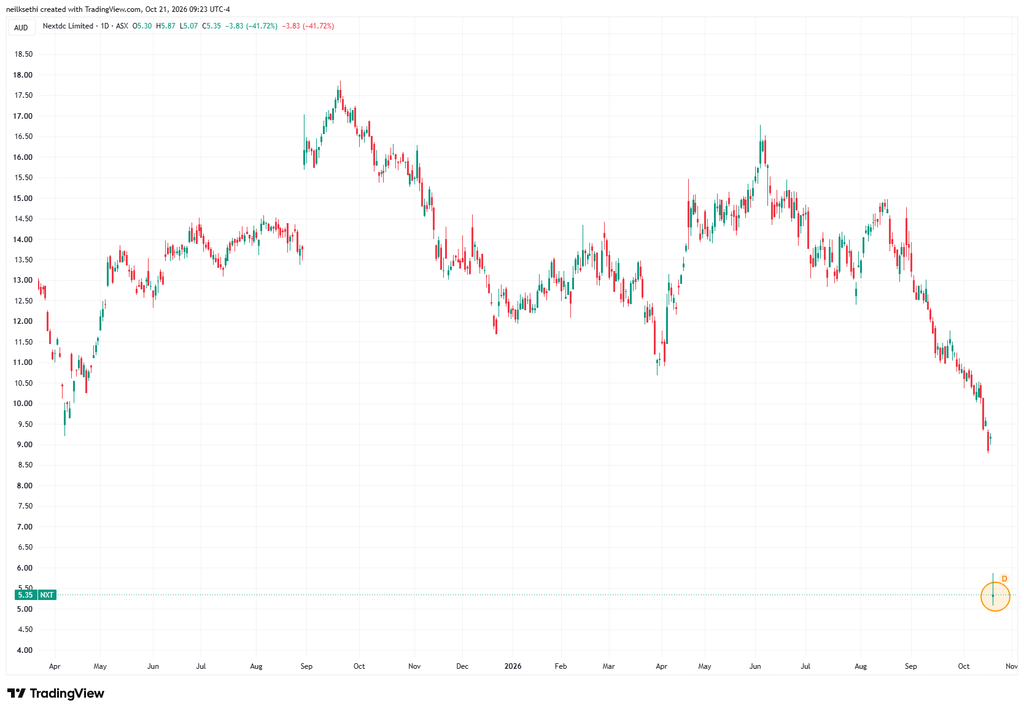
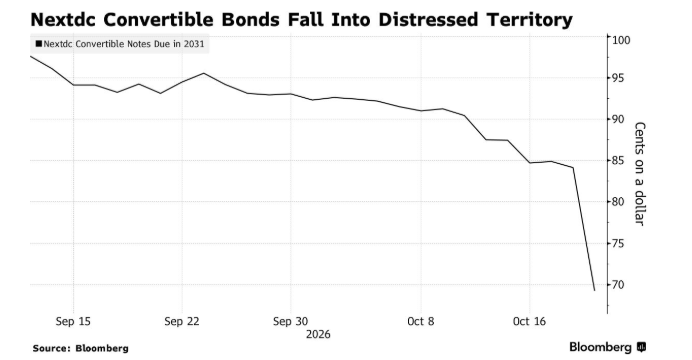
It’s not all positive in tech-land though as Australian data center firm Nextdc ($NXT) slashed its full-year earnings guidance by a third and placed development plans on hold after protests delayed power supply to one of its major projects in Melbourne that saw the firm pause all new development work, a caution sign for other global projects that have run into opposition.
Its shares plunged almost 42% in Sydney — the most since listing in 2010 — cutting its value to about A$4 billion ($2.8 billion) while its bonds fell into distressed territory.
The delay forces the company to defer roughly A$140 million of contracted customer revenue in this financial year. Management has announced it will pause all new development projects. It has 17 in operation and 11 in development or planning.