A Look at Financials Intraday

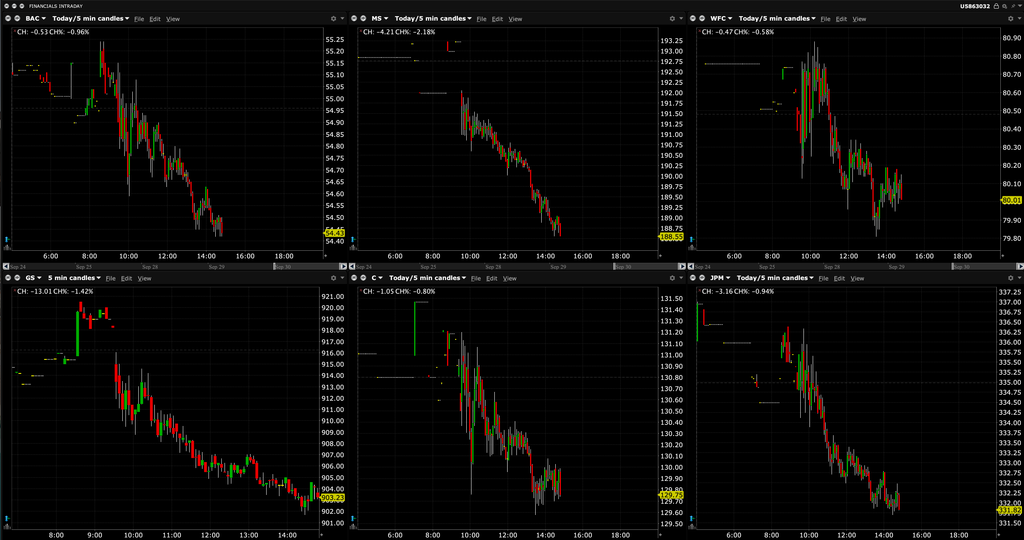
As of 2:49 PM:
Position: None
As of 2:49 PM:
Position: None
As of 1:45 PM:
Position: None
From The Credit Strategist:
When the Federal Reserve sets its baseline interest rate (the Federal Funds rate) well below the real-world rate of inflation (and below understated government-measured inflation), it leaves the door open for above-trend inflation. It also creates incentives for economic actors to borrow and spend money on speculative and unproductive activities – those that don’t add to the productive capacity of the economy. And that is precisely what happened for years, certainly since the 2008-9 Great Financial Crisis. Kevin Warsh has been pointing this out for years. Now he’s in a position to do something about this long-term monetary policy error. Despite the institutional and political resistance to raising interest rates to positive real territory, investors betting against Warsh are likely underestimating his determination to raise real rates. His criticism of the Fed’s policy errors is longstanding, principled, and evidence based. He is moving deliberately to correct these errors by organizing five “task forces” to reconsider different aspects of Fed policymaking in an effort to return to “first principles” of monetary policy from which the Fed has diverged. He wants to establish a more intellectually robust regime that reflects economic reality rather than the politically distorted process (including misleading government data) that led to years of monetary policy errors. If he succeeds, it will be a sea-change in monetary policy. Many Fed watchers on Wall Street initially argued that Warsh would not challenge the status quo and instead conform to politicized calls for lower rates that have no basis in the data; they are now coming to realize that Warsh meant what he said when he criticized Fed policy in the past and has the intellectual and intestinal fortitude to back up his words regardless of resistance. Investing on that basis will prove to be the better course in the period ahead.
The massive growth of debt creates the illusion that economic growth is strong and healthy by flattering corporate earnings and stock prices. But without $2 trillion annual U.S. deficits and huge government borrowing in Europe, China and Japan, economic growth would be much lower as would corporate earnings and stock prices. Economies are growing in nominal terms, but real (inflation-adjusted) growth is much lower – and most of the growth we see is dependent on a concomitant build-up in debt that can never realistically be repaid in constant dollars. That consigns the world to future inflation. Accordingly, the wealth created by this process is less than it seems and wholly dependent on the Ponzi-like structure of public and private sector financing where debt is incessantly refinanced and extended into the future. Any breakdown in that process will materially reduce if not destroy wealth, but even before that happens, the value of the fiat currencies in which that wealth is denominated keeps eroding steadily under the pressure of rising inflation.
Rising global interest rates, especially those at the long end of the curve, are signaling that we are above the levels where current levels of borrowing can be maintained without moving us toward crisis. Yields are reacting to strong economic growth, but that growth would not be happening without epic government and private sector borrowing. As such, arguments that higher yields are a purely positive reflection of a healthy economy are incomplete at best and misleading at worst. At the end of the day, the growing economy is going to have to deal with the debt that made it look so healthy. Readings like the ISM Services Index hitting 58.7, its highest level in 59 months, and the ISM Manufacturing Index hitting 56.7, its highest in 33 months, reflect economic strength. But those figures have to be read in the context of all the debt employed to reach those levels that are rarely mentioned in any analysis. Growth is not organic because it is debt dependent. Absent massive borrowing, it would be much lower.
Position: None
Wolf Street howls about changes to methodology of the calculus of inflation.
Not Even the Massive Changes of Methodology Can Get PCE Inflation Back into the Bottle | Wolf Street
Position: None
The attached pdf below is a thorough briefing of the ALJ stay and the GAO Drug Scheduling Report.
Most importantly this is a procedural issue.
Go to page six for the possible outcomes.
I continue to add to the space.
Position: None
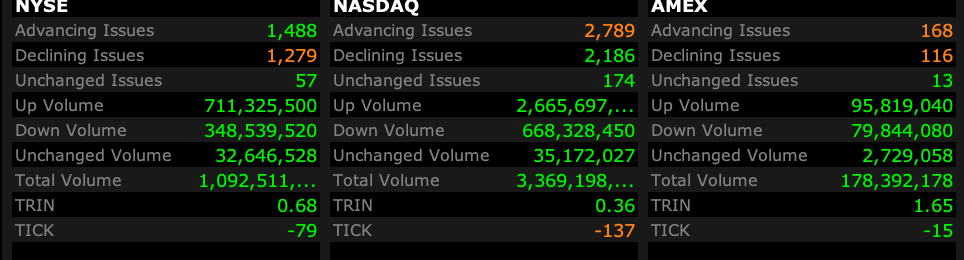
– NYSE volume 145M shares, flat to its one-month average;
– Nasdaq volume 33% above its one-month average;
– VIX Index: down 1.06% to 15.87
SOURCE: Interactive Brokers
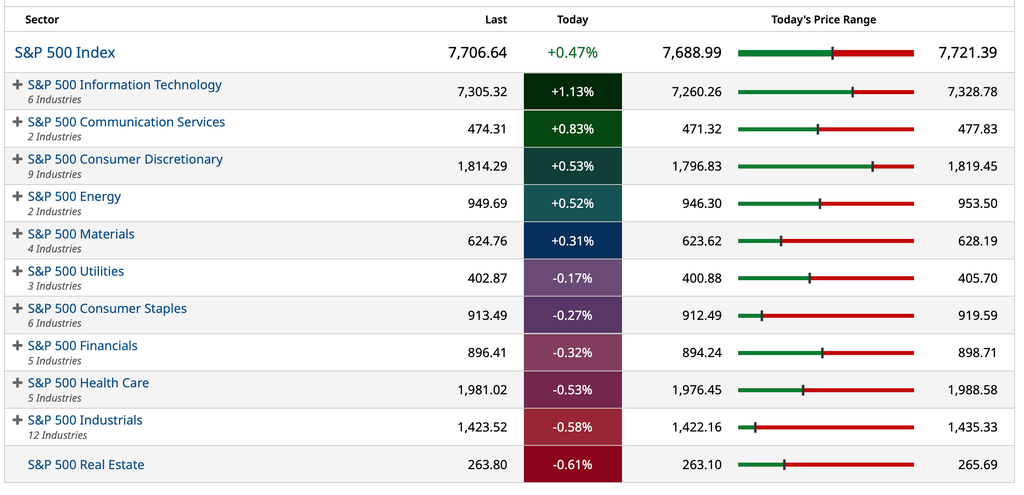
SOURCE: Barchart
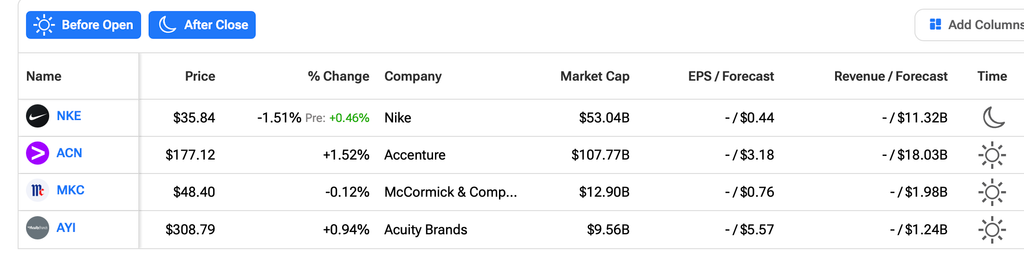
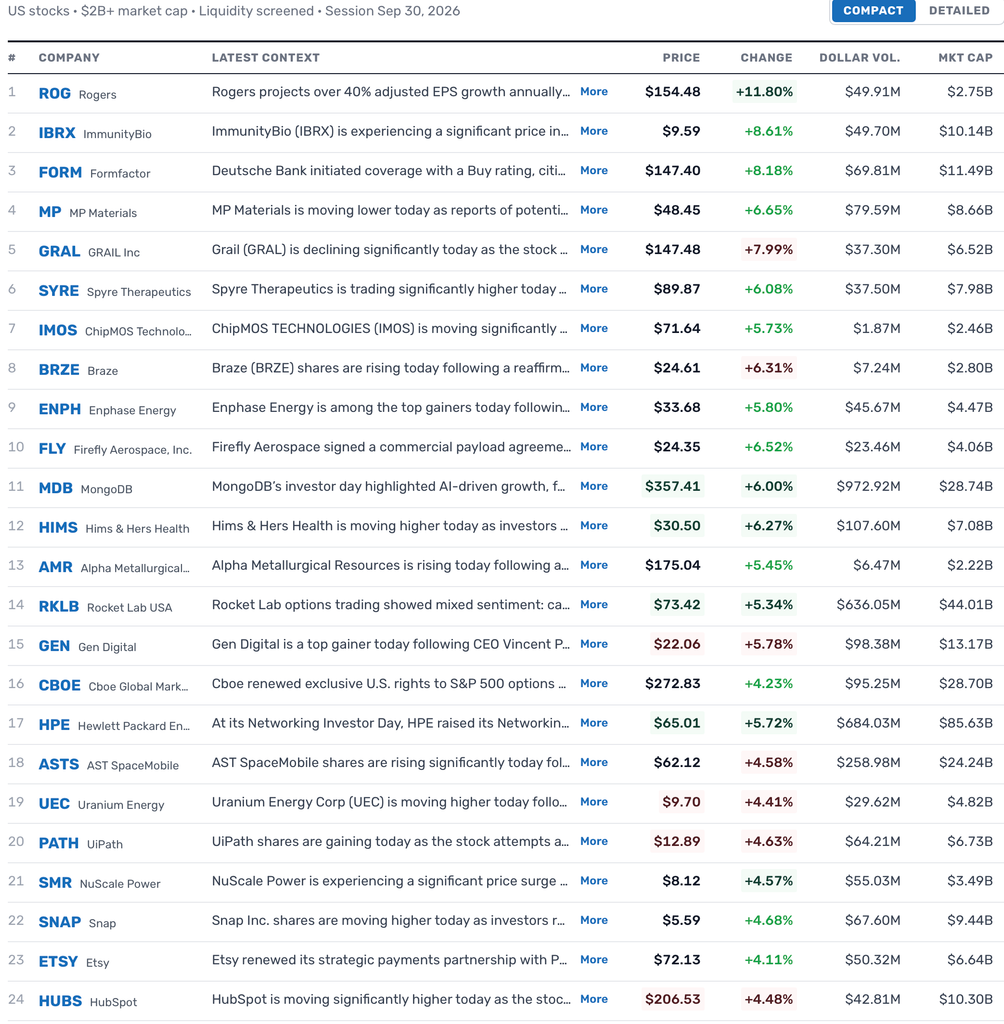
SOURCE: TheStreet Pro
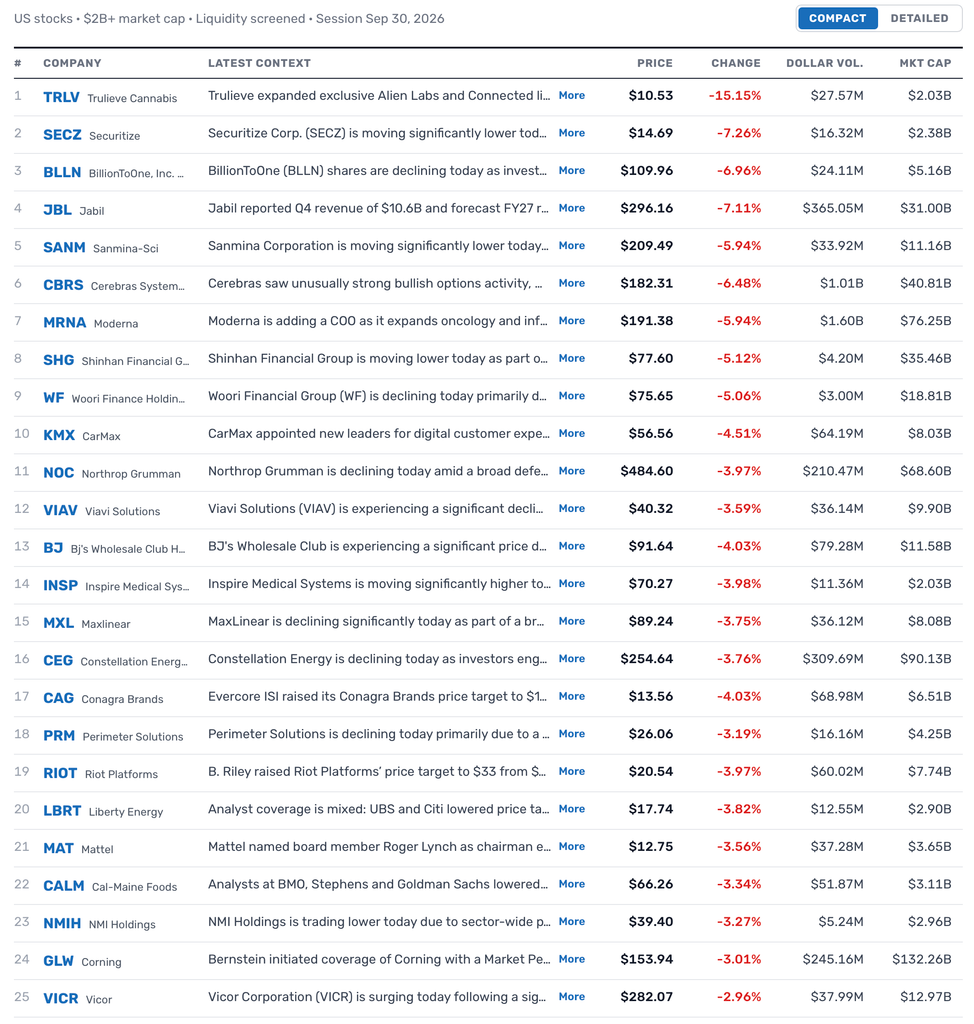
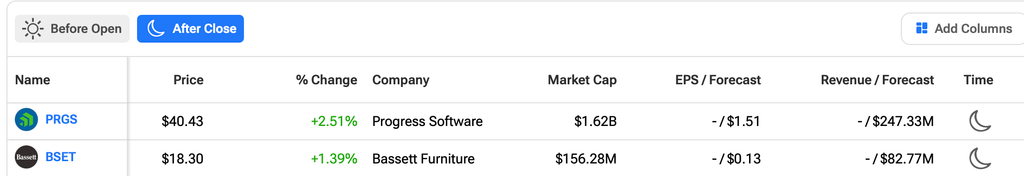
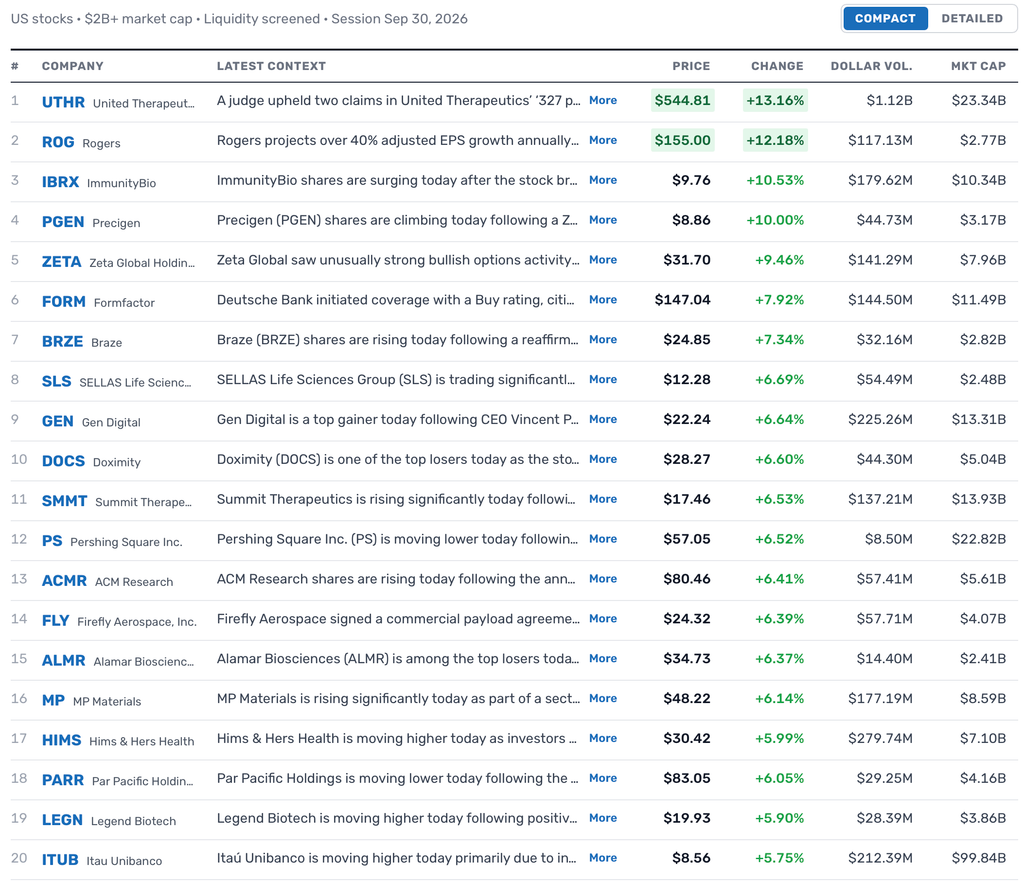
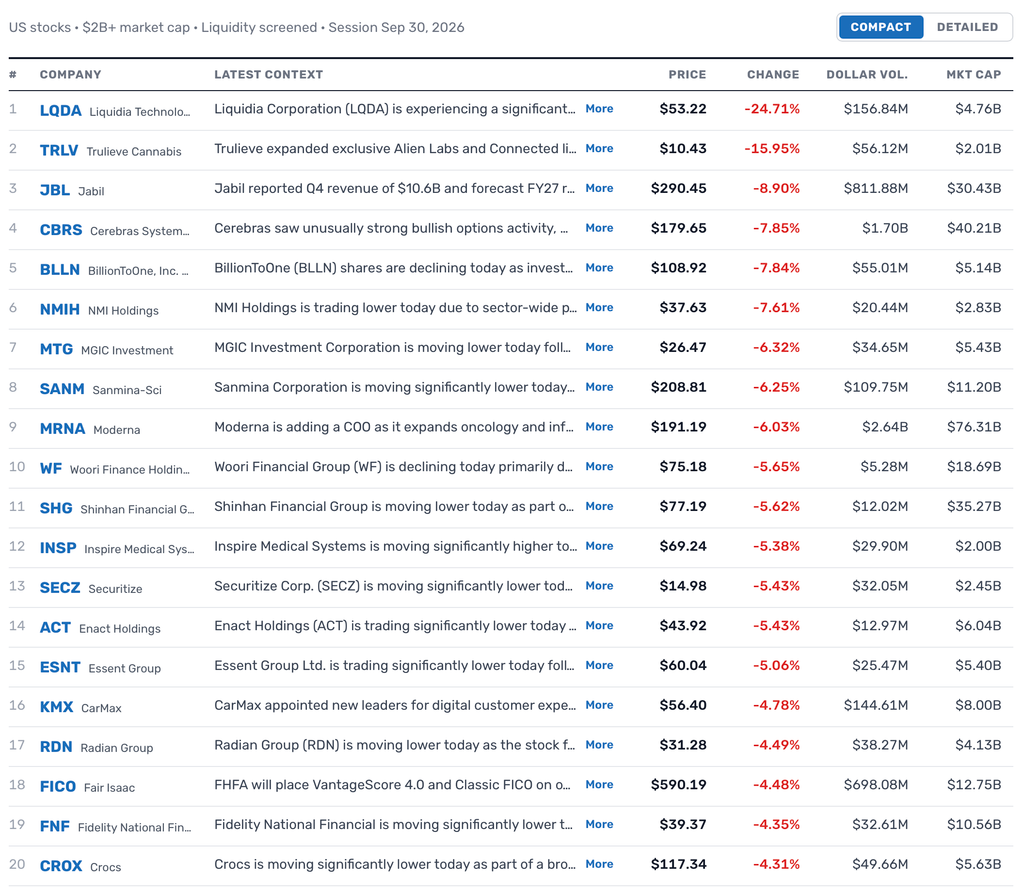
SOURCE TheFly
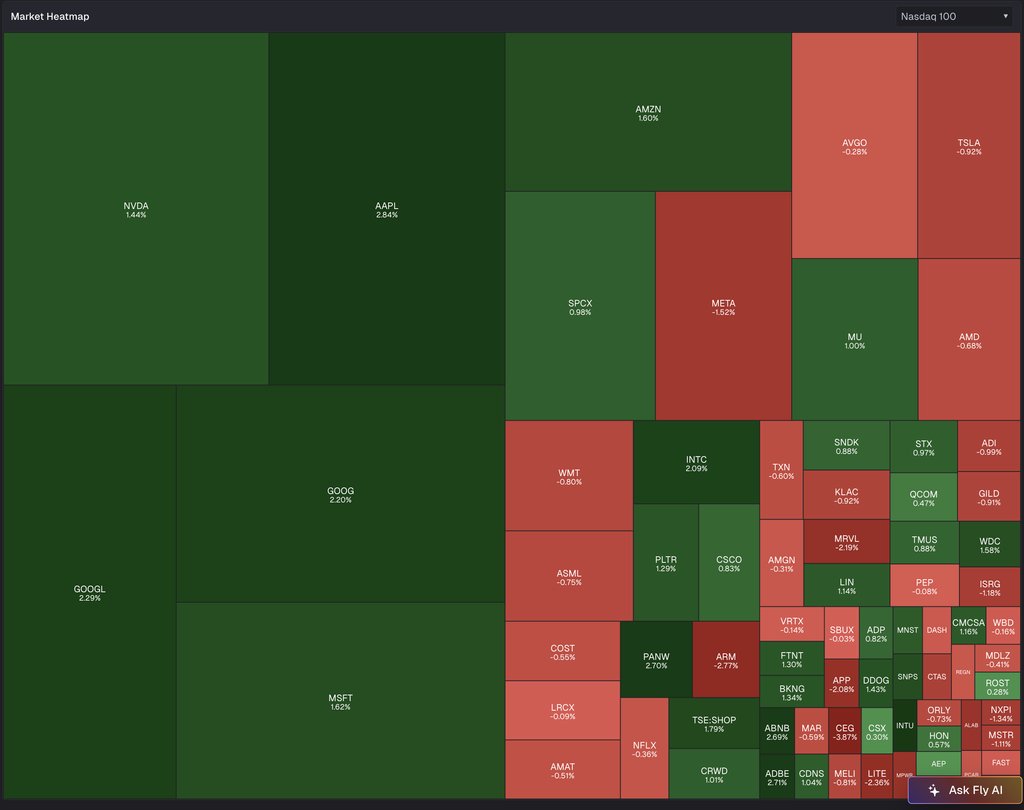
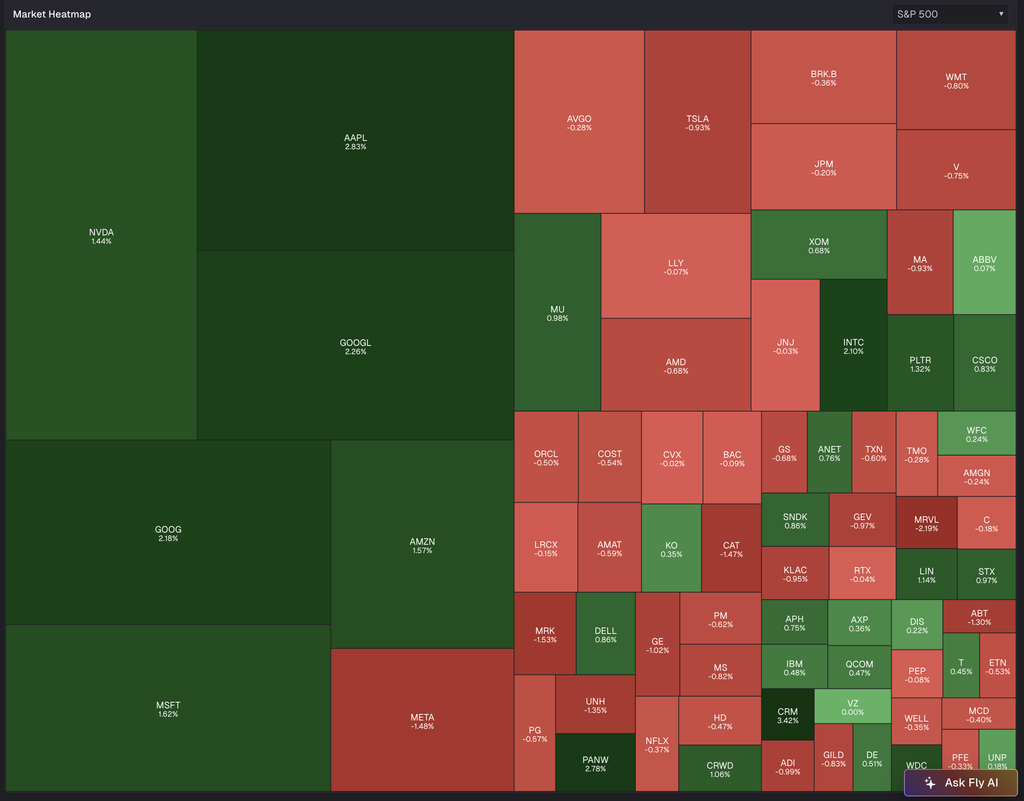
The all-time leaders in the playoffs of pitchers striking out 10 with no runs allowed:
Justin Verlander 3
Sandy Koufax 2
Randy Johnson 2
Cam Schlittler 2
Positions: None
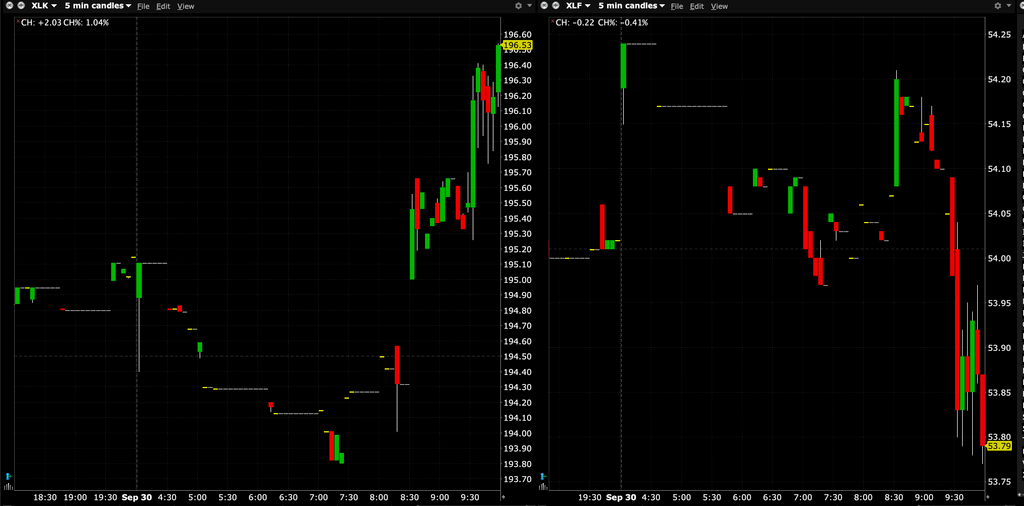
Chart from 10 a.m. ET
The following is from Peter Boockvar:
I think the John Williams comments, the president of the NY Fed, yesterday really matters and assuming no data surprises from now until the October 28th meeting, I don’t think they raise rates again at that gathering, especially right before the midterm elections. If they do hike again by year end, it would be more likely December. The 2 yr yield is down 6 bps since he spoke, and this is what it responded to from him, “With the policy action we took at our September meeting, there is no need for urgency, and we have time to gather more information.” Certainly doesn’t sound like a guy who is for a rapid rate hike cycle.
But he still kept another rate increase on the table by saying “If the economy evolves in a manner broadly consistent with my forecast, one further upward adjustment of the federal funds target range may be appropriate late this year to support a timelier return of inflation to target.”
I’ll argue again that the market is already doing the Fed’s work, among reacting to other things too, and it is not all on the Fed here to respond. A rate tweaking cycle we are under I’ll say again, I believe. And this is what Kevin Warsh wants and told us so, he wants to give room for the market to express itself, and it certaintly is doing so.
The most interest rate sensitive sector in the economy we know is housing. The MBA said the average 30 yr mortgage rate rose to 7.3% from 7.12% in the week before and vs 6.79% one month ago. In response, purchase applications fell 4.3% w/o/w and down 14% y/o/y. Refi’s were lower for a 6th straight week, down 8.7% w/o/w and by 56% y/o/y. I guess no surprise, however difficult the current rate environment is for the housing industry which remains hugely challenged.
These were earnings call comments of note from CarMax in the other highly interest rate sensitive business of selling used cars. With a relatively new CEO, there is some self help here that drove the stock up almost 5% yesterday.
“Used unit comps grew 13%, driven largely by improved price competitiveness.”
Still, the average selling price was up 6.3% y/o/y.
With respect to its CarMax Auto Finance business, “The observed credit performance in this space continues to be in line with our original expectations.” They did though see a reduction in Tier 1 lending (those with the best credit) as “Increased funding costs driven by the interest rate environment resulted in CAF increasing rates in Tier 1 where customers have more funding alternatives, including cash or financing through credit unions. We view this as a normal response to the higher interest rate environment versus a structural change in behavior from CarMax customers.” They saw continued growth in Tier 2 lending.
On their consumer, “affordability is on everyone’s mind. If you look at every single discussion around that…and our focus on having incredibly competitive pricing. And the other word I would say about the consumer is resilient, at the end of the day. Across all the different spectrums, at the lower end consumer to the higher end consumer, we’re definitely seeing resiliency there. I mean, the broader industry is down 1% or flat to 1%, and we posted comps at 13%. So I think having great cars, great vehicles, at great pricing and making it easy to work with will drive continued growth and performance in the business.”
Carnival had a good quarter as cruising continues to be the travel of choice for some. Its stock rallied by 13.4% yesterday. From them:
“The improvement in booking trends we highlighted on our last call continued to build throughout the quarter, with better close-in demand translating into higher revenues. That momentum also enabled us to raise our yield expectations for the fourth quarter.”
They don’t hedge their fuel costs but seemingly managed the cost increases well “as our teams continued to find ways to use less.”
With guidance, “For full year 2027, we are already half booked, with both occupancy and pricing at record levels. Bookings taken over our third quarter solidified this position, as we saw very healthy increases compared to last year’s levels.”
“Demand remains broad-based, including very healthy demand for our peak summer European deployments. 2028 is also off to an excellent start at higher occupancy and even higher prices y/o/y. And our booking curve is further out than it has ever been at this point in the year.”
Shifting gears to the overseas data. The August 3.6% gain in Australia’s trimmed mean CPI validated the rate hike seen yesterday to 4.6% by the RBA.
China’s more private sector weighted PMI improved in September with manufacturing at 52.1 from 51.5 and services up a touch to 51.6 from 51.4. With the former, Rating Dog said “Growth in manufacturing production accelerated amid rising demand from both domestic and overseas customers.” And, “rising cost pressures led to a renewed increase in output prices in September.”
Helping services was a lift in new orders “supported by successful business development efforts among firms and a broad improvement in demand conditions. The survey data also pointed to stronger external demand, as growth of new export business accelerated for the first time in 3 months.”
Separate from this data, China took a step yesterday to improve the demand for housing with the announced subsidies for mortgage payments. I think ending the decline in home prices is crucial to stabilizing household wealth and consumer spending.
On the heels of seeing yesterday’s higher than expected Spanish CPI for September, France today said its headline CPI rose 3.4% y/o/y, up from 2.6% in August and 2 tenths above the estimate. They also said that in August, PPI was higher by 4.8% y/o/y. Italy’s CPI was higher by 4.1% y/o/y vs 3.2% last month and above the forecast of 3.7%.
Expect more ECB rate increases as their deposit rate is still at only 2.5%.