Once Again…

I am again re-engaging on the short side of $JOET and $GRNY.
I continue to expand my short $SPY on a scale on market strength.
Position: Short JOET (S), GRNY (S), SPY common (VS), calls (M) puts (S)
I am again re-engaging on the short side of $JOET and $GRNY.
I continue to expand my short $SPY on a scale on market strength.
Position: Short JOET (S), GRNY (S), SPY common (VS), calls (M) puts (S)
Professor Scott Galloway’s No Mercy No Malice... “One Ring To Rule Then All”
Position: None
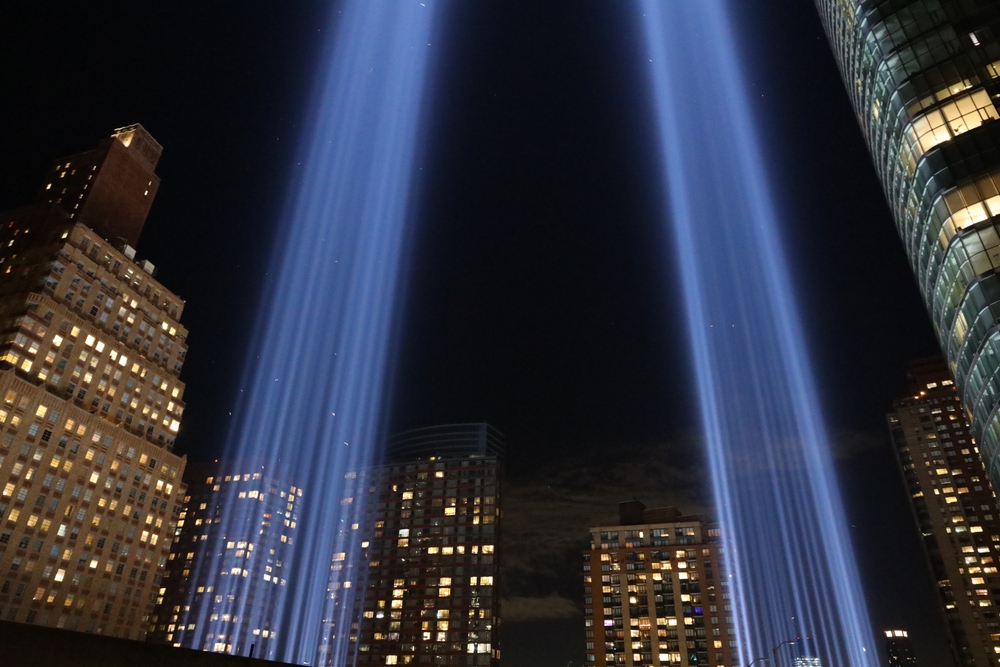
This column is dedicated to those who were lost twenty-five years ago — especially to my best pal, ‘Brown Bear.’
I received this email from Denny just now:
Dougie, of all the things written today concerning 9/11 yours was the finest and truly the most heartfelt!
Your old friend, Dennis
Position: None
Position: None
Volume
– NYSE volume 3% below its one-month average
– NASDAQ volume 19% below its one-month average
– VIX index: down 11.32% to 15.82
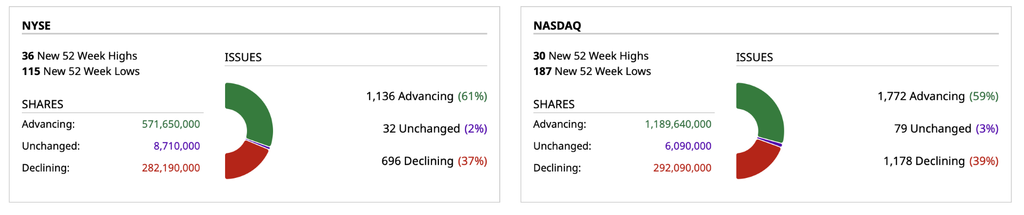
Breadth
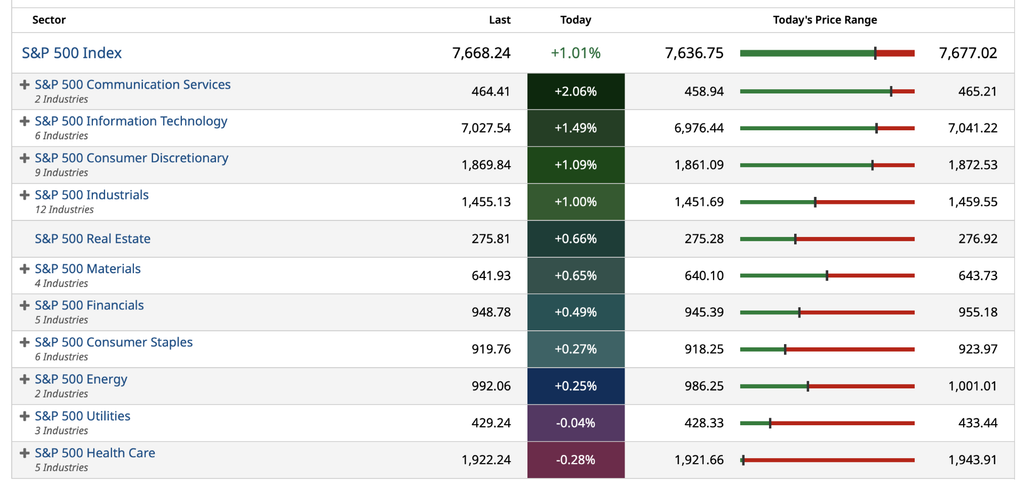
Sectors
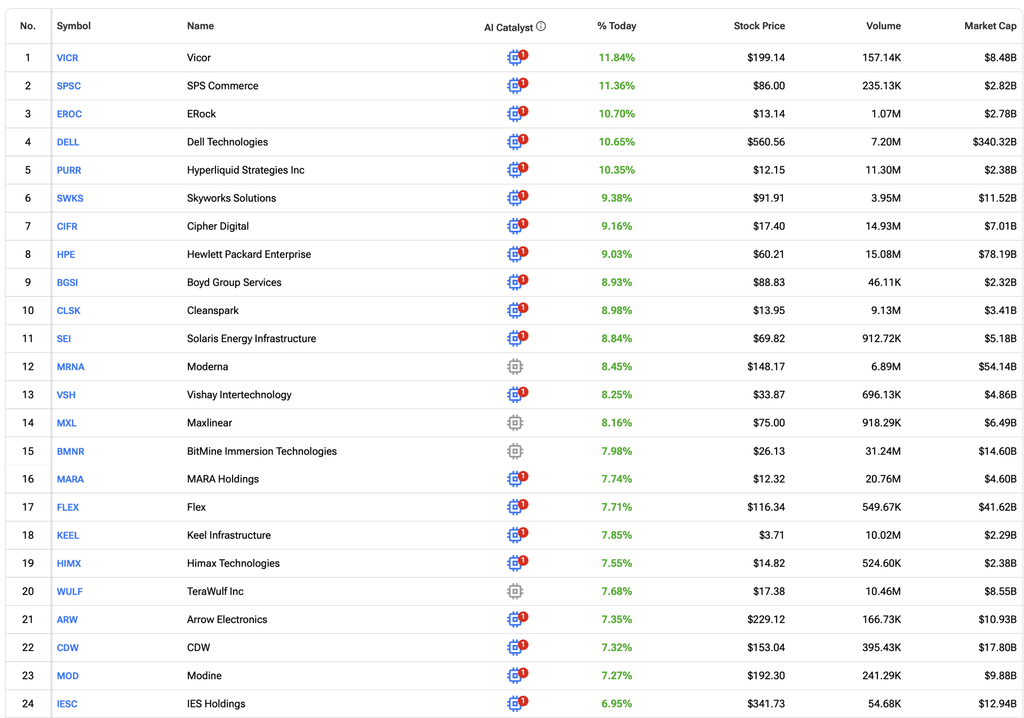
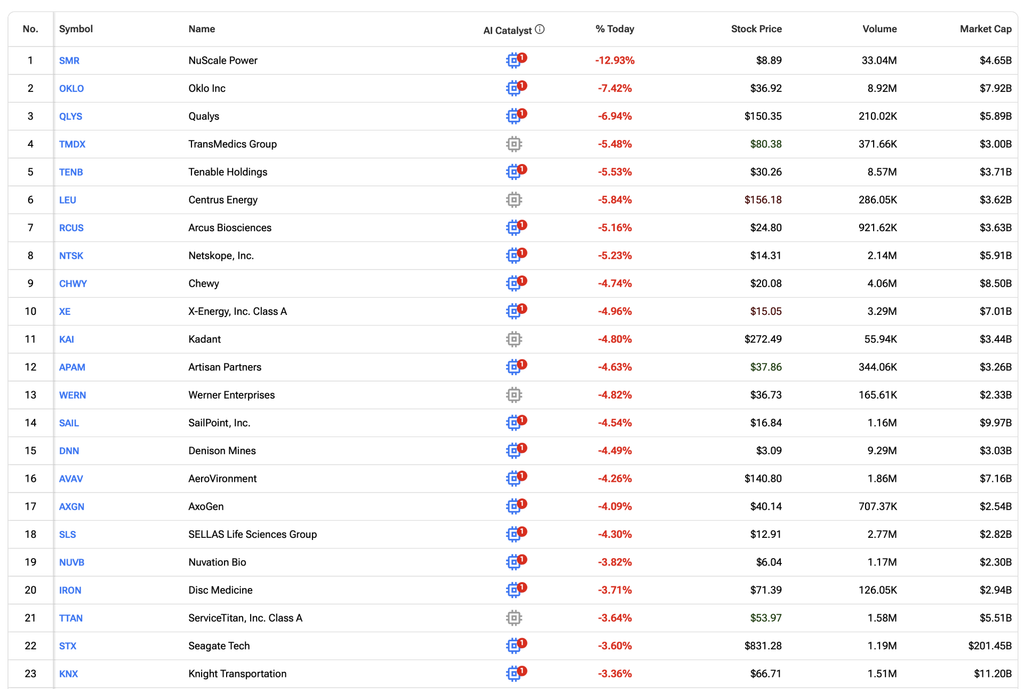
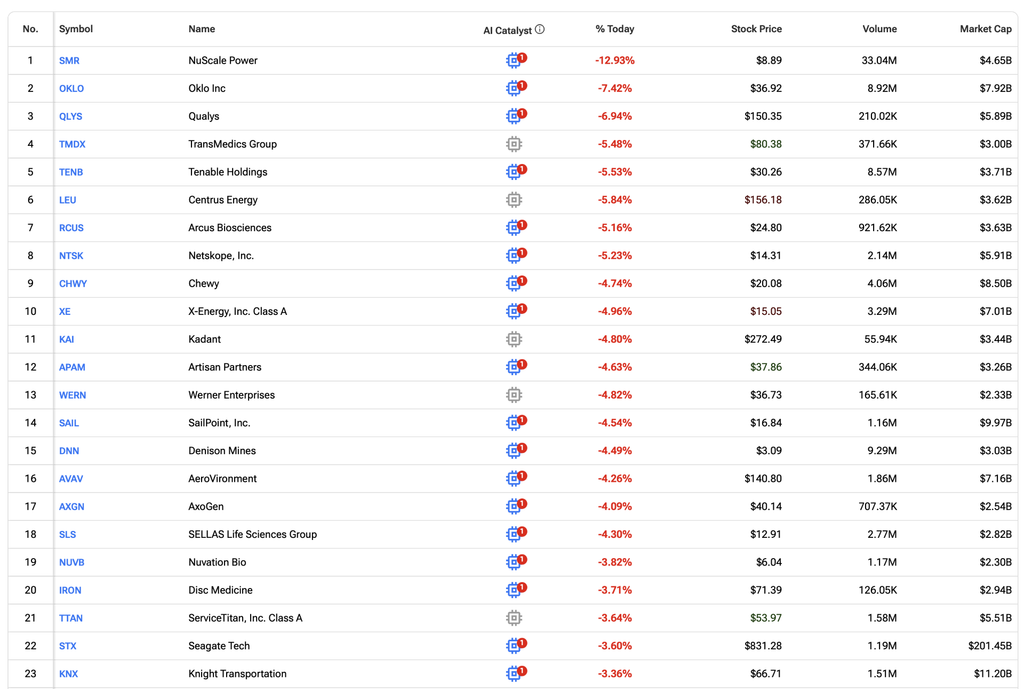
% Movers
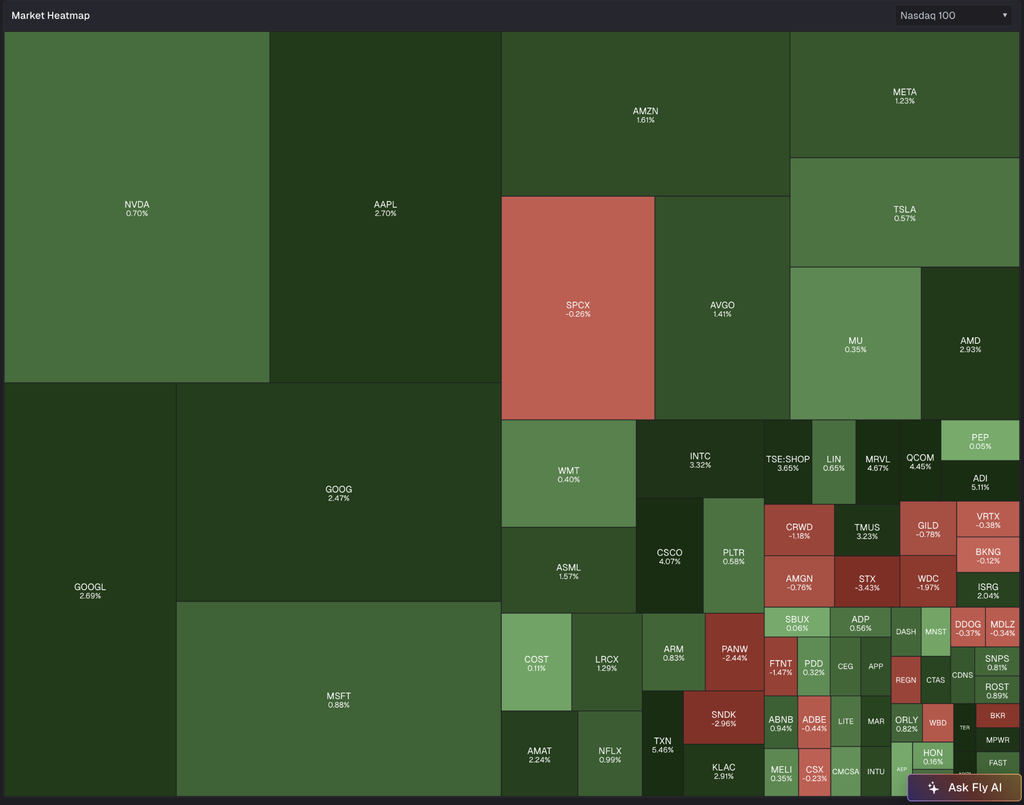
Nasdaq 100 Heat Map
S&P 500 Heat Map
Position: None
From Peter Boockvar:
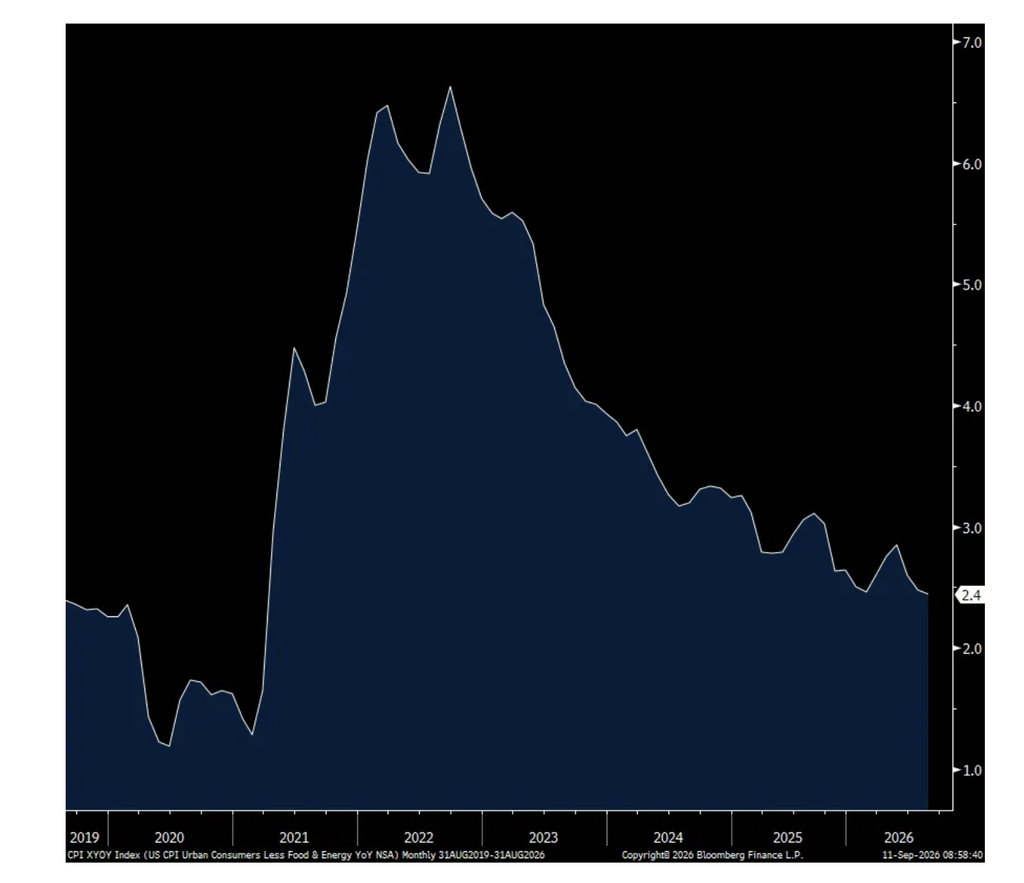
The August CPI rose .4% m/o/m headline and .3% core vs expectations of up .4% and .2% respectively. The y/o/y gains for each were 3.4% and 2.4% vs 3.4% and 2.5% in July and to remind us, compares with 5.4% headline and 4.6% with PPI seen yesterday.
Energy prices rebounded by 2.1% m/o/m after the two prior months of declines. They remain up by 16.3% y/o/y. Food prices were higher by one tenth m/o/m and 2.7% y/o/y with ‘food at home’ prices up by 2.2% and by 3.4% y/o/y for ‘food away from home.’ Specifically beef prices seem to be stabilizing but at high levels. I was at Bobby Van’s in NYC last night and never paid such a high price for a steak.
Services inflation ex energy, still the main driver of CPI, rose .3% m/o/m and 3% y/o/y. Owners’ Equivalent Rent, the biggest component, rose .2% m/o/m and 3.1% y/o/y. Rent of Primary Residence was up .2% m/o/m and 2.7% y/o/y. Both are more in line with the reality of national blended rental rates. After a .6% monthly gain in July, medical care services fell by .2%, though up 2.5% y/o/y. Health insurance is still badly reflecting reality, telling us that prices fell .5% m/o/m and by 8.5% y/o/y.
Airline fares continue to skyrocket, up another 2.7% m/o/m and by 23.4% y/o/y. Hotel prices jumped by 2.7% m/o/m and 2.9% y/o/y. Fixing a car cost 1.1% more vs July and by 5.2% y/o/y. On the other hand, car insurance continues to moderate after the post Covid spike. Prices here fell .8% m/o/m and by 5.1% y/o/y.
Core goods prices rose .1% m/o/m and .7% y/o/y. Vehicle prices bounced with new ones up by .3% m/o/m and .6% y/o/y while used car prices rose by .4% m/o/m but still down 2.3% y/o/y. Apparel prices were unchanged m/o/m but up 3.6% y/o/y. Furnishings and other household supplies saw no change in prices m/o/m and up .6% y/o/y. Medical care commodity prices fell .2% m/o/m and by 2.7% y/o/y driven lower by drug pricing.
Bottom line, if all we did was look at CPI, a core rate of 2.4% y/o/y would be comforting but knowing that what happens with higher energy prices doesn’t stay with just energy prices, we have to assume there will be spill over, particularly with this move higher in diesel prices. And I’ll repeat myself again, ignoring PPI in one’s inflation analysis I believe is a mistake and only tells one half the story.
Rate hike odds for next week now up to 86%. The 2 yr yield, after initially jumping post data release, is back to flat but higher by 10 bps over the past two days. The 10 yr yield is now down 2 bps vs 8:29am est after initial popping but still up 4 bps since right before PPI was released. The 30 yr yield is flat over the past two days.
I think it’s now a lock that the Fed will hike next week but still believe this should be considered a tweak more than anything. The rest of the curve has already adjusted the cost of capital much higher and will continue to do so if it feels necessary.
Headline CPI y/o/y
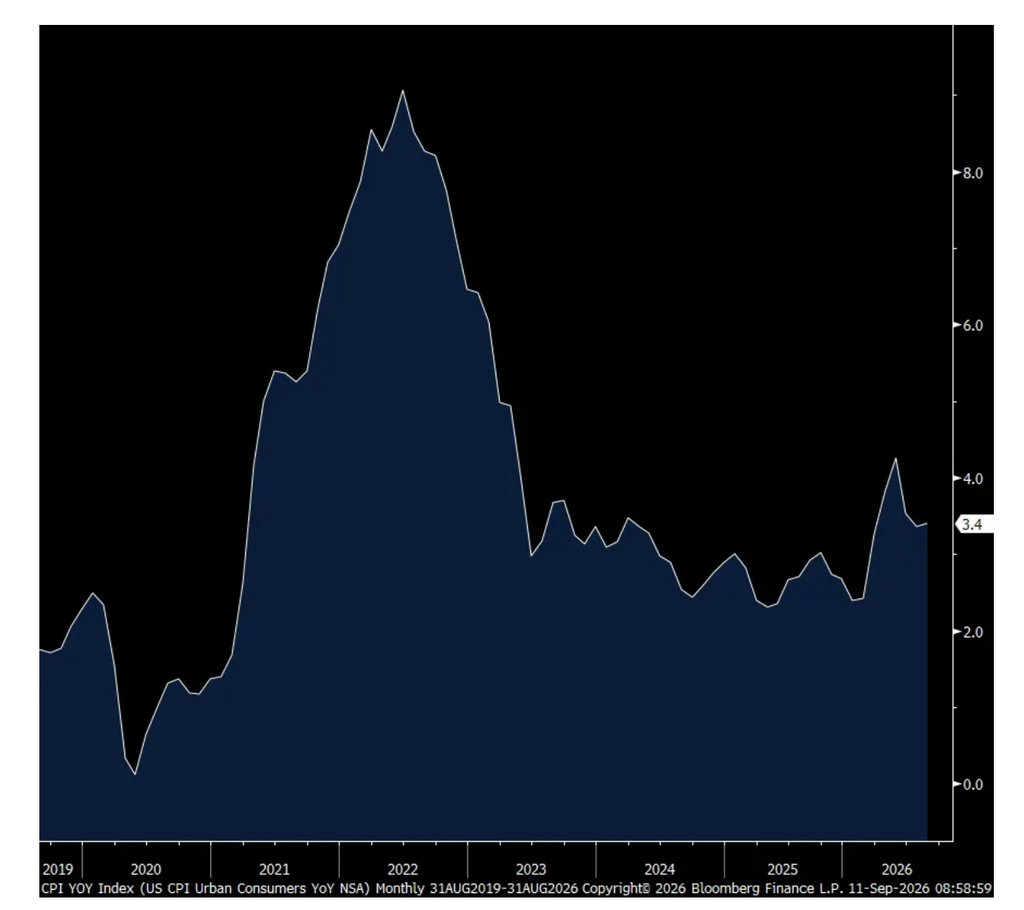
Core CPI y/o/y
Position: None
Here are today’s things:
* Shorted indices:
$SPY $765.03
$QQQ $716.23
* Added to short SPY calls (October monthlies)
* Added to $GLD at $398.84
* Added to $MSOS common at $4.85.
Position: Long MSOS common (VL), calls (S), GLD (S); Short SPY common (VS), calls (M), puts (S), QQQ common (VS)