More Tales From Nvidia: The Makes No Sense Edition! (Issue #255!)

This is an interesting tweet. 

Although it is AI specific with regard to OpenAI, I view it more broadly regarding the investment world these days. 

Open AI’s valuation should be going down, not up. The fundamental picture keeps getting worse.  The prior round valuations were grossly elevated to begin with. There is seemingly nothing but massive losses on the horizon. Executives are leaving in droves. They have all sorts of issues with the product, and its related risks. The CEO is a clown. The industry overall has real issues. 

We are likely looking at midterms where Democrats may gain some power (which I have stated can be viewed as a market headwind — more corporate and individual taxes, etc.), which will not be good for AI either. 

Yet no matter how much worse things look, they can somehow attempt to keep raising money at a higher valuation than the prior elevated round. 

One of their biggest investors (SoftBank) needs to keep borrowing money at elevated rates to keep funding them. It is almost as though there is an expectation that because the prior round was done at X, the next round will be done at almost 2X. 

Who is doing this, and why?  It makes no sense. The fundamental answer is the next round of financing should be done in bankruptcy court, in my view. 

Anthropic is no different with regard to how the IPO is theoretically being priced and how their business is valued. The equity markets in total seem no different now. 

It really makes no sense. It is almost like there is some sort of magical force elevating everything. I have never seen anything like this. 

Position: None
Another Marijuana Moment

As I mentioned late yesterday afternoon, the stay is procedural and I fully expect rescheduling to occur:

DEA Judge Pauses Marijuana Rescheduling Hearing As Opponents Highlight Government Report Detailing ‘Gaps’ In Federal Processes – Marijuana Moment

According to another source, President Trump is growing impatient about the slow pace of rescheduling progress:

President Trump ‘Not Happy’ With Marijuana Rescheduling Delays, Plans to Contact Attorney General and DEA Chief, Senior Adviser Says

Position: Long MSOS common (VL) and calls (M)

Tuesday’s Closing Market Stats

Closing Volume

– NYSE volume 1% above its one-month average 

– NASDAQ volume 12% below its one-month average 

– VIX index: down 0.50% to 15.99

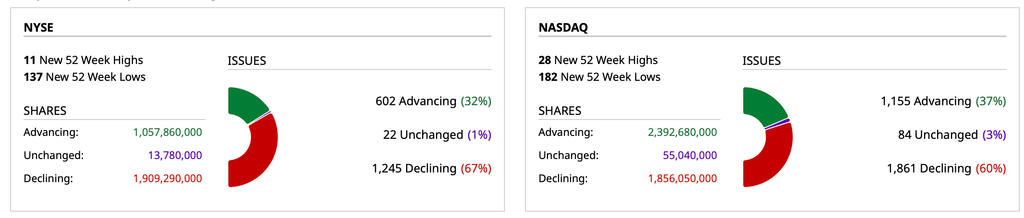
Breadth

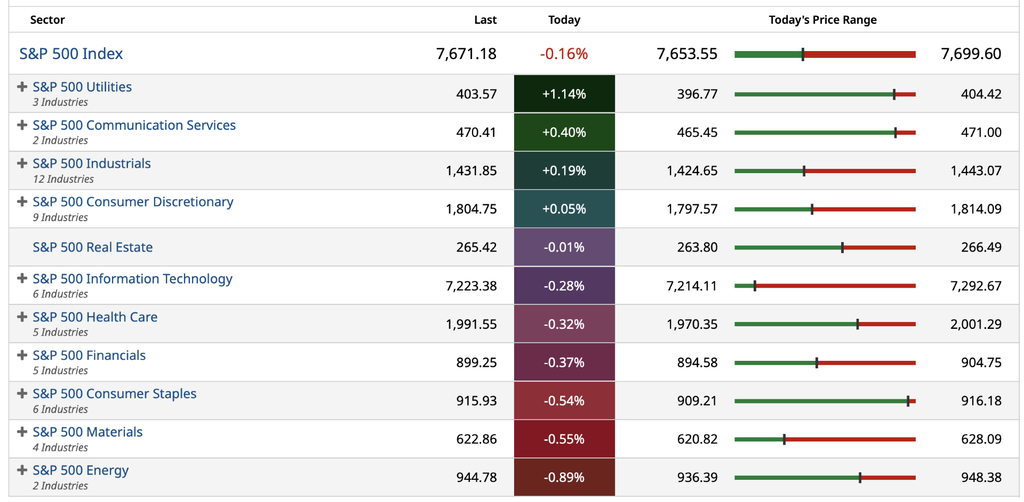
S&P 500 Sectors

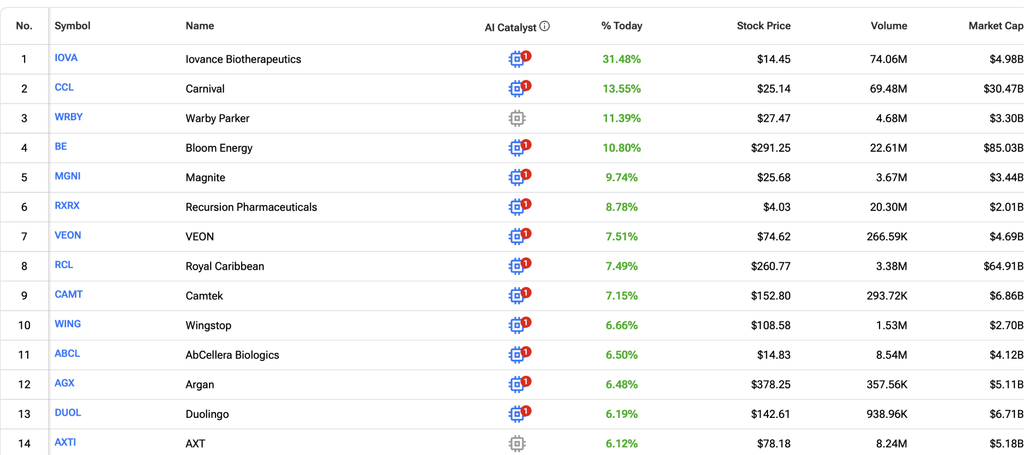
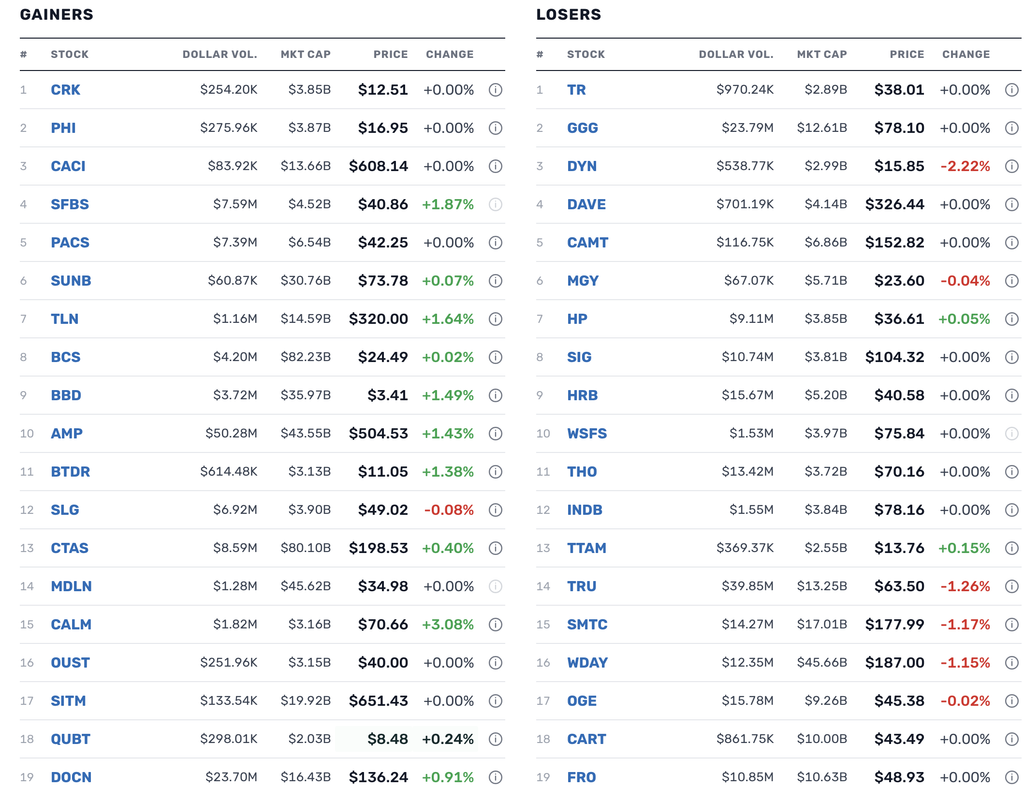
% Movers

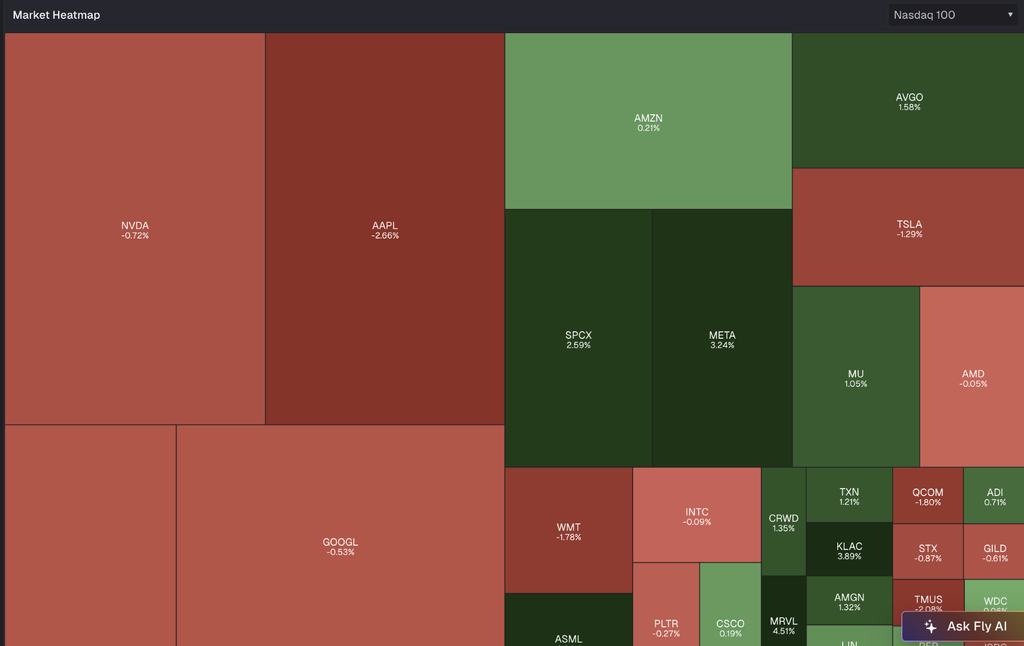
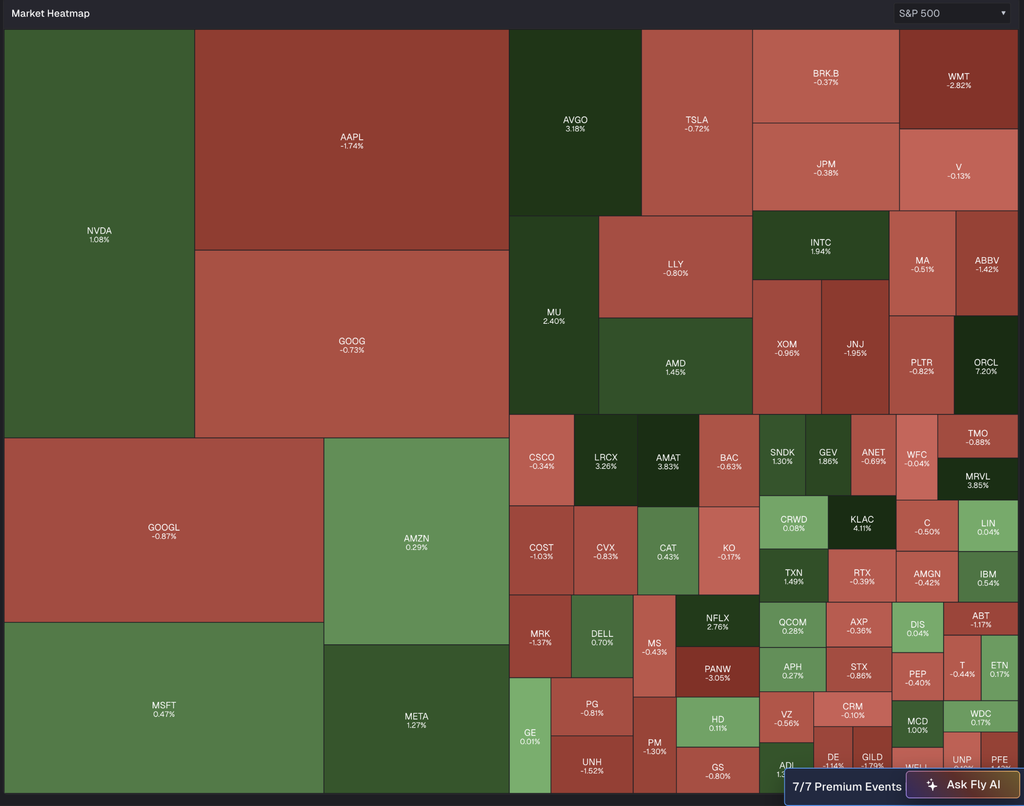
Heat Maps

Position: None

Boockvar on Consumer Confidence

From Peter Boockvar:

Consumer confidence sour/Job openings slip

The September consumer confidence index from the Conference Board fell to 81.9 from 88.6 and that was 7 pts below expectations. This is a level last seen in 2014 but when it was still accelerating post GFC. The Present Situation declined by 8 pts and the Expectations component was lower by 6 pts. A major factor in this decline, one year inflation expectations rose to 6.1% from 5.8%.

Also negatively impacting the mood, there was softness in the labor market questions. Those who think jobs are Plentiful fell to the least since 2016 not including Covid. Jobs Hard to Get rose 1.6 pts to the highest since 2016, also not considering Covid. When looking out to the coming six months, those expecting ‘more jobs’ fell almost one point to the lowest since April 2025. Expectations for income growth also weakened.

Spending intentions were down for the big tickets items such as vehicles and homes. They were mostly lower too for major appliances. Spending on services declined too. The Conference Board said, “The top five planned services spending categories were: restaurants/bars/take-out, streaming/internet/mobile services, beauty and personal care, utilities, and healthcare. Beyond the top five, consumers preferred to spend on cheap thrills and necessities. Anticipated spending for many discretionary activities moderated, including hotels for personal travel, movies, airfare, andamusement parks. Household maintenance, financial services, and historical sites/museums saw minor increases in planned spending.“

I’ll leave the bottom line to the Conference Board and not surprisingly, “Consumers’ write-in responses regarding factors affecting the economy were mostly pessimistic in September. References to prices, the high cost of goods and services, and oil and gas prices in particular, rose to new heights, reflecting September’s surge in fuel costs. Comments about war/conflict eased this month but remained elevated. Consumers also frequently cited politics, trade, and employment in their write-in responses, though to a lesser extent.”

Reflecting those expectations for less jobs available, August job openings shrunk to 7.079mm from 7.335mm in the month before. It was just below 7mm in March but above 7.5mm in April.

The hiring rate was 3.3%, up from 3.2% in July and vs 3.4% in June and 3.3% in May, hovering around the lowest since the early 2010’s. The quit rate was unchanged at 1.9%.

In terms of industry, what stood out was the lift in job openings for ‘information’ jobs, I’m sure AI related. On the flip side, there was a five month low in job openings for ‘professional/business services’. There was a gain in the demand for retail workers and finance/insurance but a drop in real estate/rental/leasing.

Bottom line, while the firing rate remains low, the hiring side is more selective as a variety of companies figure out how best to protect margins from the cost pressures many are facing.

Position: None

No Trades

No trades this afternoon.

Three research calls.

Positions: None.