Boockvar on Nvidia, AI Buildout, China Retail

The following is from Peter Boockvar:
Just a few things of note
While the fate of the next leadership team of Nvidia and how this all turns out is a really big deal both for itself and its massive contribution to the AI data center buildout, it still remains Anthropic and OpenAI that are at the center of everything as it is their model development that is the genesis of GenAI LLM’s and the massive CapEx and ecosystem it has created.
While trying to affix a valuation on such a fast growing but not yet profitable business is difficult, I think a key investor debate for Anthropic should be the complexion of its revenue stream. About 85% is due to token usage rather than subscriptions with the former much more variable and volatile relative to the latter. For now, I only hear about its incredible top-line growth, which is impressive for sure, though has slowed quarter over quarter, but not much about the makeup of what’s driving the revenue.
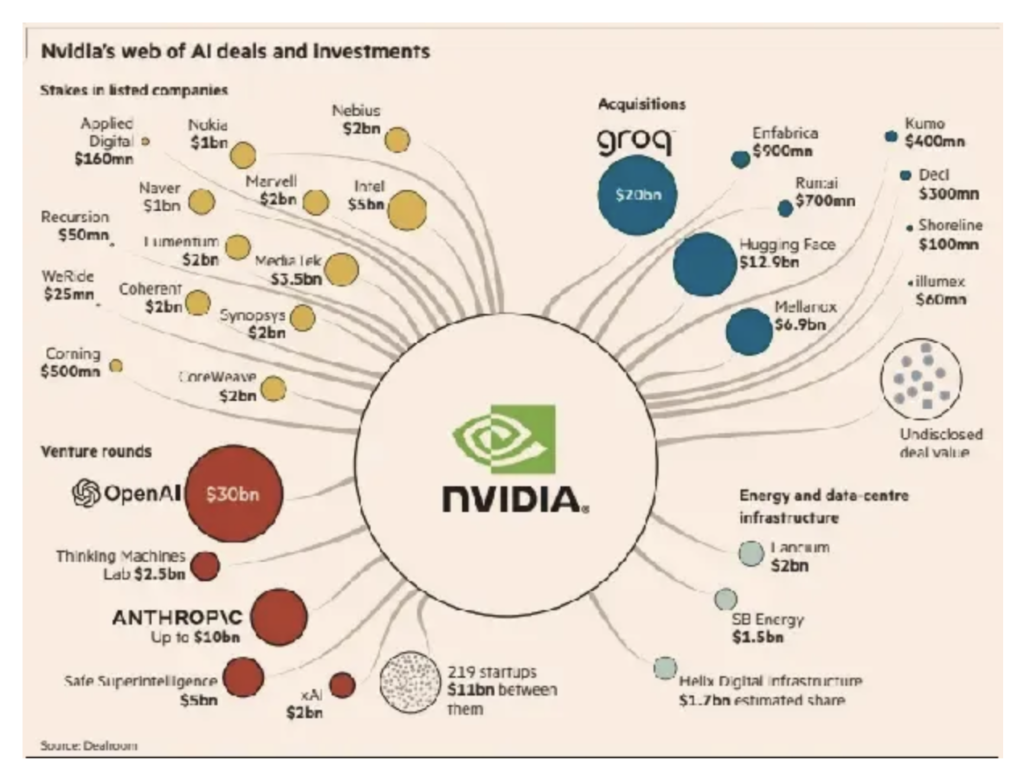
With respect to Nvidia, the Weekend FT had a great chart of all its equity investments and M&A activity:
I’ve expressed our long and positive stance on some consumer staples stocks like Kimberly Clark, Kraft Heinz, Nestle, McCormick, Conagra, and IFF and I do think that regardless of how the AI tech trade unfolds from here, there is nothing wrong with some boring in one’s portfolio.
To a few economic data points of note overseas. Japan’s economy grew 1.1% y/o/y in Q3 and declined by .1% q/o/q annualized. If we include the Q2 upward revision, the data was as expected. Just as it is in the US, non-residential investment is the strongest piece of their economy due to all the AI picks and shovels spend going on there and which is powering exports of high-tech stuff to the rest of us. With respect to consumption, that was soft but the BoJ said it had been weak due to “weather conditions such as typhoons, torrential rains, and prolonged rainfall.”
No real market response to data that is already a month and a half old. Expectations of a BoJ rate hike next week still looks elevated and its swaps market stands at an 84% chance.
In China, retail sales remain soft and I still directly tie it to continued weakness in residential home prices. Retail sales were up .4% y/o/y, half the estimate as home prices, both new and existing, fell again m/o/m. New home prices continue to rise for the top tier cities of Shanghai, Guangzhou and Shenzhen but fell again in Beijing and in the second and third tier cities. Home prices broadly need to stop going down in order to stem the weakness in consumer spending, I believe.
Industrial production was still the area of strength but up 4.8% was below the forecast of up 5.3%. Property investment was down almost 22% ytd y/o/y with fixed asset investment soft too.
