Why I Am No Longer a Cassandra

* Expanding on my views presented last week
I don’t want to bury the lede: I am returning to the land of the living, as on Thursday I pivoted and have begun to accumulate selected equities, as I said at the time.
Yes, I have had an ursine market view — for several years now. My concerns, written almost daily in my Diary, were multiple, and I’ll repeat them here:
* The rising prospects for “slugfation” (sluggish economic growth and sticky inflation)
* The lack of fiscal discipline on the part of both the Republicans and Democrats) in Washington, DC.
* Interest rates will likely be higher for longer
* Improvisational foreign policy that had potential adverse social, interest rate and economic ramifications
* The AI trade has been the straw that stirs the drink” of the U.S. economy, corporate profits and the U.S. stock market – we saw a wide range of concerns (including political objections to data center expansion) and have questioned the optimistic ROIC assumptions regarding the massive AI capital spending spree
* Investor optimism seemed extreme as valuations have been elevated – with most traditional valuation metrics in the 90%-tile or higher
* For years investors have increasingly acted as if they were at a casino (gambling/speculating and not investing) – as measured by the popularity and proliferation of leveraged ETFs and ODTE (zero days till expiration) options
* Market structure posed a potential risk should price momentum abruptly reverse
Though my arguments had merit (and most were generally proven accurate), the markets ignored my concerns.
While the price of the S&P Index has remained elevated, over the last several months there has been a stealth Bear Market which has accelerated dramatically over the last week. Since the early summer, many widely-held stocks technology stocks have fallen by 50% or more.
1. Consider for example, Dell Technologies’ ($DELL) shares which traded at $595 on Oct. 8 and, less than a month later Thursday, Nov. 5, I initiated a long position at $319.
2. We are finding plenty of emerging value opportunities outside of technology. As an example, we initiated a long in “best of class” Morgan Stanley also on Thursday at $181 compared to its share price of $235 less than four months ago.
3. We have other examples of developing that we will share in the future in my Diary.
No Longer a Cassandra
As repeatedly stated, my hedge fund is not a short or short-biased fund.
I recognize that I have sounded Cassandra-like in my bearish views but, as mentioned, many of my concerns were valid and on target. Specifically, interest rates rose rapidly (absolutely and relative to expectations), inflation was sticky economic growth was disappointing, improvisational policy led to an unwanted war and the efficacy and profitability of AI is now suspect.
We have often written that being long stocks can generate wealth and being short stocks (and/or having large cash reserves) can help to preserve capital.
Until recently, most stocks failed to meet our standards for investing. This is changing rapidly – as, on Thursday, the major Indices each fell by about 5%.
The concerns expressed above have largely been accepted by most investors and some have begun to be discounted (“second level thinking”) in an increasingly greater number of stocks.
Importantly, some of the major concerns (discussed above) are likely to moderate:
* While the cumulative or “stacked” inflation since 2021 remains problematic, we now see signposts (e.g. lower energy prices) that inflation will moderate relative to consensus expectations
* If inflation does retreat, the domestic economy (fueled by the consumer) may exhibit better growth than we previously expected
* Interest rates may have peaked for the cycle
* The current Administration’s potential improvisational policies are likely to be diluted by the stronger than expected showing of the Democratic Party in this week’s elections and the President’s “lame duck” status
* Tuesday’s Blue Wave likely means that the AI capital spending spree will probably be moderated – reducing our fears and smoothing the AI capital spending cycle (serving to reduce the chance of a boom-and-bust cycle)
* Equity valuations in a number of sectors (particularly technology) have declined considerably as “fear” and panic have replaced greed
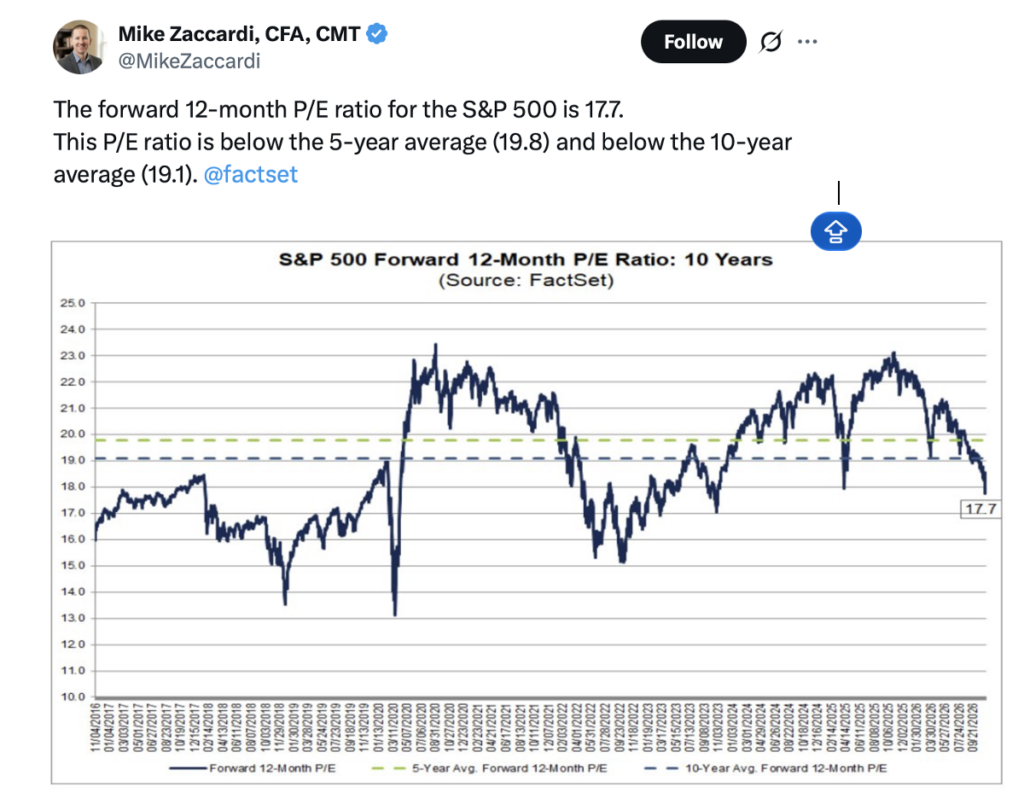
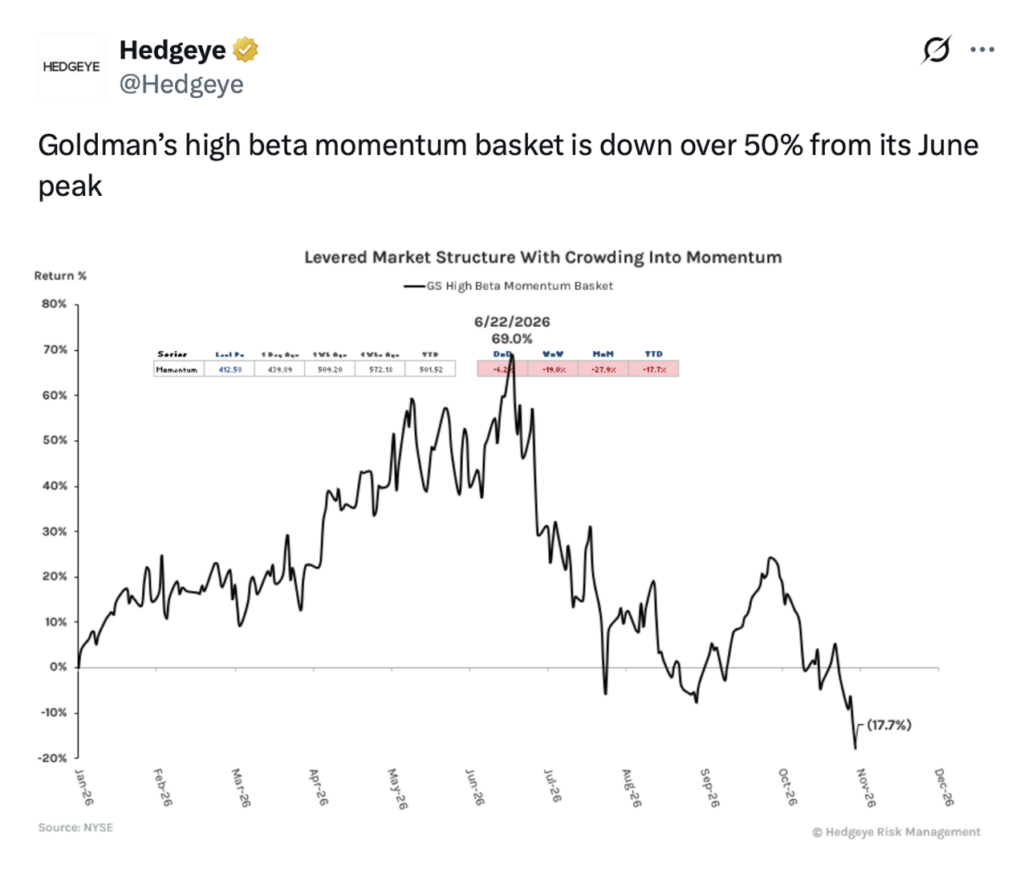
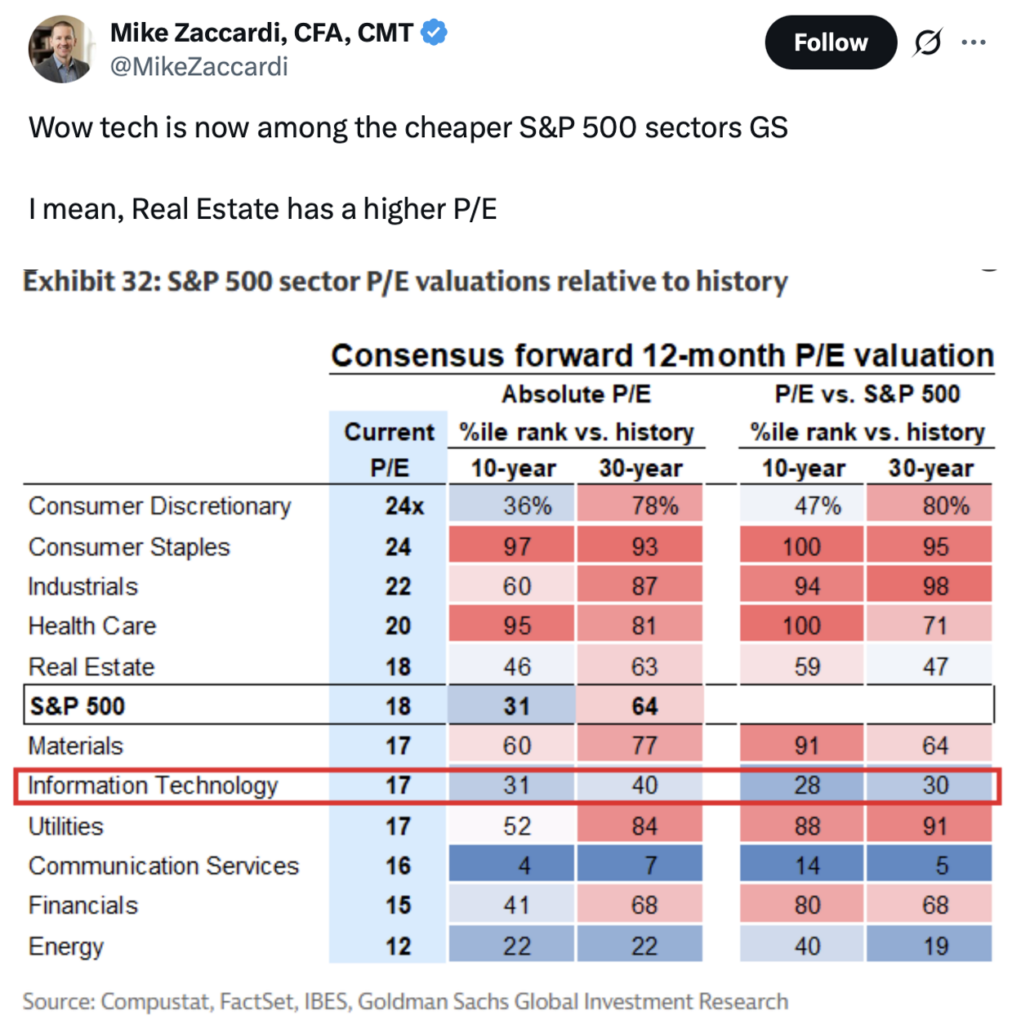
With the rise in “fear” and heavy (recent) trading and investment losses, there has been a diminished interest in ODTE call options and leveraged ETFs are suffering from outflows – moreover several large hedge funds have apparently been forced to liquidate (and have contributed to this week’s sharp market decline)
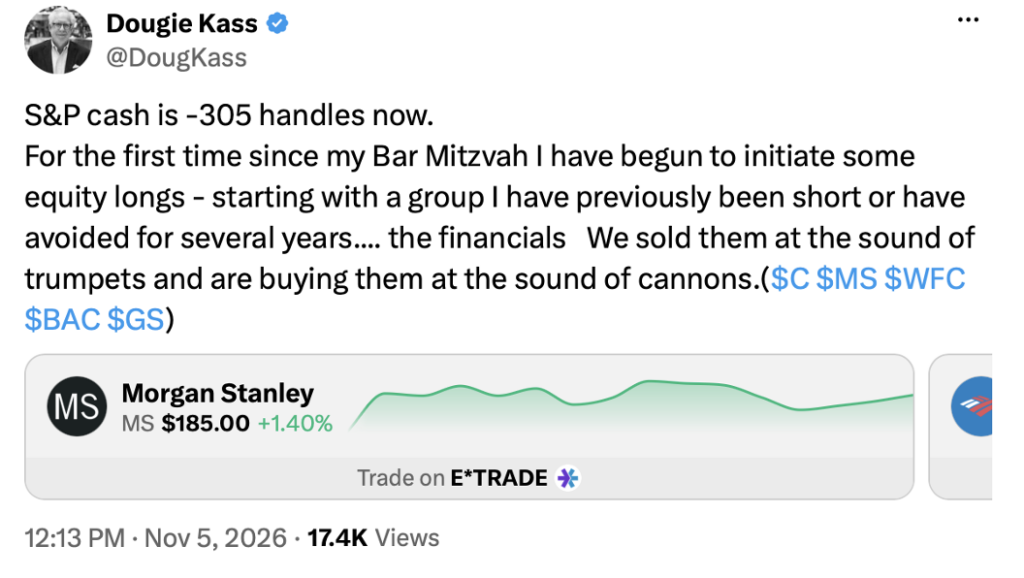
That is not to say I am wildly bullish – we are not.
However, as an expression of the increased investment opportunities that appear to be emerging, I have moved from a small net short exposure to a 10% net long exposure by Thursday’s close of trading.
Should the current decline in stocks accelerate I am likely to increase my invested position if the fundamentals and other factors continue to stabilize or improve.
Bottom Line
I welcome the chance to return to “the land of the living” and buying equities – with my current intention of buying and holding… and not trading.
To paraphrase Warren Buffett: It may be time to consider being greedy when others are panicking and are feeling fearful.
I now see emerging value in selected equities that have been decimated over the last 3-4 months.
Positions: Long DELL S MS M
