Boockvar on NEXTDC … Huh? … Japan Exports, French Bonds

The following is from Peter Boockvar:
I never heard of them either/Other notable stuff
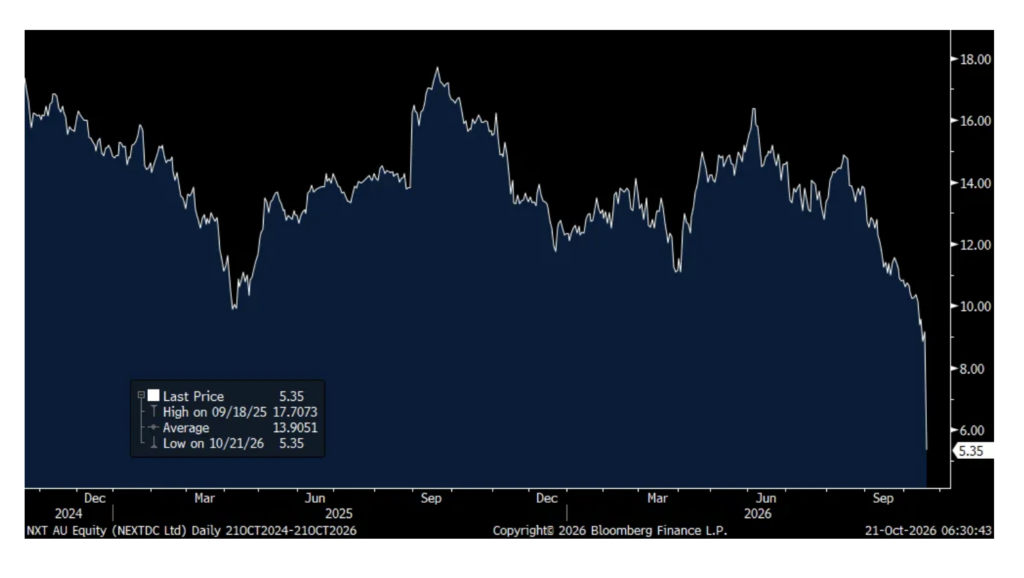
Every hear of NEXTDC Ltd based in Brisbane, Australia? I didn’t until today but it develops data centers and its stock plunged by 42% overnight. They preannounced negatively and said this on their call as for why. “The main reason is M3 Melbourne. The timing of power to that site is no longer certain and I’ll explain why…Jemena in Victoria is the distributor that supplies power to M3. Jemena suspended parts of network works that deliver the next step up in grid supply to the site. Jemena has attributed the suspension to community and stakeholder opposition to the works. And to the local council not giving its consent until more community consultation takes place on the program for installation of poles and wires. Jemena told us formally they don’t expect to restart before February next year.”
M3 Melbourne is defined by the company as a “225MW Tier IV certified data center engineered as a new digital gateway for Victoria…Purpose built for hyperscale growth and high-density compute, M3 Melbourne spans more than 41,000 m2 of technical space.”
I guess the bottom line here, along with the Firmus and AirTrunk IPO postponements, the Coreweave financial concerns, the disastrous Elice IPO and Volta, the UK data center company having to raise money recently at 11%, is that on one hand if there are less data centers that end up being built, less stuff that goes in them gets ordered. On the other hand, the ones that do get built maybe will be able to maintain some pricing power for longer on leasing out GPUs because at the end of the day, the price of technology products and services typically goes down and that will eventually be the case for the lease prices of GPUs. I don’t know when but they will if history is any guide.
NEXTDC
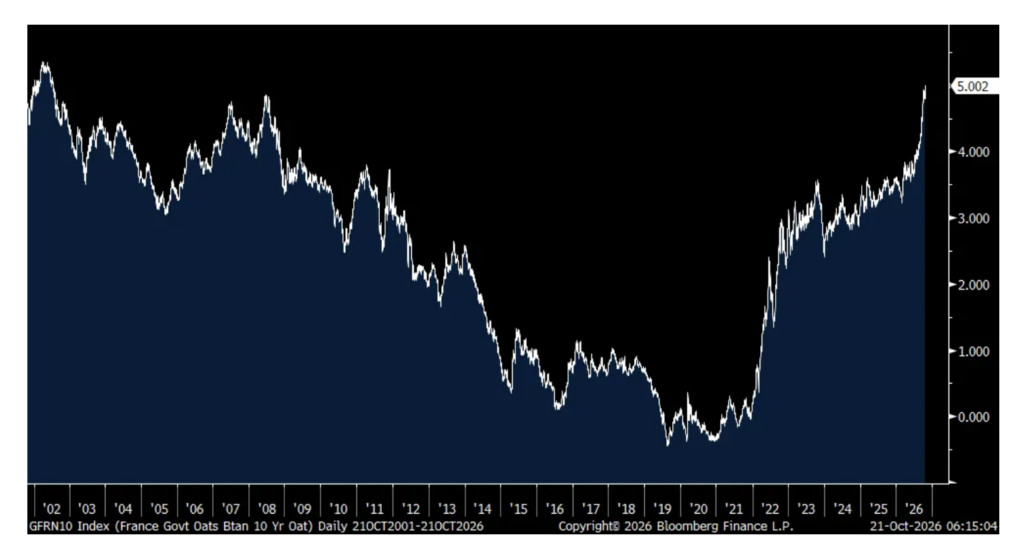
The French 10 yr bond yield is touching 5% for the first time since July 2002. I know everyone has their view on why rates are rising globally and I continue to say ‘all of the above.’ French yields are not rising because of robust growth, but because debts and deficits matter. What also matters is the behavior of foreigners in their market as they own about 50% of the French oat market and the Japanese in particular own about 7%. Japanese JGB yields, when including the cost of FX hedging, are looking more and more attractive to Japanese domestic investors and money is coming home.
French 10 yr Yield
Staying with the Japanese, they reported September export growth of 16.7% y/o/y but while solid it was below the estimate of 21.3%. Of course, the shipments of semiconductors and chip equipment led the way, higher by more than 40% for each. Auto exports were up by 15%. Exports to the US rose 23%, to the EU by 10.5% and to China by almost 9%. Imports were higher by 19%, just under what was forecasted.
Nothing market moving on this data though.
Yesterday we saw that in the UK, weekly earnings ex bonus rose 3.7% y/o/y in August. Today, September CPI in the UK is out and it rose 3.5% y/o/y with a core rate of 2.8%. Essentially running to stand still financially.
With respect to wholesale prices, PPI input prices were up by 8.3% y/o/y and output charges were higher by 4.6%. Quite the margin squeeze and another country that is seeing PPI well above CPI and I’ll say for the umpteenth time, one must look at both CPI and PPI in order to have a full picture on inflation.
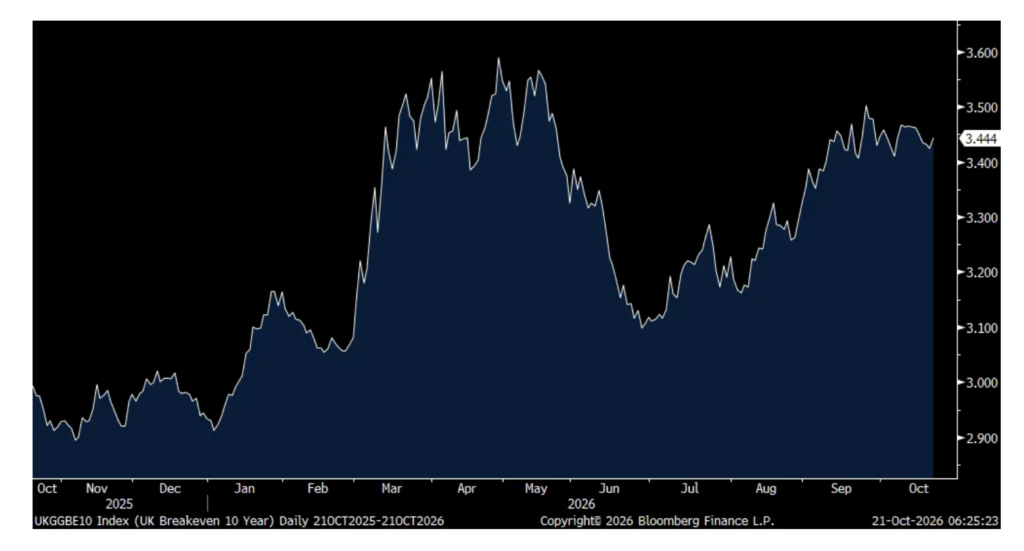
As the data was about in line, gilt yields are little changed and the 10 yr UK inflation breakeven is higher by 2 bps to 3.44% but remaining in a 3.4-3.5% range it’s been in over the past month.
UK Inflation Breakeven
In the US, the rise in interest rates is impacting commercial construction. The September Architecture Billings Index weakened to 44.7 from 47.2 with 50 being the breakeven. Commercial/industrial (which includes data centers) is the only category remaining above 50 while the other three, including multifamily, is below. The AIA said “This is an increasingly difficult environment for architecture firms. Weakening billings are being compounded by a soft economy, challenging project financing and growing caution among clients. With fewer projects moving forward, there is little reason to expect a meaningful improvement in business conditions in the near term.”
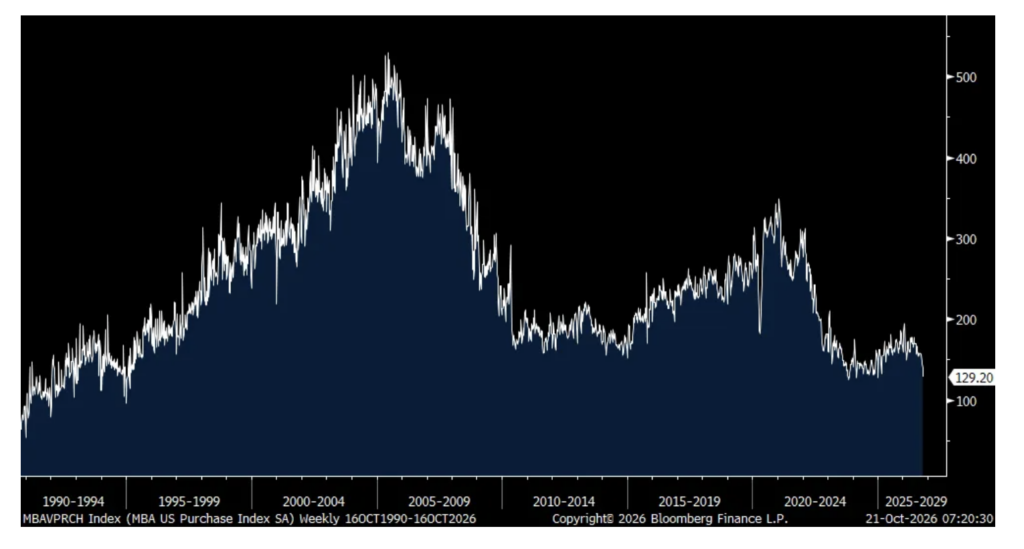
Higher mortgage rates continues to freeze the housing market. While the average rate of 7.41% was down 9 bps, the elevated level resulted in a 7.3% w/o/w drop in purchase applications and down 18% y/o/y. They now sit at the lowest since January 2025. Refi’s dropped for a 6th week, by 2% w/o/w and by 59% y/o/y.
Purchase Applications
To some earnings calls of note:
From MMM, up 6% yesterday:
“We continue to see strong momentum in general industrial and safety, with second half growth accelerating to high single digits, above our prior expectations. In electronics, we’re seeing increasing strength in semiconductors and data centers, which is partially offsetting a weaker consumer electronics market, especially in LCD displays. Auto OE and aftermarket are trending in line with prior expectations, with a modest improvement from down low single digits in the first half to about flat in the second, and with auto OE a bit softer and aftermarket a bit better.” Aerospace is doing well too.
And, “The consumer business, which contributes about 20% of sales, improved sequentially to about flat in the second half as modest improvement in consumer POS spending is partially offset by channel inventory adjustments at a few specific retailers.”
From GM, down 7% yesterday because of higher costs:
Revenue was up 3% y/o/y. “As this quarter’s results and our revised guidance show, our business is performing well, even with a major launch underway and the inflationary pressures we’re experiencing in areas like logistics, commodities and memory.”
They sold 670,000 vehicles in the quarter, of which 645,000 were internal combustion engine. They are still losing money on their EV business with not enough hybrid models out. And, “turning to our international operations, we expect continued ongoing softness in GM International, reflecting headwinds from the dynamic environment in the Middle East.”
“The US market remains resilient. We expect total SAR to be in the mid 16 million unit range for the full year, which implies approximately 16 million for the rest of the year, consistent with what we are seeing in October.” Perspective though, in 2019 we were seeing annualized vehicle sales of over 17mm.
Staying with the car business, from Ally Financial, up 1% yesterday:
Auto loan originations rose 10% y/o/y and “consumers have continued to demonstrate resilience as they navigate an evolving macro backdrop, and we remain encouraged by the performance we’re seeing across the portfolio.”
“Consolidated net charge-offs of 117 bps were up 6 bps sequentially due to seasonality and were roughly flat y/o/y.”
“Our coverage levels continue to balance stable credit trends across our portfolios against broader macroeconomic uncertainty. Consumers have continued to demonstrate resilience, but we monitor several factors, including persistent inflation, affordability pressures, elevated oil prices, and lower personal savings rates. It is important to note that our underwriting approach is not static.”
Of note, “While the portfolio is performing largely in line with our expectations, our late 2025 and early 2026 vintages are showing higher early life delinquency, which are being closely monitored.” I bolded to highlight.
From Capital One and whose stock is rising pre-market:
They lowered their reserves for bad debt by releasing $250 million of allowance in their domestic card business. “The allowance release was driven by continued favorable observed credit in the quarter, partially offset by greater consideration to downside economic scenarios related to geopolitical risks.”
Net charge-offs fell and “are benefiting from the steady improvement in delinquencies that we observed in the first half of this year and from strong recoveries’ performance.”
