More Tales From Nvidia: And Lessons of AI Burn From SpaceX (Issue #263!)

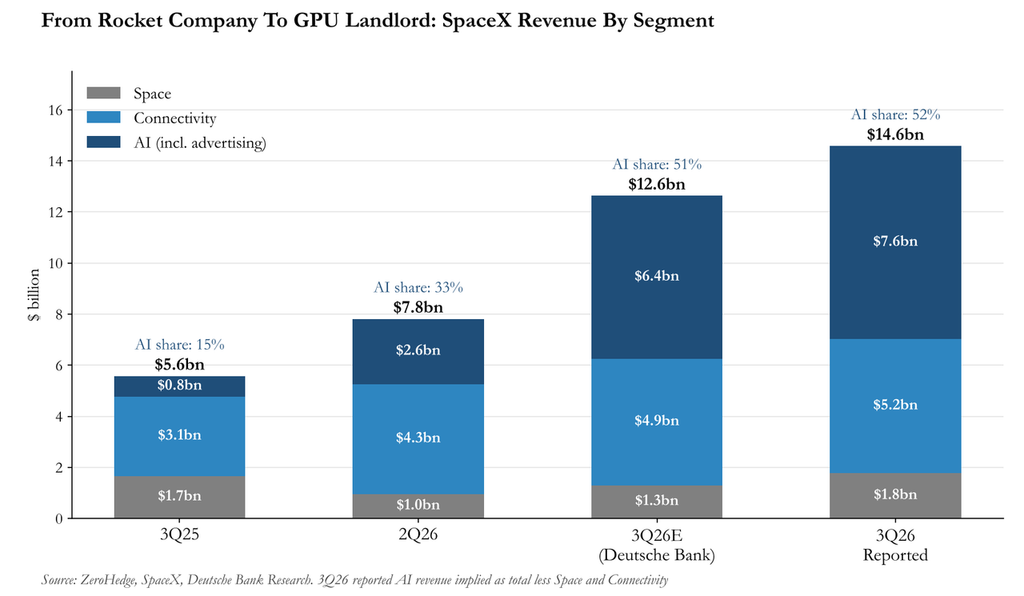
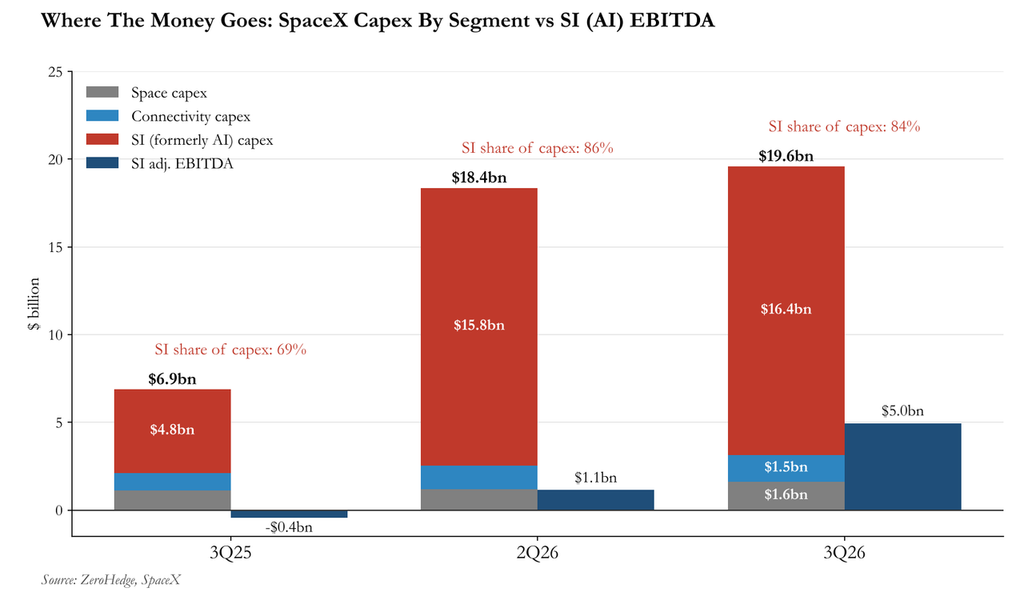
Below are two charts that speak volumes about the economics of AI.
SpaceX ($SPCX) just reported 3Q2026.
All of a sudden, AI (ergo data centers) is their biggest business. Along with that, cash and cash equivalents came in at $51.29 billion, versus an estimate of $91.2 billion. CAPEX for their AI segment was $16.4 billion versus $5 billion of EBITDA. Is this compelling?
I guess they can buy all the revenue they want; good thing the cost of financing it is so low??? Feels like double dilution is on the come here. Continued issuance to do whatever they are doing chasing WeWork landlord revenue, and dilution to potentially acquire Tesla ($TSLA), which is becoming more and more apparent.
Clearly Elon Musk wants to goose SPCX stock where he has much more of his net worth (~70%) to acquire TSLA (~25%) to hide it, on more favorable terms for SPCX (ergo himself).
This is the same trick Musk used when Tesla acquired Solar City. Hide the biz that can’t meet its promises, then to the next B.S. story.
Boy did that thing burn cash, holy heck, never seen a whiff this bad. Good thing borrowing costs are low these days. Oopsie:
In any case, at the rate AI is burning cash (and sucking down credit and equity), the 10-year Treasury will be yielding 6% in no time!
Position: None
