Boockvar on Bank of England, Sour Mood of Individual Investors

The following was provided by Peter Boockvar:
BoE provides some Gilt relief/The mood got sour for the individual investor/Pending home sales
The BoE today updated its approach to shrinking its balance sheet and the result today is a further drop in gilt yields with the 10 yr yield now down 8.5 bps. They will halt for the next 6 months its asset sales and this is what the new program will look like in reducing the size of its balance sheet thereafter:
1)About 222 pounds of gilts will naturally mature over the next 8 years.
2)They will halt the sale of the very long term paper they own, those with maturities longer than 2049 and these gilts will be kept on their balance sheet permanently to back its banknotes.
3)The balance will be sold and the overall pace of the sales/maturation of gilts in the market will be reduced to 46 billion per year, down from 70 billion.
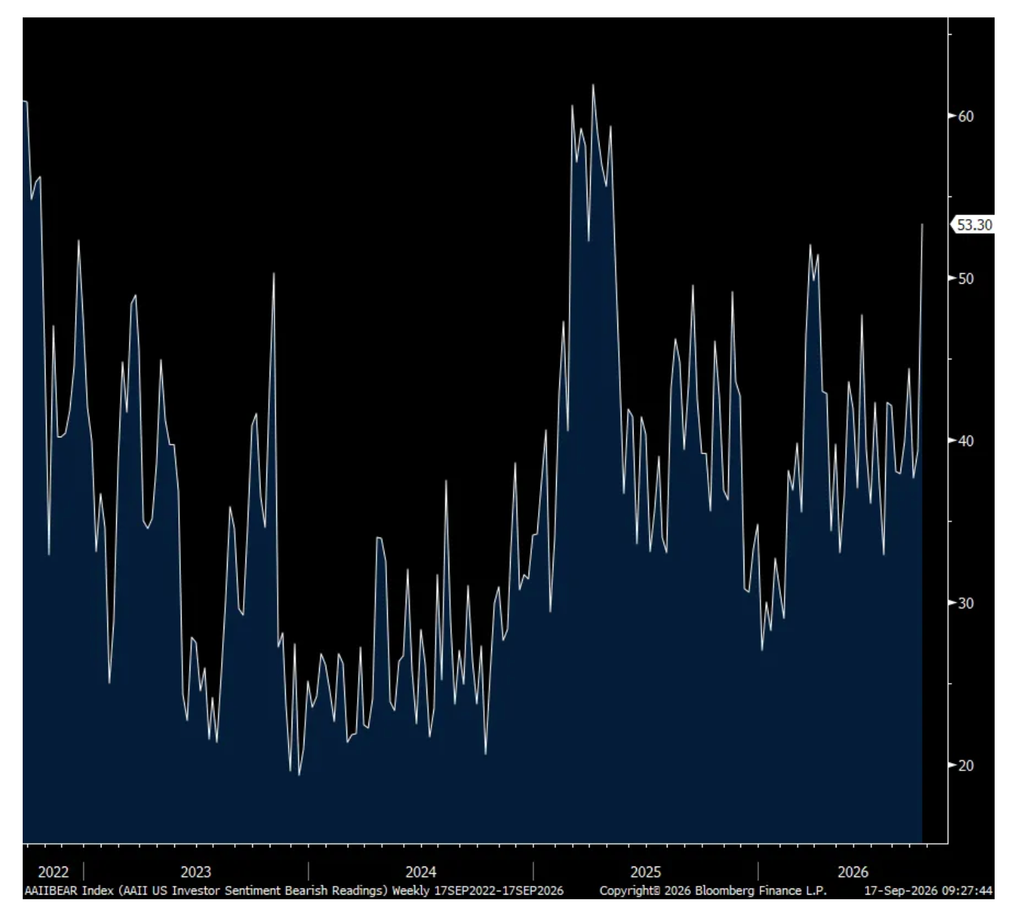
The AAII individual investor sentiment survey is my least favorite stock market measure of the mood as it tends to be much more fickle and its chart looks like something you’d see when you get a physical/EKG test. However, when it gets really extreme in one direction, it’s worth taking note and that was this case this week.
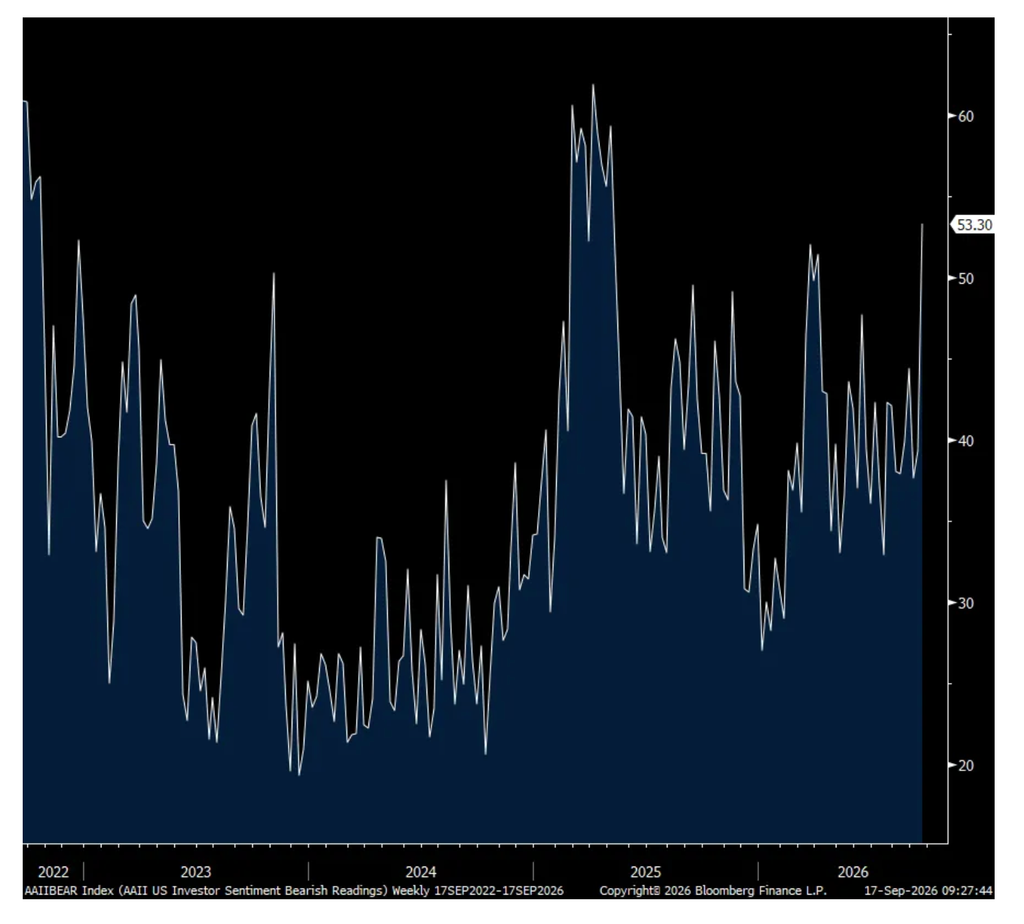
Bears jumped by 14 pts to 53.3 and that is the most since May 1st 2025 when the market was in the ‘Liberation Day’ downdraft. Bulls are the least since September 2025.
The II ‘professional’ investor survey still remains pretty bullish though. They said yesterday that Bulls slipped to 48.1 from 50 but Bears are sitting at just 16.7, down from 17.3 with the balance going to those who expect a Correction.
The CNN Fear/Greed is in the ‘fear’ camp at 28, on the cusp of moving to ‘extreme fear.’
Bottom line, at least looking at AAII, from a contrarian perspective, we’re set up for an equity bounce.
AAII Bears
AAII Bulls
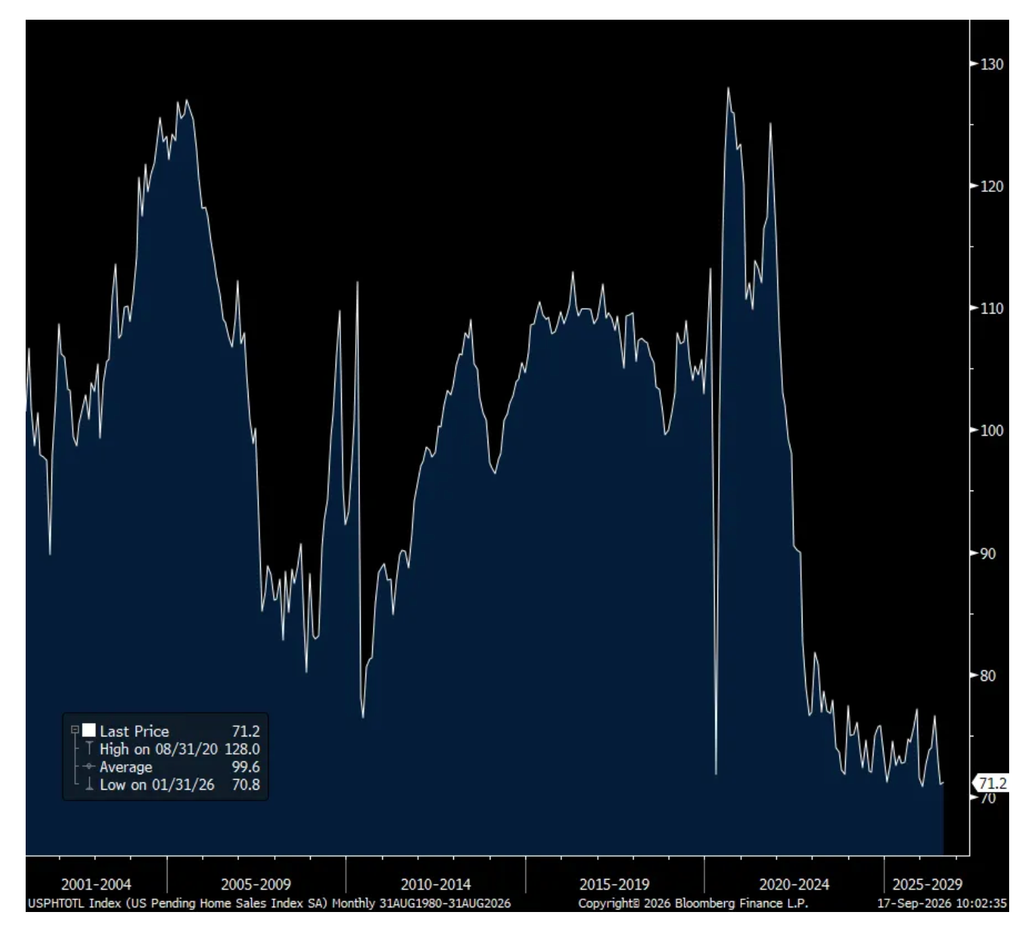
Finally, pending home sales in August were about as expected when including the slight downward revision to July but they remain punk. They rose .3% m/o/m after a decline of 2.6% in July. Regionally it was quite mixed with a 4.2% decline in the Northeast and 1.6% drop in the Midwest as they “saw the fastest home price growth in August” said the NAR, offset by a 3% rise in the West and 2.3% increase down South.
The index at 71.2 is basically sitting at the lows. Not surprisingly from the NAR, “the housing market is still sluggish, with contract signings below last year. This is due to higher mortgage rates offsetting the increased buying power created by job gains and income growth outpacing home price growth.”
Pending Home Sales index