Upside, Downside Movers in the Morning

Upside
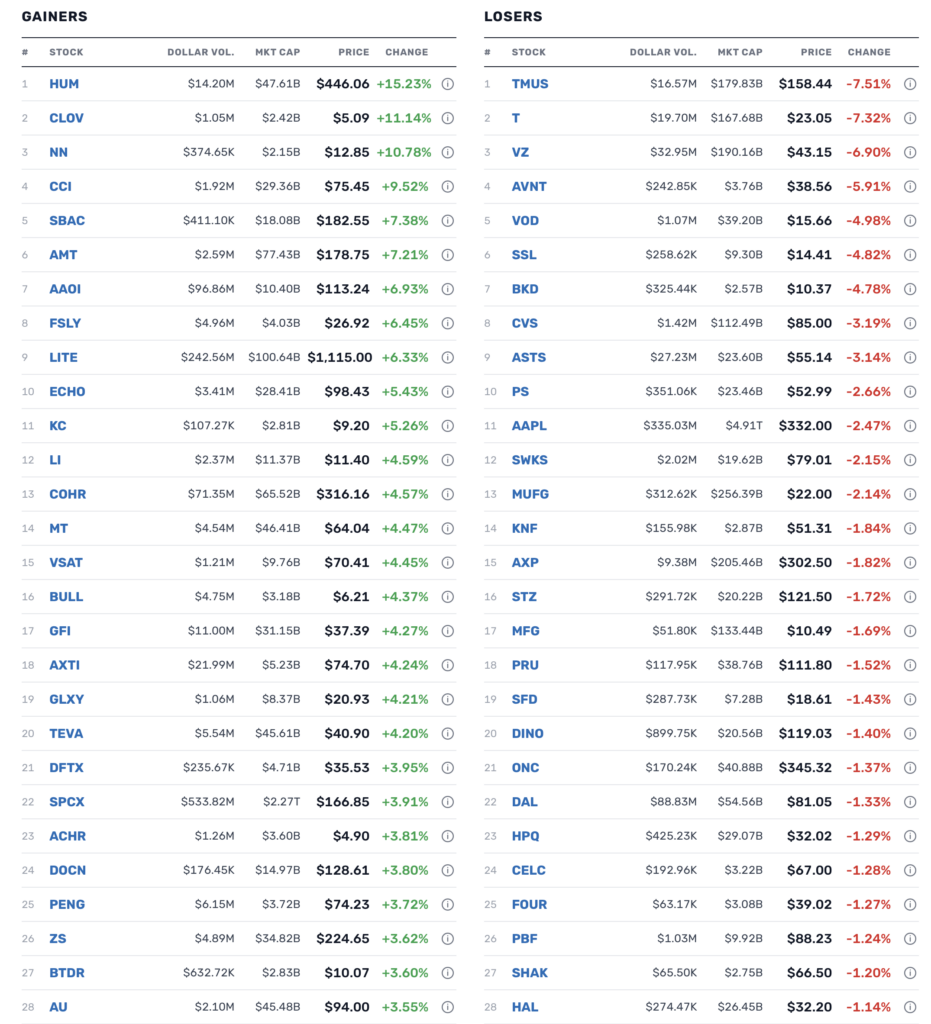
– $VEEA +45.0% (regained full Nasdaq listing compliance following its reverse stock split)
– $XRTX +21.0% (outlined planned FDA IND and Health Canada clinical-trial filings for XRx-026 in gout)
– $SAIQ +19.5% (confirmed an October satellite launch advancing its post-quantum secure-communications roadmap)
– $HUM +14.5% (2027 CMS Star Ratings exceeded its top-quartile revenue goal, with its largest contract returning above the bonus-payment threshold)
– $CLOV +11.5% (PPO plans earned 5 stars and the HMO plan earned 4.5 stars for 2027, strengthening 2028 payment and enrollment economics)
– $CCI +9.5%, SBAC +7.0%, AMT +7.0% (tower operators rally as SPCX’s low-band spectrum deal implies a terrestrial buildout and potential new-tenant demand)
– $FSLY +7.0% (Oppenheimer upgrades to Outperform with a $35 target on AI-traffic growth)
– $AAOI +6.0%, LITE +6.0%, COHR +4.5%, GLW +3.5% (optical names rise after LITE said AI-data-center demand has booked component capacity through early 2029)
– $ECHO +5.0% (SPCX’s additional spectrum purchase reinforces the value of ECHO’s existing spectrum and equity partnership)
– $SPCX +4.0% (agrees to acquire a nationwide 800 MHz spectrum portfolio for about $8B, strengthening its direct-to-device mobile push)
Downside
– $ALHC -23.0% (key California HMO contract fell to 3.5 stars, below the CMS quality-bonus threshold)
– $TMUS -7.5%, T -6.5%, VZ -6.0% (wireless carriers slide as SPCX’s nationwide low-band spectrum acquisition raises the threat of direct mobile competition)
– ASTS -3.0% (falls after SPCX acquired spectrum ASTS had pursued, increasing competitive and spectrum-access concerns)
– $CVS -3.0% (only about 69% of Medicare Advantage members are in 4-star-plus plans for 2027, down from 81% for 2026)
– $AAPL -2.5% (no clear fresh catalyst identified; unusually large mega-cap decline despite higher Nasdaq futures)
– $DAL -1.5%, LUV -2.0%, $UAL -1.5% ($DAL missed Q3 profit expectations and sharply cut its FY outlook as surging fuel costs overwhelmed strong demand)