Atlanta Fed Q3 GDP Tracker Eases to +3.5%

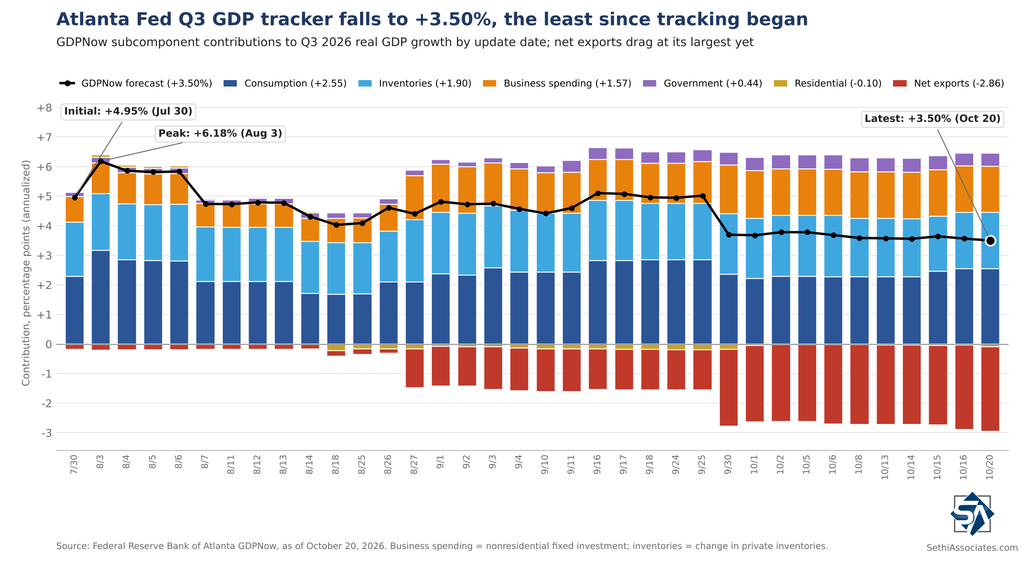
The Atlanta Fed’s Q3 real GDP tracker slipped to +3.50% as of October 20, the least since it initiated tracking and down from +3.59% on October 8th.

A +0.28% rise in the contribution from consumption (to +2.55% from +2.27%) after the retail sales report was more than offset by three declines: a -0.17% drop in net exports (to -2.86% from -2.69%) after the import and export prices data, and smaller declines in inventories (-0.08%) and residential investment (-0.07%, after this morning’s housing starts).

This continues to be consistent with my ongoing caveat that in both Q1 and Q2 we saw this indicator fall sharply the month before the actual GDP reads (which for Q3 will be next week).

The reading for now remains above the blue chip consensus* of ~+2.5%.

Here’s the breakdown of the components as of October 20 and changes from my last update October 8:

Consumption = +2.55% (+0.28%)

Inventories = +1.90% (-0.08%)

Nonresidential fixed investment (biz spending) = +1.57% (+0.01%)

Gov’t = +0.44% (-0.04%)

Residential investment = -0.10% (-0.07%)

Net exports = -2.86% (-0.17%)

GDPNow Forecast: +3.50% (-0.09%)
Pending Qualcomm Layoffs Reflect Weak End Markets, Not Culture Building

Reuters is reporting that Qualcomm ($QCOM) is poised to embark upon a “performance-focused reduction” in headcount with ‌notifications set to begin in November.

While Reuters reports these moves are “part of an effort to build ‘a stronger performance culture’ and address situations where the company ‘has consistently fallen short of expectations'”, the reality of the situation can be traced back to recent data from IDC and other research firms about the smartphone and PC markets.

According to the IDC Worldwide Quarterly Mobile Phone Tracker, global smartphone shipments plunged a record 22.0% year-over-year in Q3 2026 to 255.3 million units due to the “AI-led memory and RAM crisis.”

Preliminary data from IDC finds worldwide PC shipments dropped 20.1% year-over-year in Q3 2026 to 62.7 million units.

With industry figures like those, odds are Qualcomm won’t be the only supplier to those end markets reducing headcount.

Charting the Late Morning Market

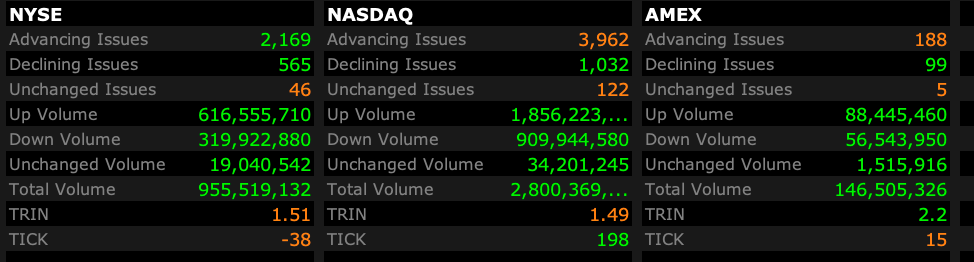
– NYSE volume flat to its one-month average;

– Nasdaq volume 8% above its one-month average;

– VIX index:  down 3.80% to 17.74

Breadth

SOURCE: Interactive Brokers

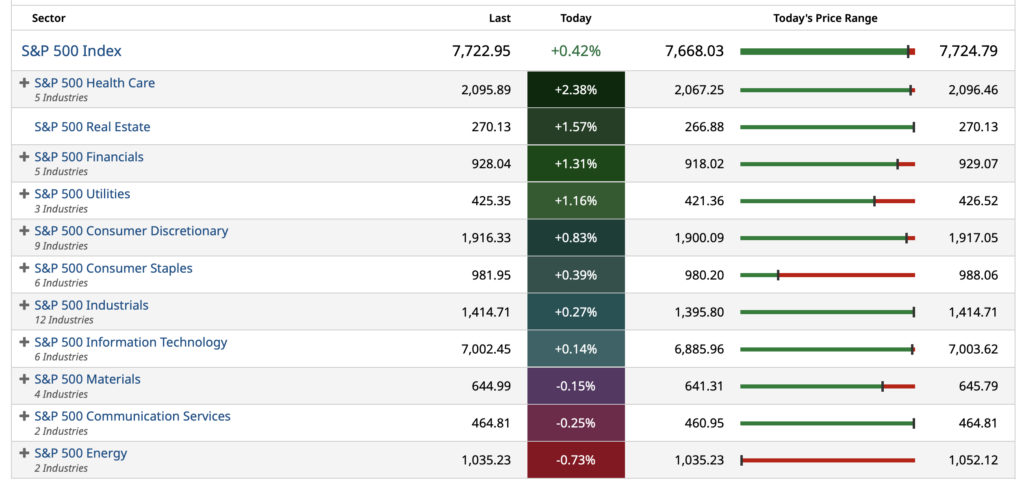
S&P500 Indexes

SOURCE: Barchart

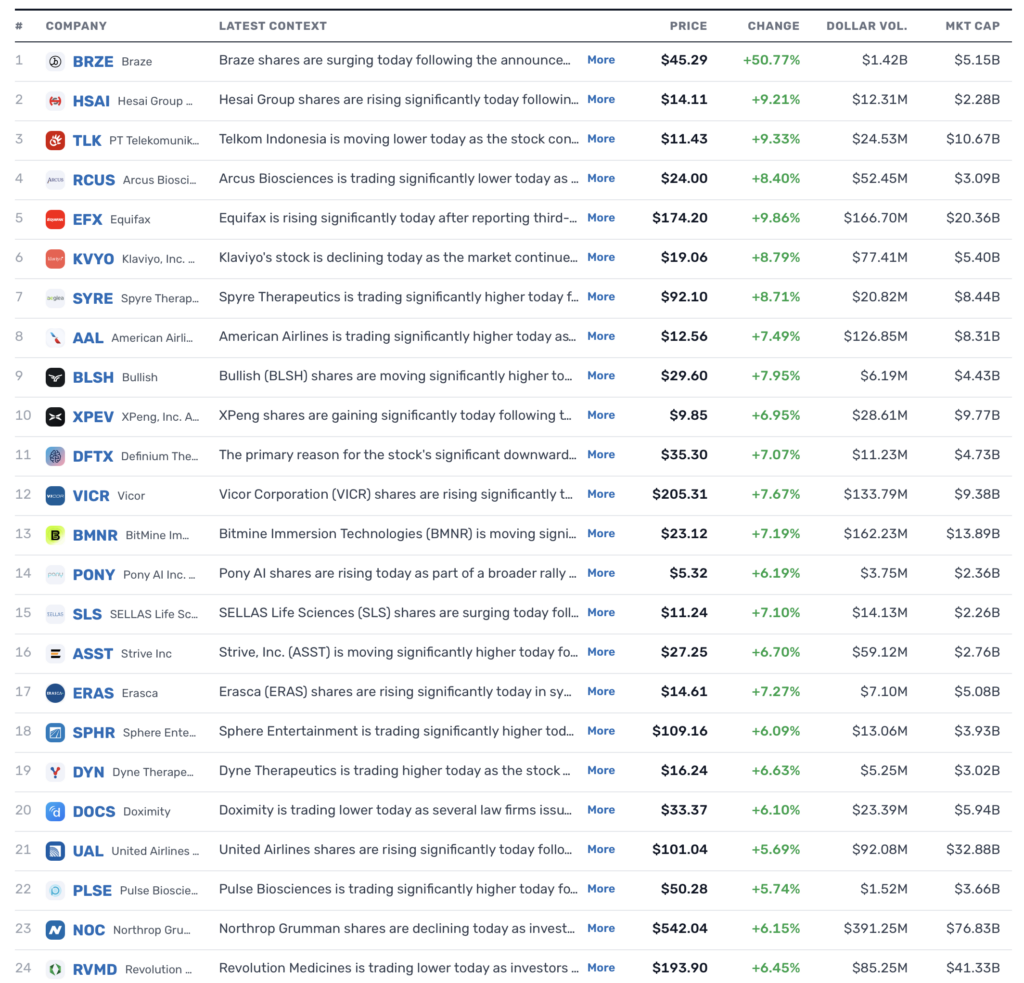
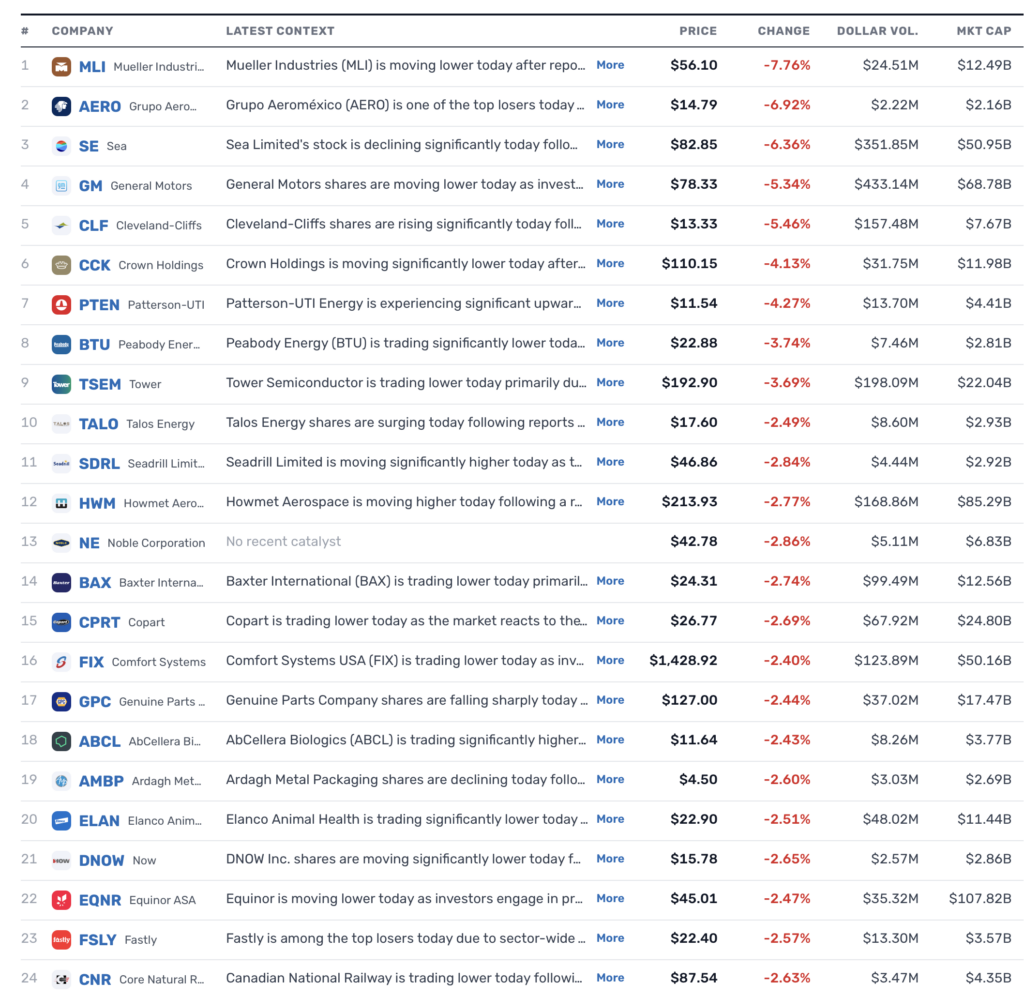
% GAINERS, DECLINERS

SOURCE: TheStreet Pro

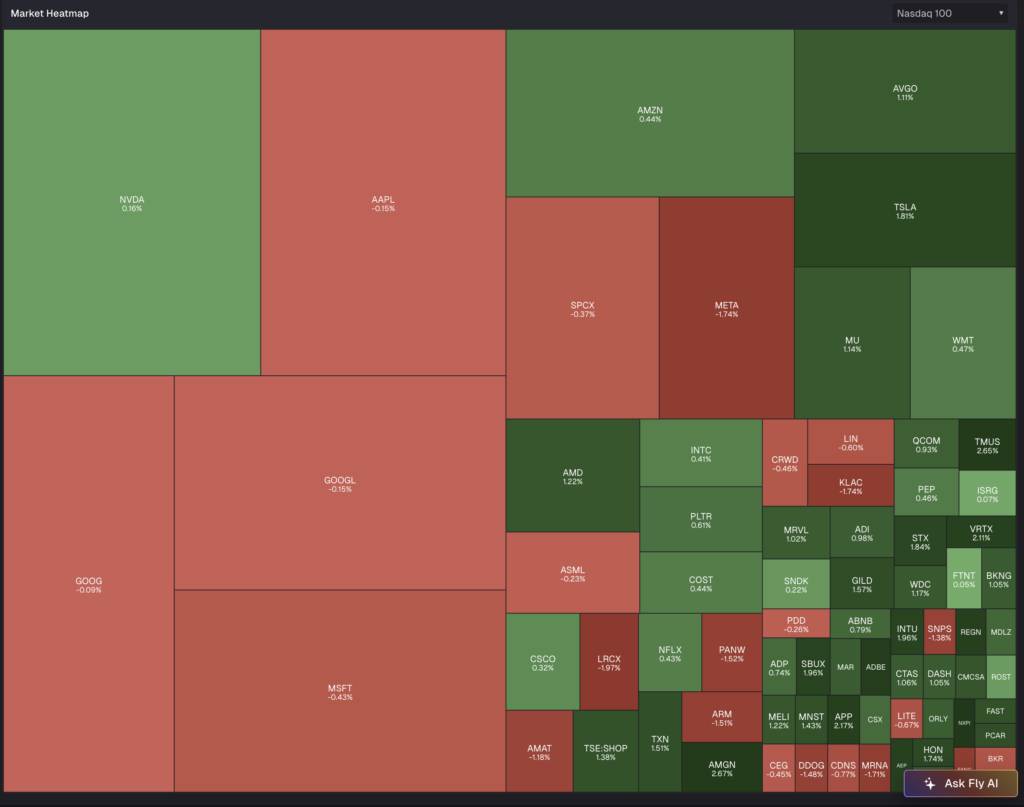
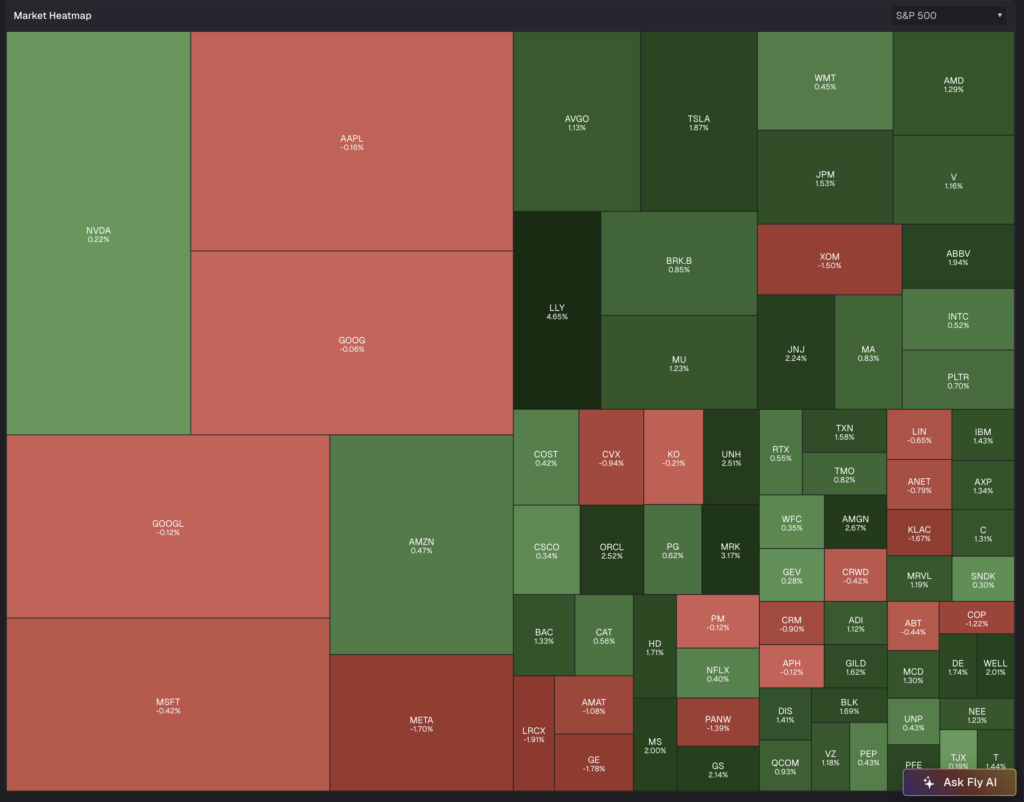
Nasdaq 100 and 

S&P500 Heat Maps

SOURCE TheFly

Fake News?

Break in!

Equities are taking a leg lower based on reports (from “Trade The News“) that an Iran/U.S. ceasefire deal is “close” is untrue.

Position: None

More on The Weave

I covered my $CRWV short between $62 AND $63 on Sunday night – as reported.  

Positions: None.