Oscillator Modestly Overbought

The S&P Short Range Oscillator remains in a modest overbought at 1.43% vs. 1.56%
I have no index positions on currently.
Position: None
The S&P Short Range Oscillator remains in a modest overbought at 1.43% vs. 1.56%
I have no index positions on currently.
Position: None
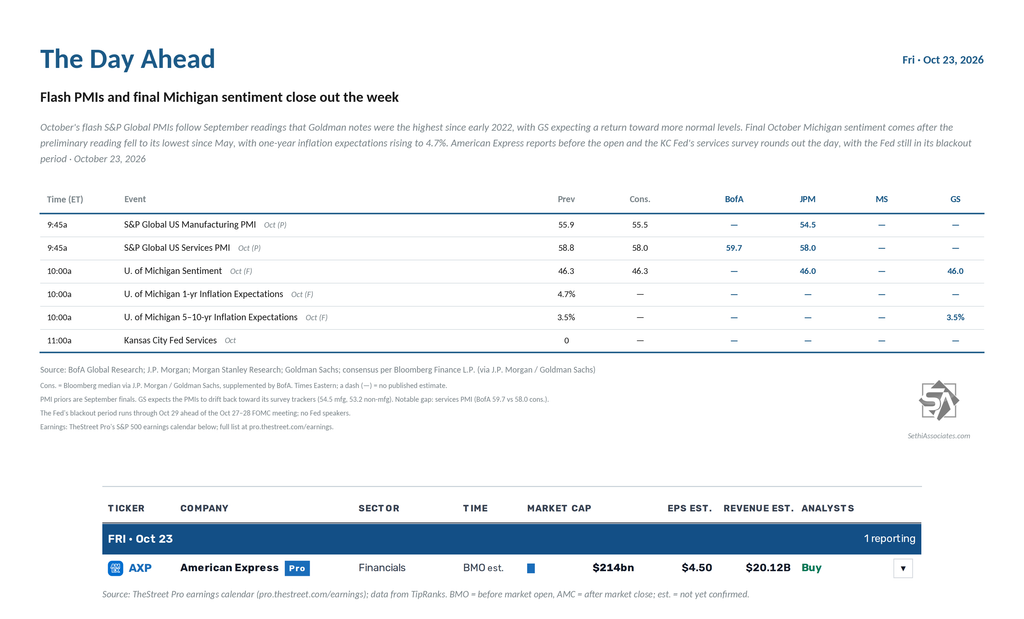
US economic data closes out the week with October’s flash S&P Global PMIs, final University of Michigan consumer sentiment and the Kansas City Fed’s services survey.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
No non-Bill (>1yr in maturity) US Treasury auctions.
Q3 earnings season continues with one S&P 500 component, American Express ($AXP).
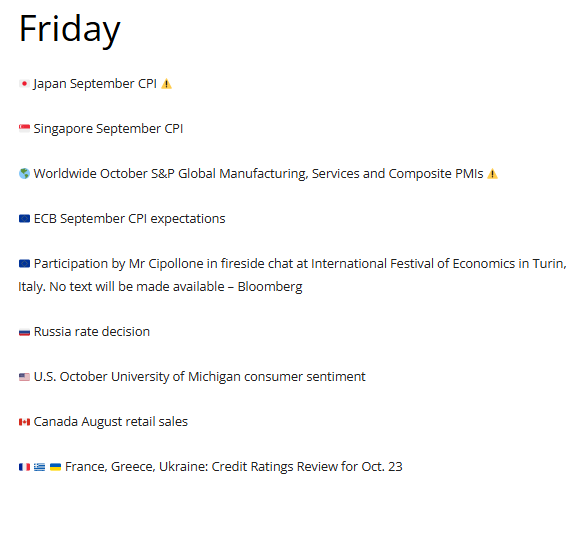
Ex-US highlights are global flash PMIs, ECB consumer expectations survey, UK October GfK consumer confidence, September retail sales, Japan September national CPI, and Canada August retail sales.
From Christophe Barraud’s international Week Ahead rundown:
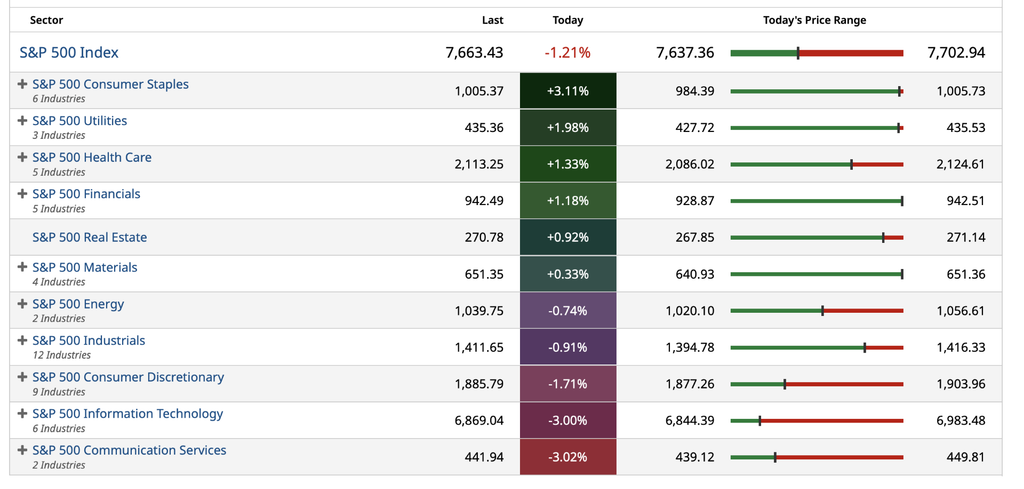
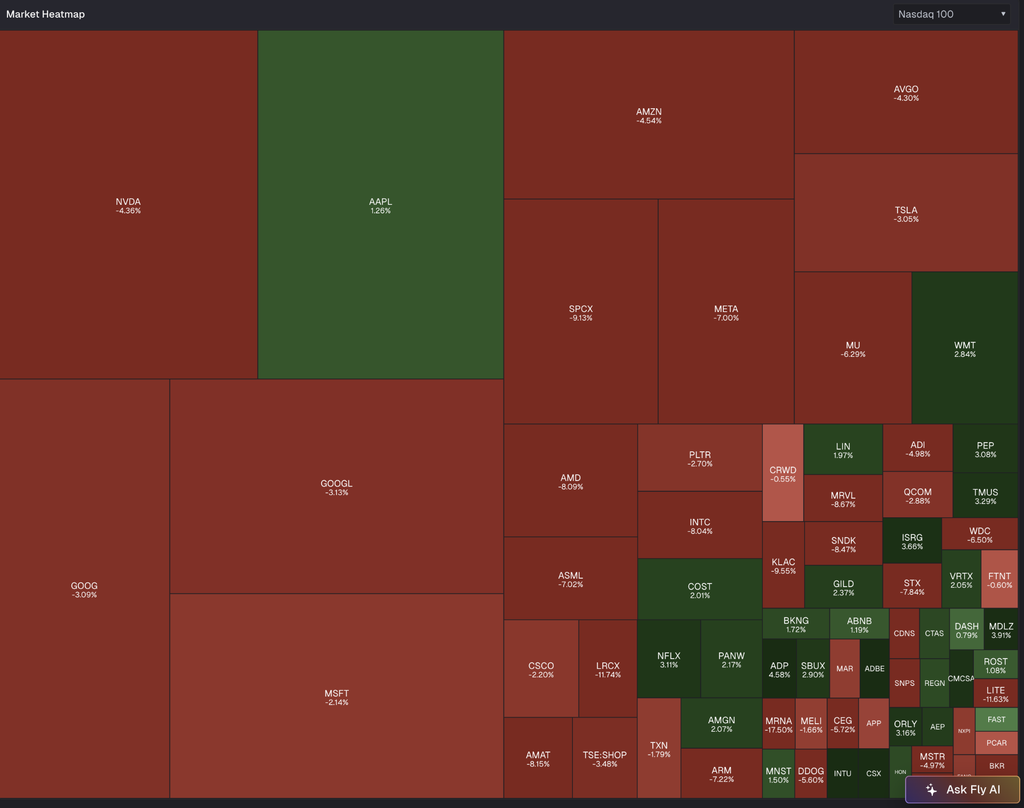
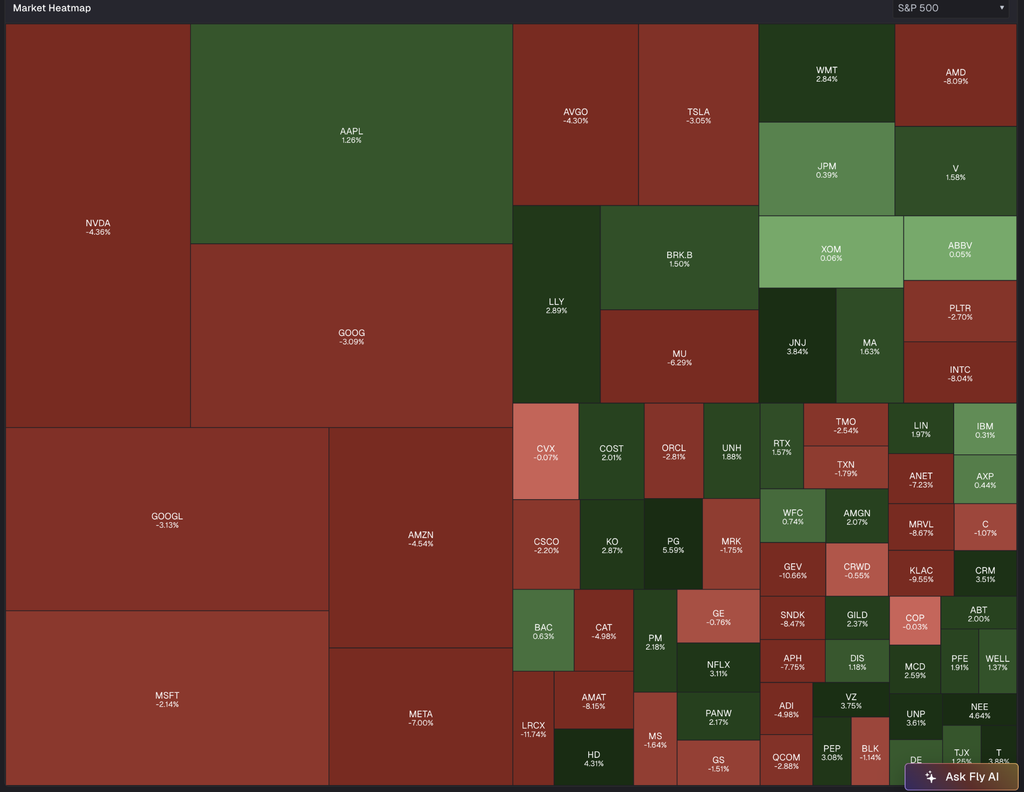
The market was down today, but the selling was orderly and concentrated in tech and the mega caps.
Worries about the sustainability of the AI trade surfaced once again, driving down a swath of related stocks, but other stocks rallied as Treasury yields dropped the most since August 2025, seeing equal-weight vs cap-weight the most extreme since 2024.
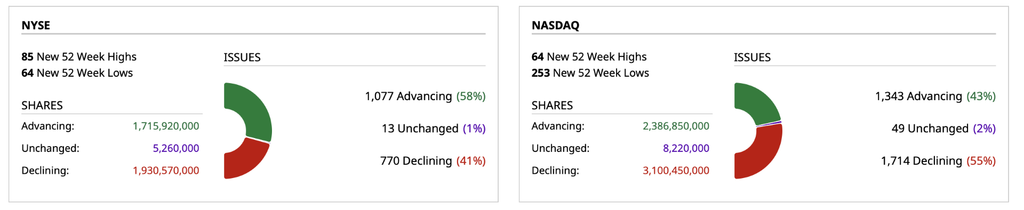
Why was the market down on a day that breadth was positive? It’s that either/or market again.
Closing Volume
– NYSE volume 14% above its one-month average;
– NASDAQ volume 14% above its one-month average;
– VIX index: up 14.39% to 19.08
Breadth
S&P 500 Sectors
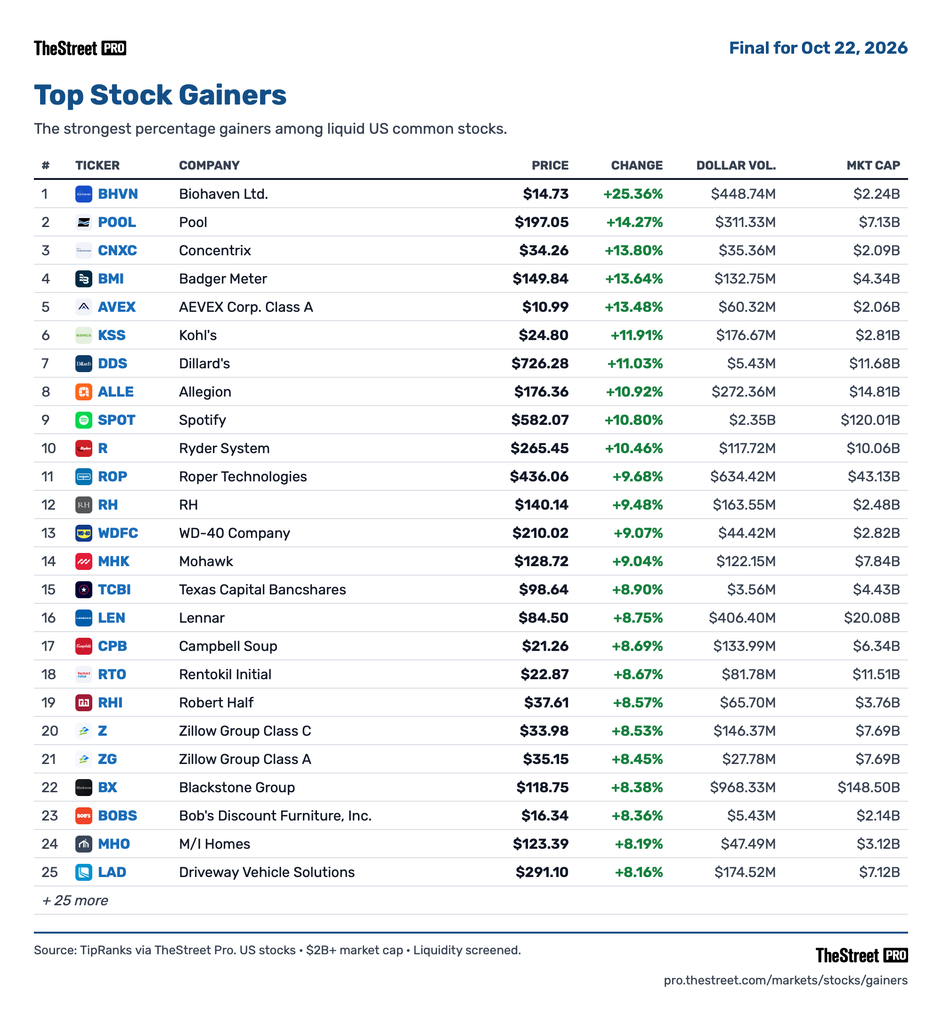
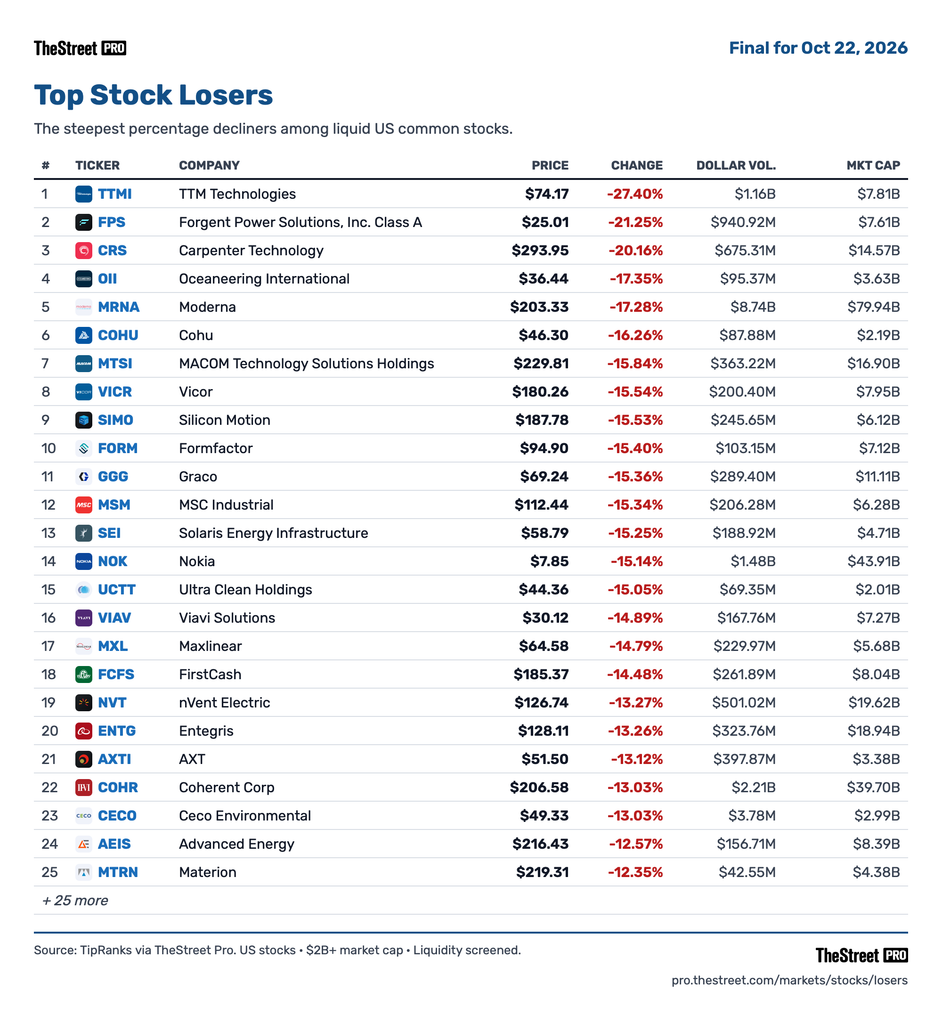
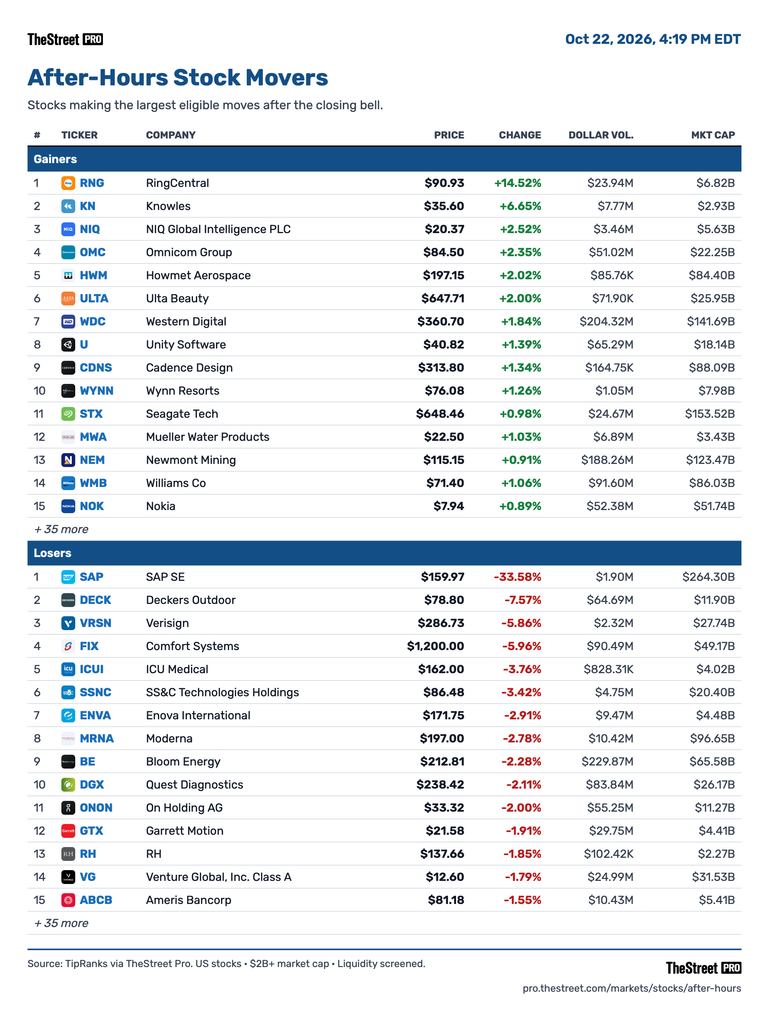
% Movers
Heat Maps
Position: None
The gap is closing, but the opportunity is in new leaders, not broken AI names.
Position: None
AI demand is pulling through across sectors, but supply constraints remain a headwind.
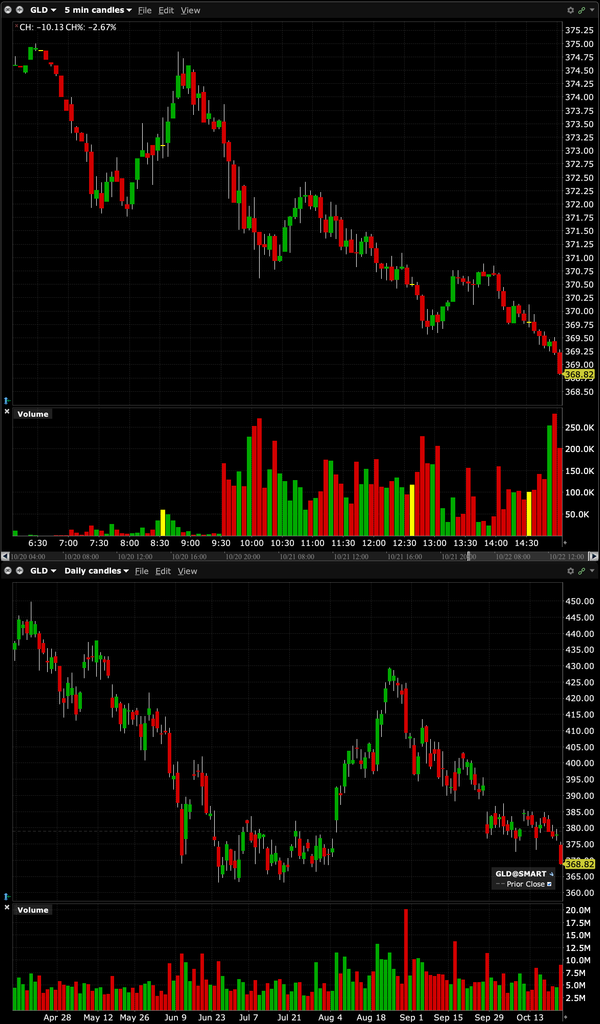
$GLD: (intraday and daily chart)
Position: None