A Tech Led Rebound to Kick Off the Week

Let’s dig in following an up day on Wall Street to see what’s happened and what to expect.
Let’s dig in following an up day on Wall Street to see what’s happened and what to expect.
Sentiment remains bullish for the Mags and Semis. But volume appears to be narrowing. Here’s my analysis.
Closing Volume
– NYSE volume 20% above its one-month average
– NASDAQ volume 6% below its one-month average
– VIX index: down 4.94% to 18.49
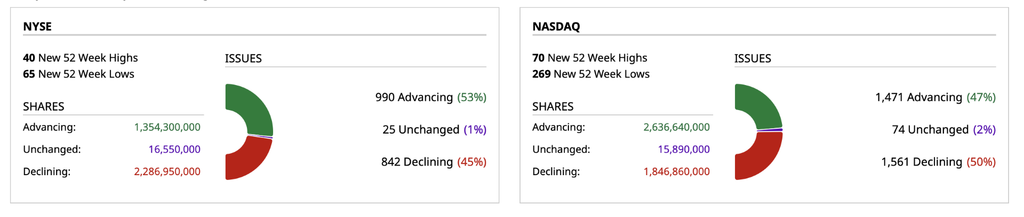
Breadth
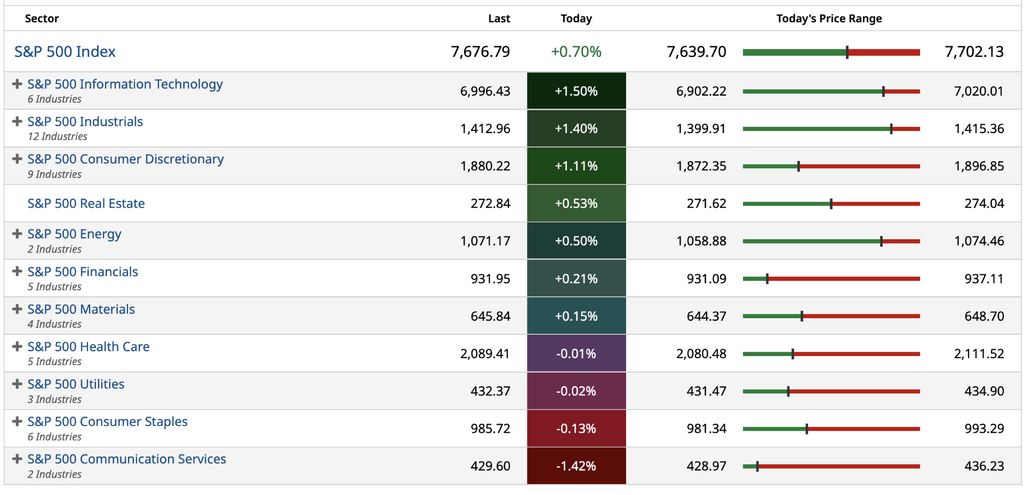
S&P 500 Sectors
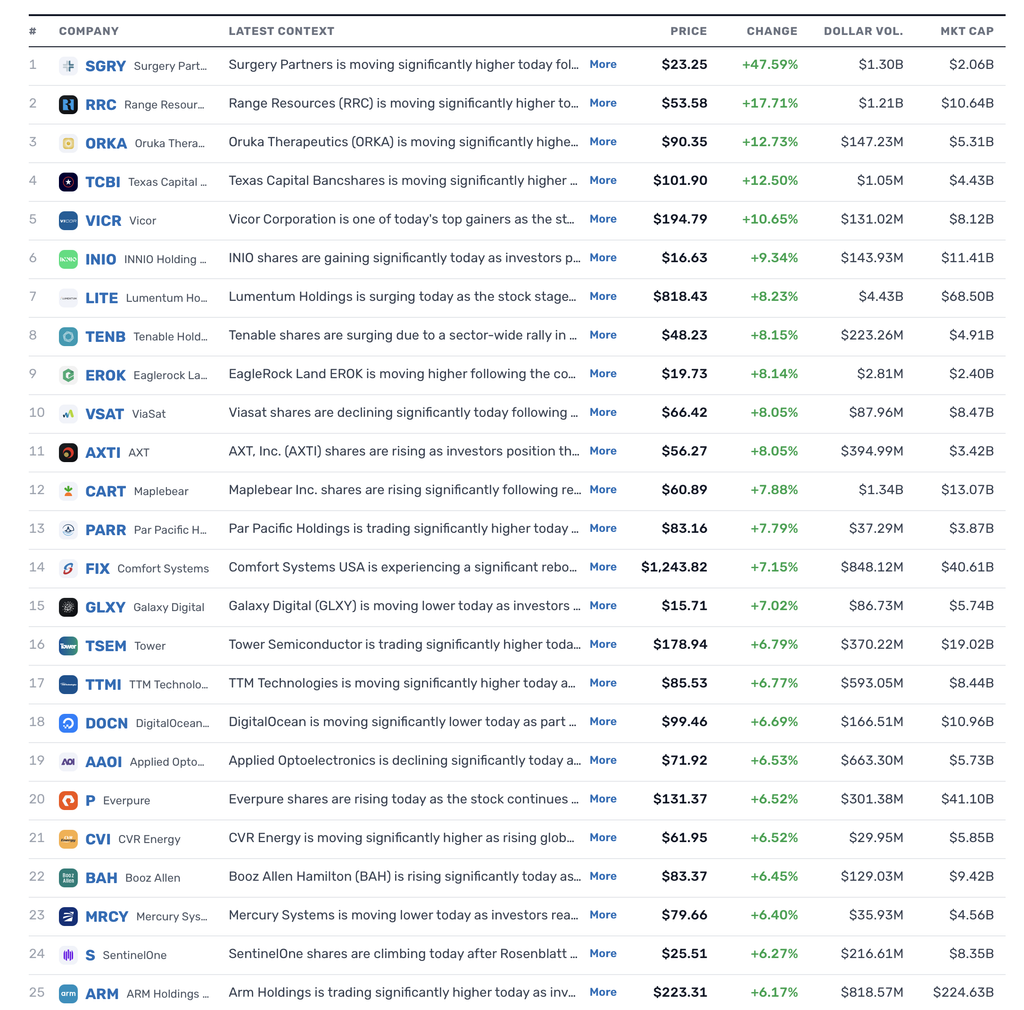
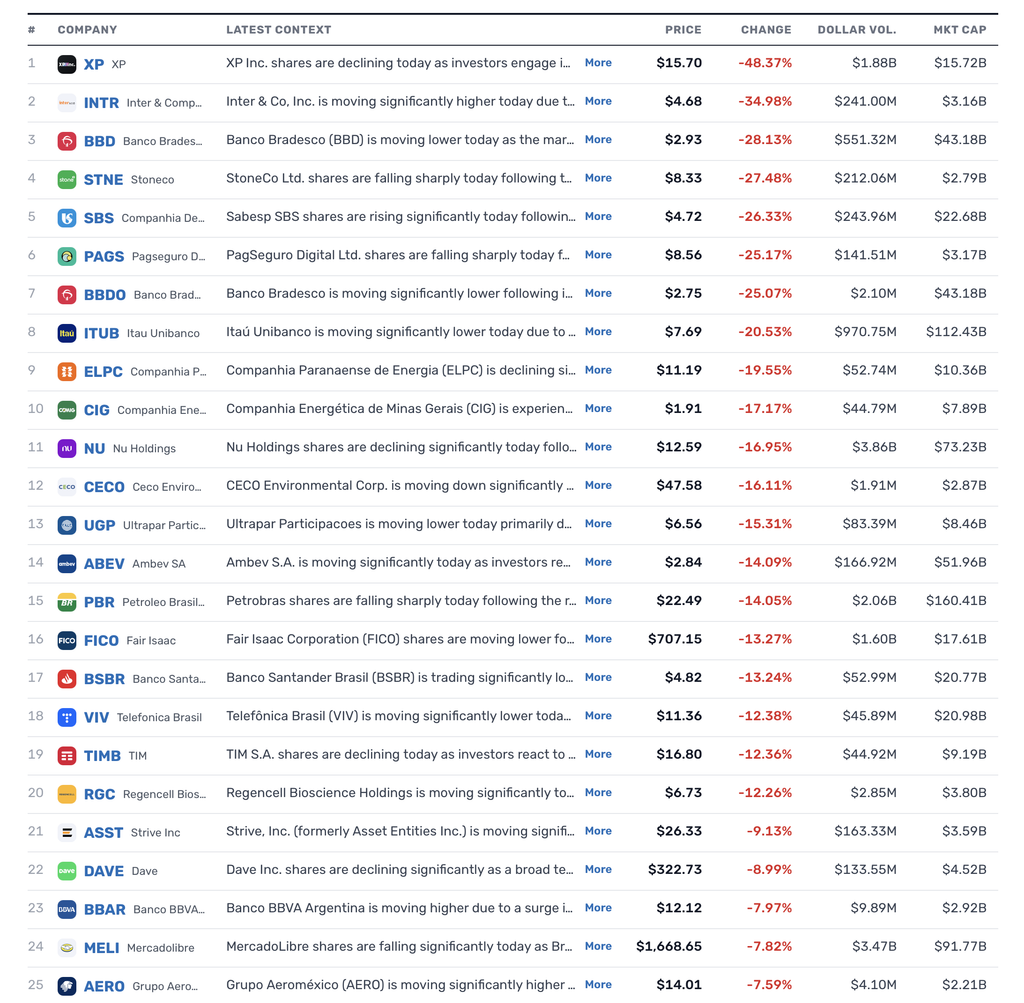
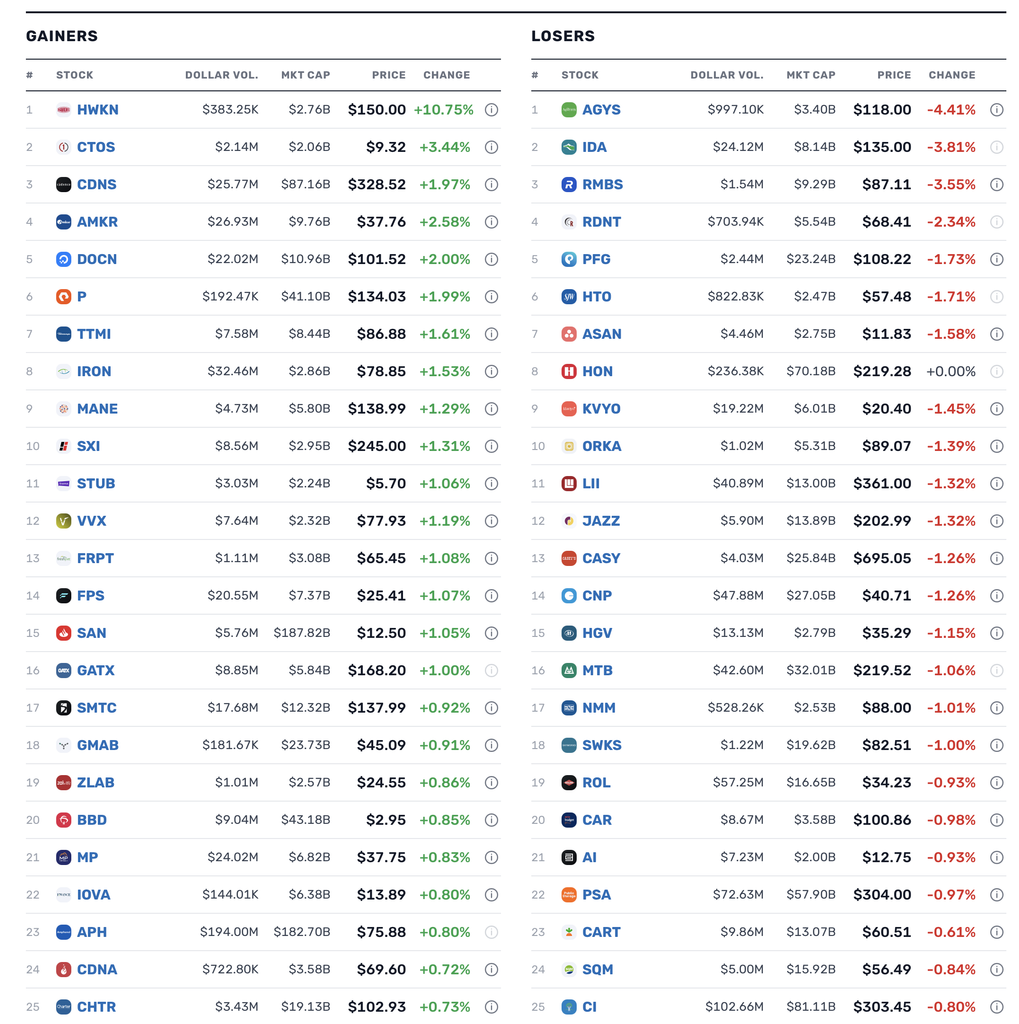
% Movers
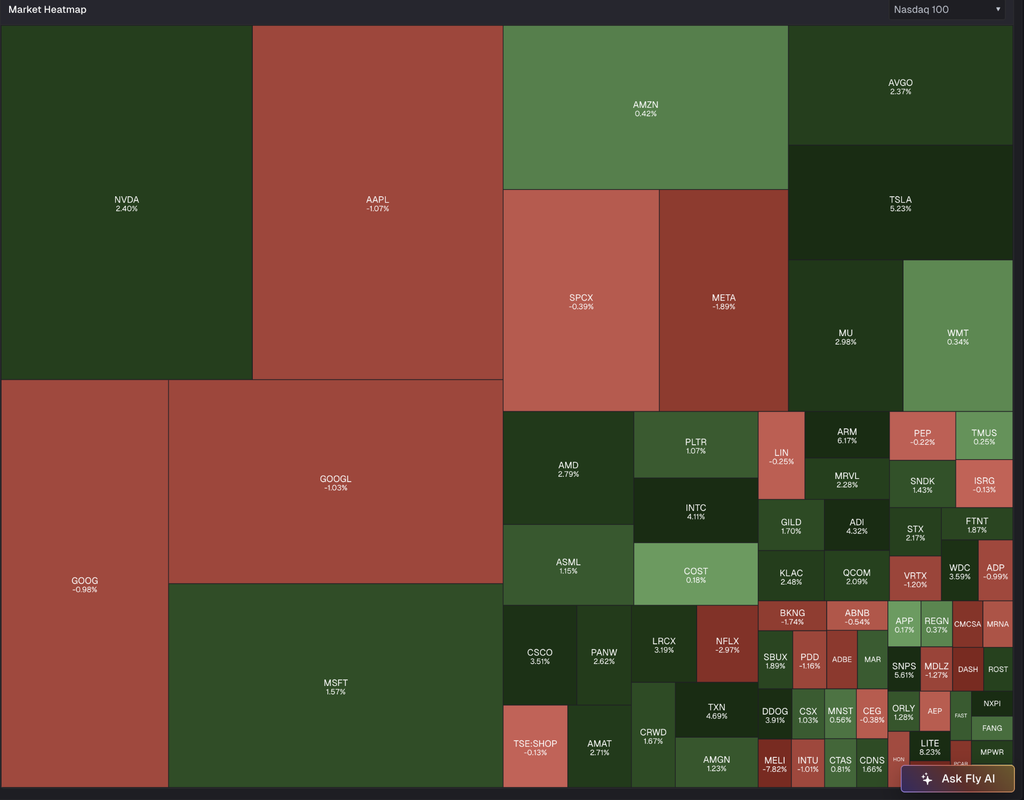
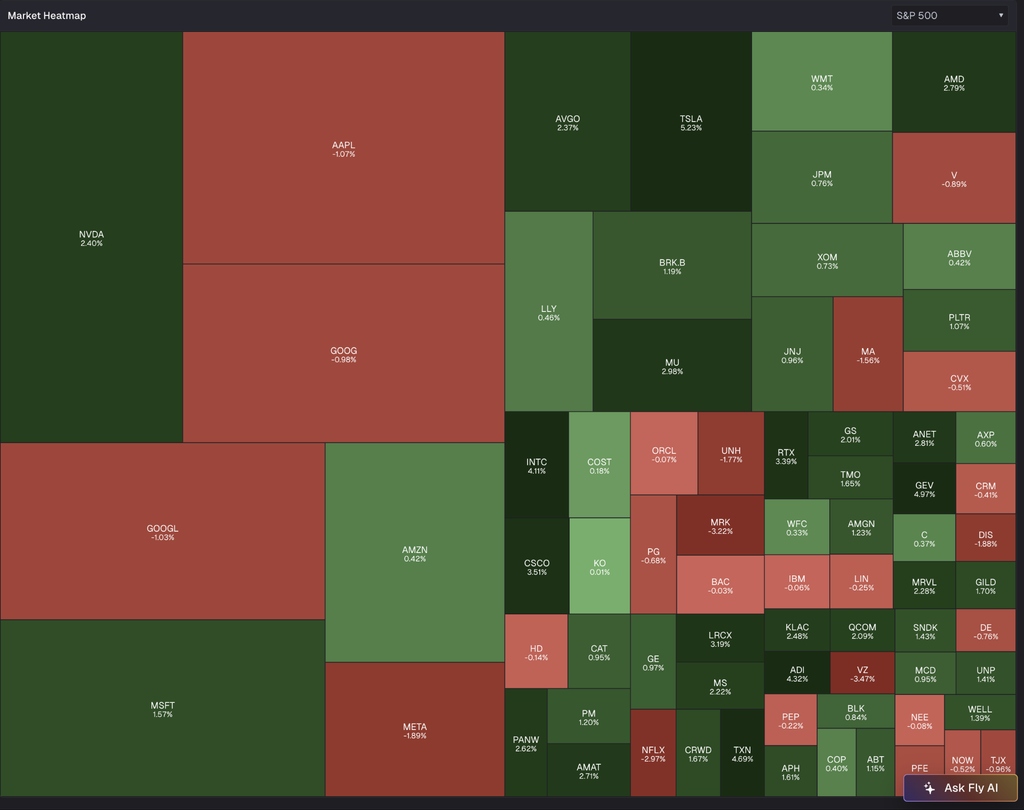
Heat Maps
Position: None
Position: None
Chips and the mega caps bounced, but breadth was weak and new lows stayed high.
I have a lengthy research call beginning at 4 PM today.
Position: None
Wolf Street howls about who is the “smart money” in the U.S. housing market.
Position: None
I am sure a lot will be learned about the Anthropic S-1 over the next few days.
But among the most (worrisome) big-picture issues is the amount of insider selling the IPO allows for (including right at the time of the IPO) without a lockup.
If the insiders and investors who know the most about the company are in a rush to sell, why would anyone be in a rush to buy?
This reminds me of the CoreWeave ($CRWV) executive who claimed that the selling in CRWV’s shares was irrational, while he and every other member of senior management had sold hand over fist.
The whole structure, governance, financials, opacity, selling, valuation, the whole deal just smacks of hubris and arrogance. There is an underlying expectation that the greater fools continue to line up, nod in bovine agreement, and eat the slop they are fed by the VCs et al:
Oh in there is this line in there too. Just classic:
Position: None
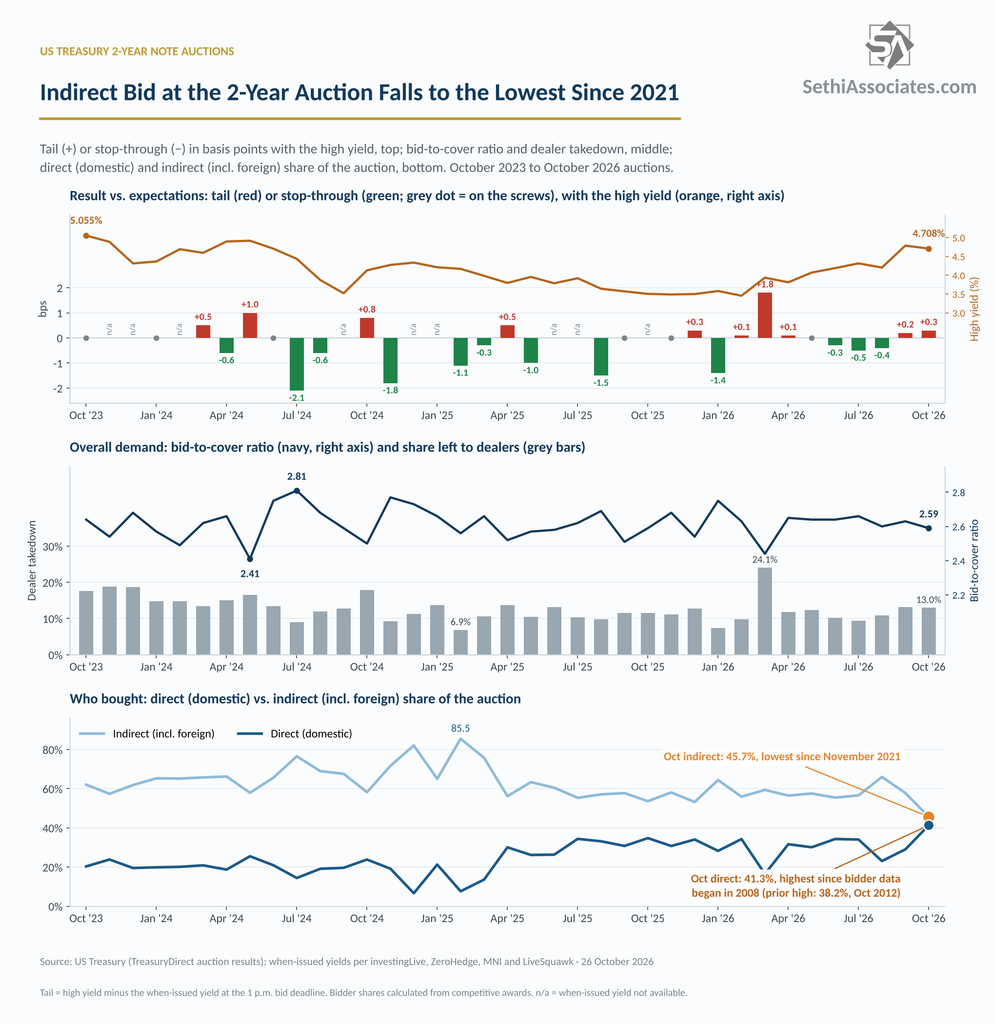
The first of this week’s three coupon (>1 year in maturity) Treasury auctions came today in $69 billion of 2-year notes, and while the end result was a bit soft, the mix of buyers stood out. Direct (domestic) bidders ended up with a record share after indirect bidders, a group that includes foreign buyers, fell to the lowest since November 2021.
The sale cleared at 4.708%, down from 4.787% in September, which was the highest since May 2024, and tailed (came in above expectations) by +0.3bps against a when-issued of 4.705%. That was the second straight tail, after +0.2bps in September, and compares with a 6-mth avg of a -0.2bps stop-through.
Looking at the rest of the metrics:
-Overall demand (bid/cover) fell to 2.59, the lowest since March, from 2.63 in September and below the 6-mth avg of 2.64.
-Indirect bidders (which include foreign buyers) dropped to 45.7%, the lowest since November 2021, from 57.8% in September and well below the six-month average of 58.3%.
-Direct (domestic) bidders jumped to 41.3%, the highest in Treasury data going back to 2008 (easily topping 38.2% in October 2012), from 29.0% in September and well above the six-month average of 30.4%.
-That left dealers (another metric of the strength of demand – the lower the better) with 13.0%, down from 13.2% in September but above the six-month average of 11.3%.
The indirect drop is worth watching, and comes on the heels of my post this morning about concerns that Japanese investors may be stepping back from Treasuries. Indirect bidders also include US funds, though, so Treasury’s investor-class data for October, released with a lag, will show how much of the pullback was actually foreign.
“Generalissimo Francisco Franco is still dead.”
– Chevy Chase, Saturday Night Live
SNL Weekend Update: Generalissimo Francisco Franco
Despite protestations from most of the panelists and guests on the Shows… I have said/written to avoid Netflix ($NFLX) at over $100 (in April 2026), at $85 (in June 2026) and again last week at over $70.
And I will say it again, today — at $63.
I still would not bottom fish in Netflix’s shares.
From last week:
My View on Netflix
Repeating for emphasis, I would not bottom fish in Netflix (NFLX).
I expect in line-to-better 2Q2026 results but a possible lower forward guidance as margins are pressured.
From last month:
Netflix Is Too Low to Short and Too High to Buy
I would continue to avoid buying (and “bottom fishing”) in Netflix (NFLX) for the reasons I have previously mentioned:
* Netflix has nearly saturated the domestic market (as well as many other developed countries). These markets are significantly more profitable than the non developed arena.
* Future Netflix sales/profit growth will come from developing country markets that provide substantially less revenue (and income) per subscriber.
* Netflix’s original content programming has been unspectacular over the last 12 months (or more) — and existing content has suffered.
In the past I have been short NFLX, but it is no longer priced as an attractive short.
Position: None
BY Doug Kass · Sep 22, 2026, 1:50 PM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 4:09 PM EDT
Position: None