Added to Apple Short

I added to Apple ($AAPL) short at $347.16
Position: Short AAPL (S)
I added to Apple ($AAPL) short at $347.16
Position: Short AAPL (S)
At $770.77, I moved to medium-sized short $SPY.
Position: Short SPY (M)
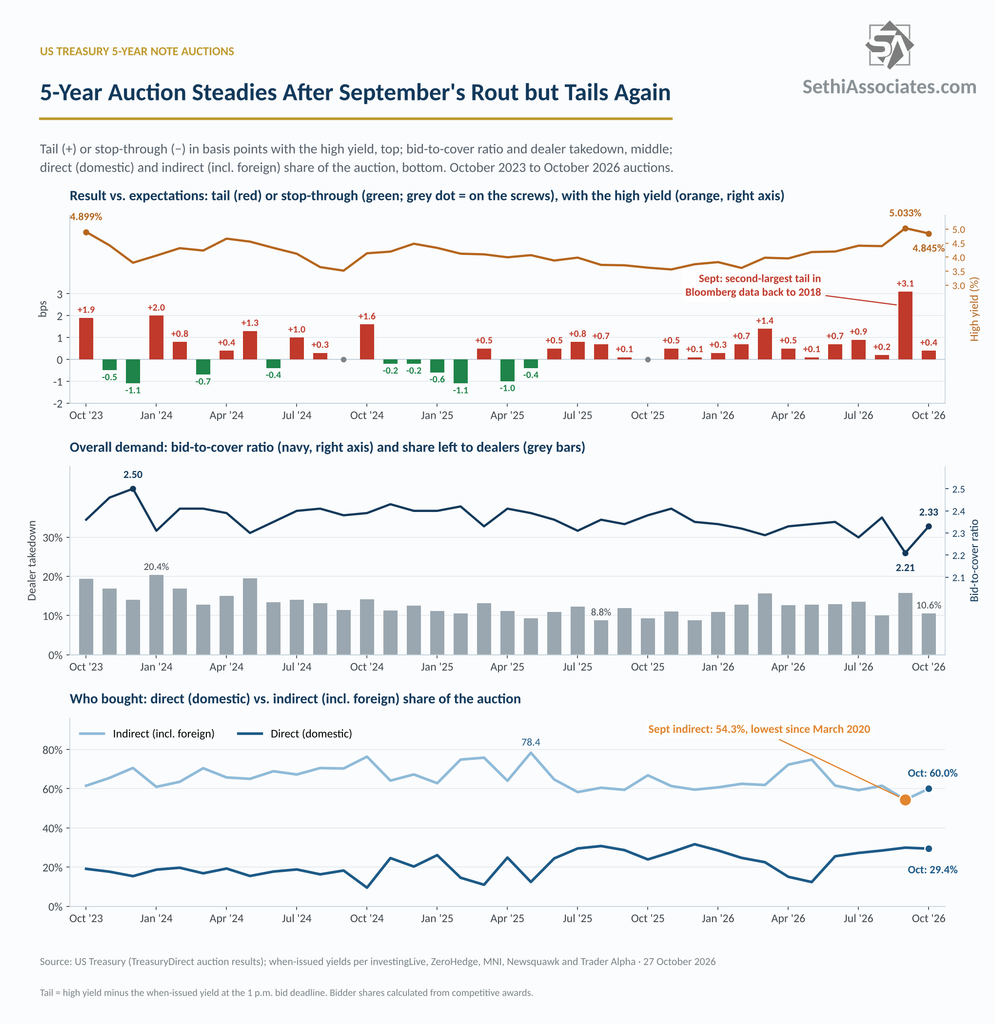
Foreign buyers weren’t interested in Monday’s 2-year Treasury auction, where indirect bidders (which include foreign buyers) fell to the lowest since November 2021 as direct (domestic) bidders took a record share. They were more so, though, in today’s $70 billion 5-year auction, the second of this week’s three coupon auctions (more than one year in maturity). That lead to better overall demand, even more so compared with September’s historically bad auction, even as the end result was the 12th straight tail (yield above expectations) for this maturity.
Looking at the specifics:
-The sale cleared at 4.845%, down from 5.033% in September (the first 5%-plus for this maturity since 2007), and tailed by +0.4 basis points. That was a big improvement from +3.1 basis points in September, the second-largest in Bloomberg data back to 2018, and better than the six-month average of +0.9 basis points. But it was still the 12th straight tail (the last auction that didn’t tail was October 2025, which priced “on the screws”) and the 17th straight auction without a stop-through (the last was May 2025).
-Overall demand (bid/cover) rose to 2.33 from 2.21 in September (the lowest since December 2018), slightly better than the six-month average of 2.31.
-Indirect bidders (which include foreign buyers) recovered to 60.0% from 54.3% in September (the lowest since March 2020), but stayed below the six-month average of 64.0%.
-Direct (domestic) bidders took 29.4%, down slightly from 29.9% in September (the highest since December 2025), but well above the six-month average of 23.1%.
-That left dealers with 10.6%, the lowest since August, down from 15.8% in September (the most since May 2024) and better than the six-month average of 13.0%.
Overall, it was clearly not a great auction given the tail, but it was better than Monday’s 2-year and much, much better than last month’s auction.
What we’re watching to see through diminished near-term industry visibility.
* This week I warned that it was ‘too much too fast’…
I further reduced my staples exposure recently — today we are seeing a lot more pressure on consumer non-durables (($PG) -$1, ($PEP) -$3, ($KMB) -$1 and ($KO) -$1.25 (I warned about a sell off after the guide up).
From last week:
Staples Slammed
Staples (consumer non-durables) are getting hit over the last few hours.
A reminder, I am down to VS on KMB, PG and KO.
I sold out my entire PEP holdings.
I would be a buyer of the space on weakness — but not at current prices.
Position: Long KMB (VS), PG (VS), KO (VS)
Position: LONG KMB (VS), PG (VS) KO (VS)
Jio Platforms, backed by Meta and Google, is due to list on Wednesday. Here’s what to watch in the offering.
Wolf Street howls about rising home inventories and lower home prices:
Positions: None
Curaleaf ($CURLF) has been on a mission to acquire Aurora Cannabis ($ACB).
Aurora is uninterested and it looks like it might fend off Curaleaf: “Aurora Cannabis Reaffirms Recommendation to Shareholders: REJECT Curaleaf’s Revised Hostile Bid; Preserve Opportunities for Future Upside.”
The short interest in CURLF is up by 57% in the last month to about 1.08 million shares.
Should Curaleaf abandon the proposed acquisition and if cannabis rescheduling goes through, we might see an outsized rise in Curaleaf’s shares as shorts seek to cover.
I have recently added to CURLF based on the above.
Positions: Long CURLF (S)
A differentiated AI infrastructure model can benefit from vibrant demand.
I am re-shorting ($GRNY) at $27.55.
Positions: Short GRNY (S)