More SPY Moves

I moved from small- to medium-sized short ($SPY) at $767.75.
Position: Short SPY common M calls S
I moved from small- to medium-sized short ($SPY) at $767.75.
Position: Short SPY common M calls S
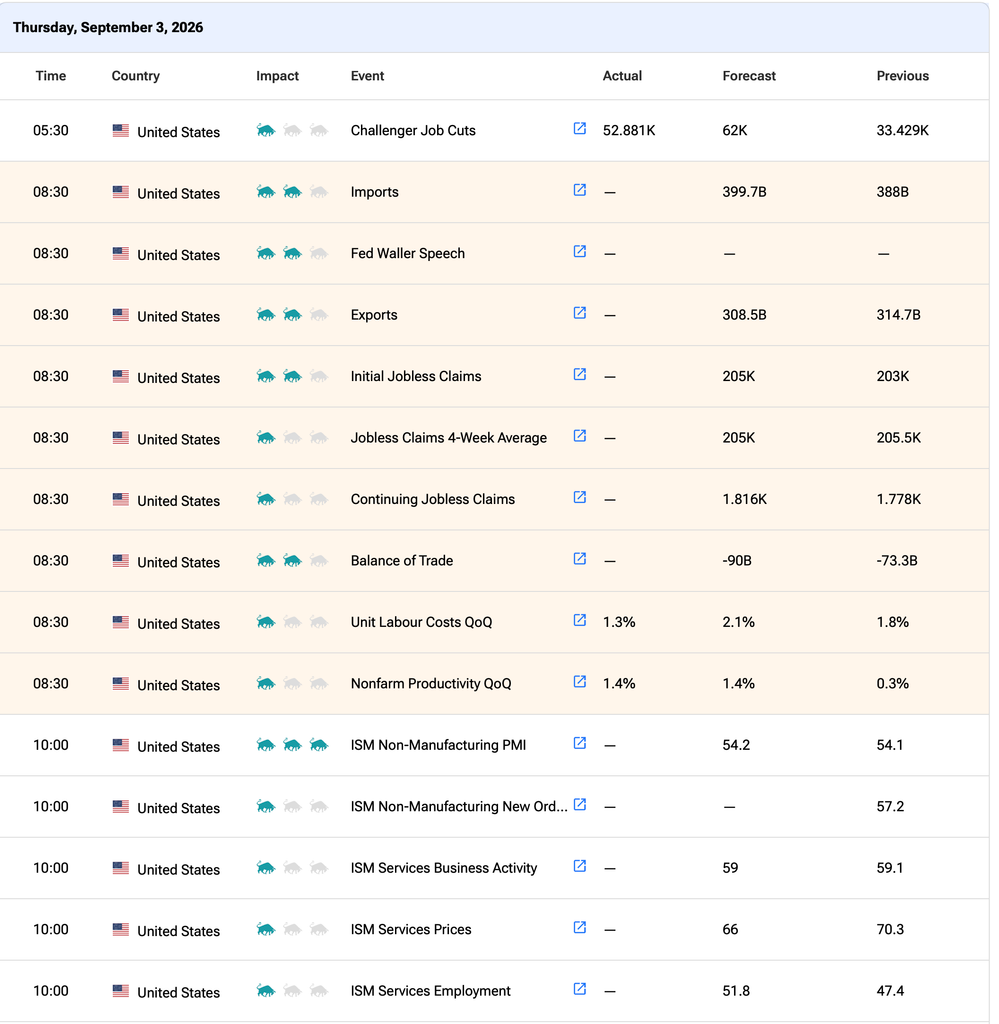
I added to my ($SPY) short at $766.61 on the jobless claims report.
Gold is benefiting from the report and is now trading at $410.24 (+$7.25 on the day and +$15 from yesterday morning’s low (where I added to))
Positions: Long GOLD S; Short SPY Common and Calls.
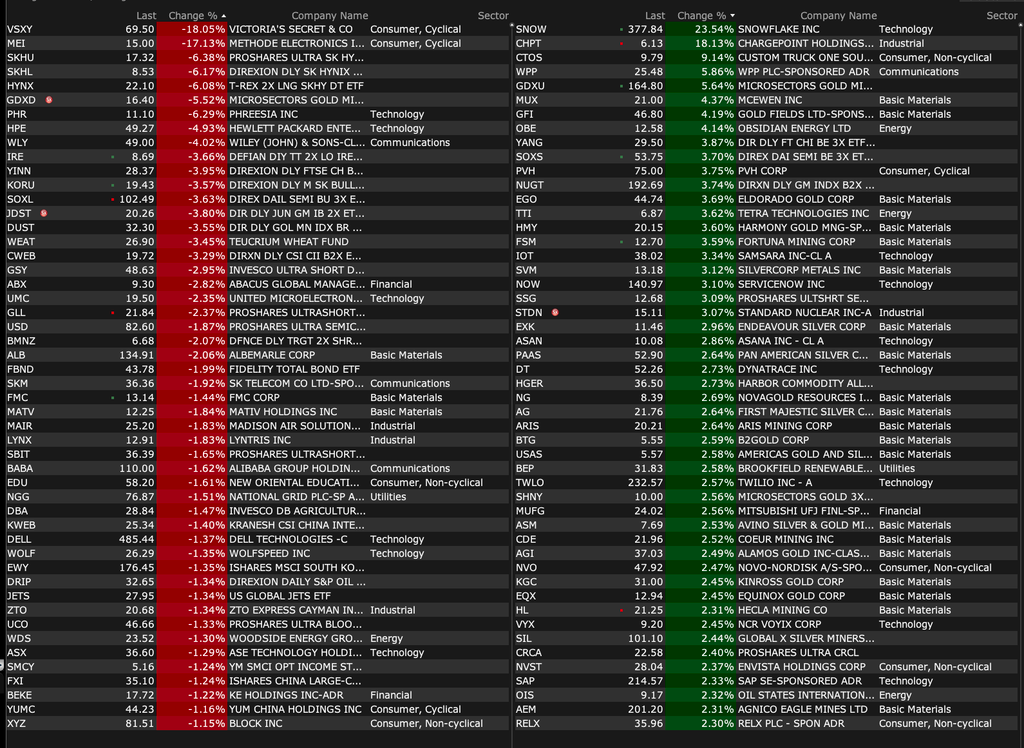
Microsoft resentments, earnings from HPE, Snowflake and Ciena, plus other headlines moving the market this morning.
Source: TipRanks:
We hear daily in the business media (principally from Perma Bulls) that investors are cautious – ergo a contrarian’s view that stocks could rally over the near term.
The reality is different than the narrative expressed by many.
From the estimable Liz Ann:
Positions: None.
rolf thrane
Peter Boockvar argues that inflation is stuck at 3%–4% and that there is little the Federal Reserve can do about it while the federal budget deficit remains at 7%–8% of GDP. I think he is wrong. Not about the the Fed, but about what the likely scenario that will play out is.
Position: None
Let’s open the Beige Book, look at employment and see why the jobs picture could be more fragile at the moment than realized.
Rick Friedman
I think it’s a big waste of real and mental capital to be buying cannabis stocks every day, while shorting pretty much everything else. Once a perma bear, always a perma bear.
stockrenter
What’s the saying? You can’t see the trees from the forest.
You lose sight of the rest of the Mkt & that prevents you from seing the many other opportunities, being so laser focused & mentally invested in 1 or 2 themes. From an institutional point of view there is no real $ commitment to the Pot names, they are all single digit names and a lot of funds can’t purchase sub $5 stubs. Also they are all Liquidity traps (aka Roach motels) you can get in but don’t have the Liquidity to get out. Any $ manager in his right mind knows that and why you never will see any real WS $ come into that sector …….If you’re in them recognize that & know what you’re playing for.
Dougie Kass
Rick:
It reflects my view that few stocks/sectors meet my standard of selection.
I am long 15 stocks and short 22 stocks in Seabreeze Partners, my hedge fund.
Moreover, I do a helluva lot of trading long and short rentals daily/ weekly – providing a menu of opportunity.
Position: None
Position: None