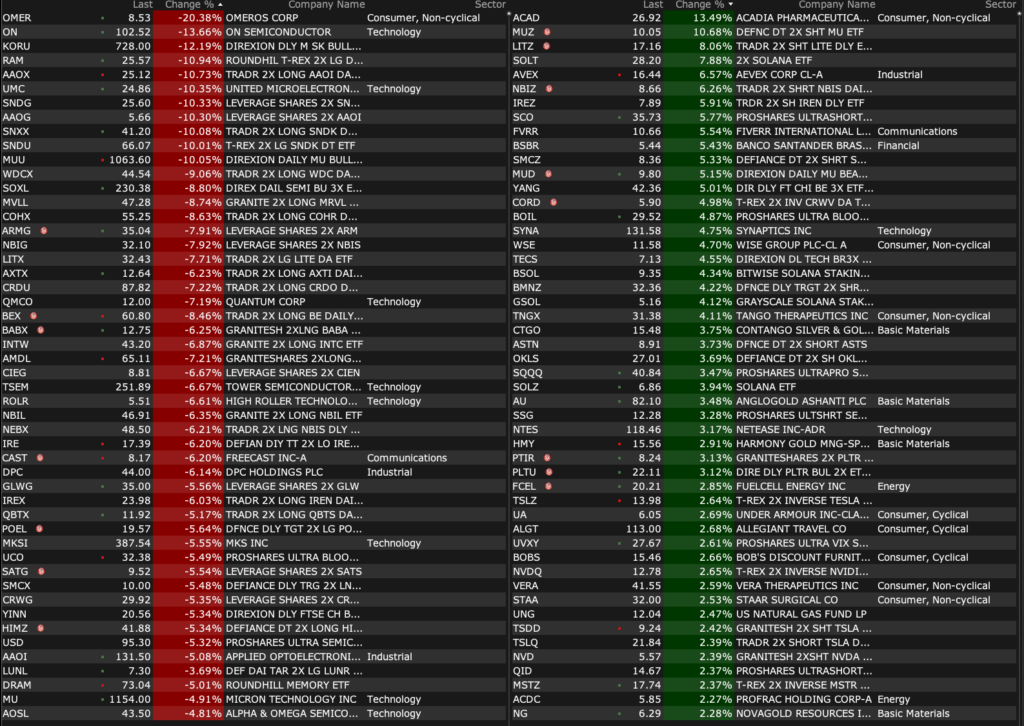
Charting the Percent Movers Before the Bell

Positions: None.
Positions: None.
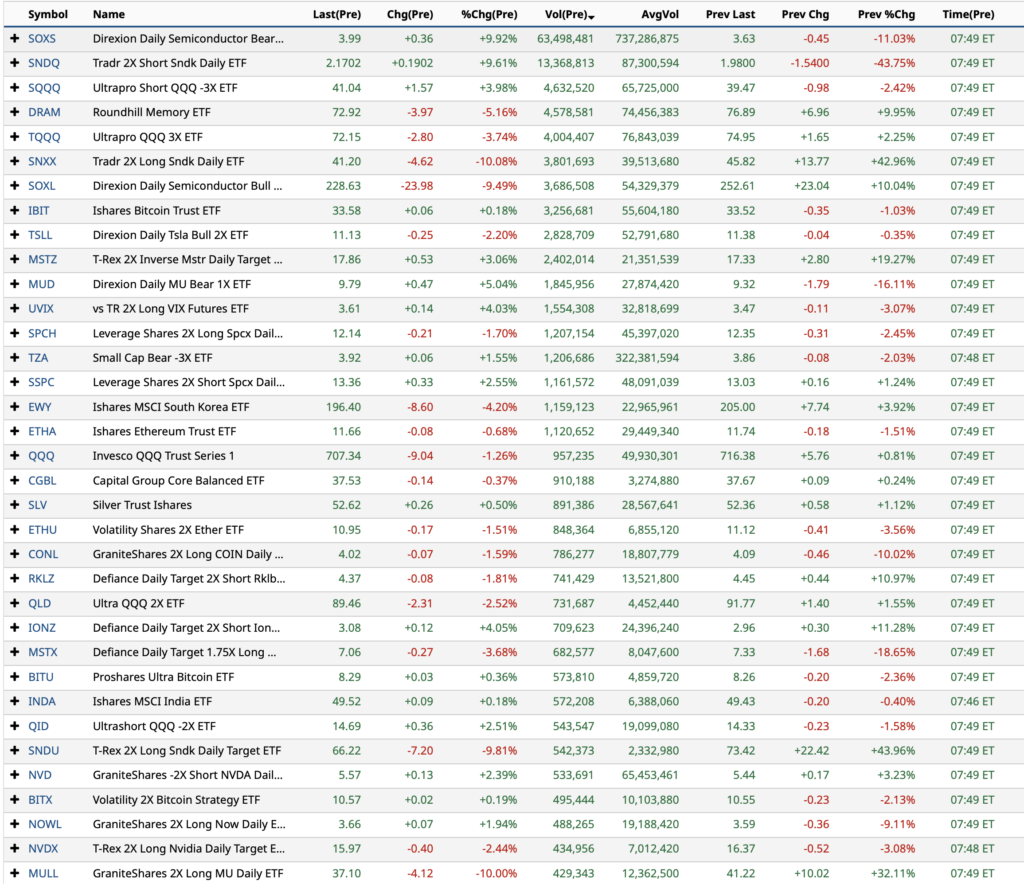
Chart from 7:49 a.m. ET.
Positions: None.
11:30 a.m.: Fed Bank of Minneapolis Kashkari (Voter) takes part in panel discussion at the 2026 Bankof Korea International Conference;
Sunday June 28: 12:35 p.m.: Fed Bank of Richmond President Thomas (Non-Voter) participates in”The Future of Economic Mobility: Built by Hand, Empowered by Opportunity” panel before the Aspen Ideas Festival hostedby the Aspen Institute, Aspen, CO (No text. No livestream)

Positions: None
Here’s why good economic data is weighing down stocks, Russell’s rebalancing will make winners and losers and the chart looks … perilous.
* Sail on Silver Girl
When you’re weary, feeling small,
When tears are in your eyes, I will dry them all;
I’m on your side. When times get rough
And friends just can’t be found,
Like a bridge over troubled water
I will lay me down.
Like a bridge over troubled water
I will lay me down.
Simon and Garfunkel, Bridge Over Troubled Water
Position: None
Semiconductor pricing power that drove Thursday’s rally is already being challenged.
The problem with shorting (or buying indices) late in the day or in the evening — as I often do — is that the fate of the general market’s opening is determined by the overall movement memory stocks.
And to predict/guess the opening price of $MU, $SNDK, $AMAT, $AMD, $INTC is a “fool’s errand.”
The market has no memory from day to day.
Position: None
You can makes this up:
Position: None
Added to these longs:
* $AMZN $227.69
* $GOOGL $341.53
Position: AMZN (S), GOOGL (S)
As I wrote yesterday, it is astonishing that the markets have, until recently, ignored the clear transformation from capital light to capital intensive occurring in most Mag 7 constituents.
Hyperscalers (“check writers”) vs. Chips (“check receivers”):
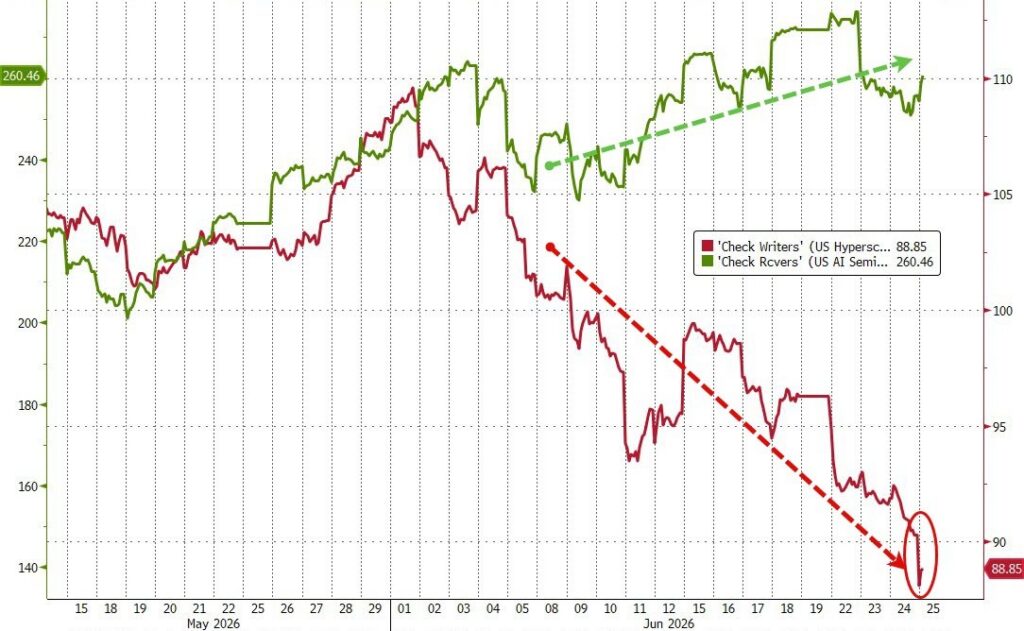
Remember the debates with some subscribers in the Comments Section in which my concerns were dismissed by glibly repeating AI responses to AI skepticism and/or by the notion and defaulting argument that the stocks are buys and holds (and investors should be unconcerned with shifting (fundamental) sands and weakening absolute and relative stock performance?
In contrast I have provided opinions of skeptics (Marcus et al) combined, especially in my first 100-150 “More Tales” with my own primary analysis (though recognizing that I am not a technology specialist). I did so because I thought there was value to a skeptical view — at a time in which such gross overweight of Mag 7 was an accepted condition in business media discussions and in portfolios writ large.
It was lonely living outside the herd and opposing “Group Stink” but look at the share price falls since:
$META $780 to $545
$AMZN $275 to $225
$MSFT $550 to $335
$GOOGL $410 to $330
I have been writing about elevated multiples (discounting only bullish outcomes), the evisceration of free cash flow at Amazon (AMZN), Microsoft (MSFT), Google (GOOGL), et al and the mismatch between immediate revenue recognition (at Nvidia ($NVDA)) and the deferral of costs (unrealistic and lengthy depreciation schedules) incurred by the hyperscalers, but it wasn’t until a few months ago that the markets began to catch on to the jig.
And, since then its been a developing period of absolute and relative performance for Mag 7. Now that the narrative has changed and many have accepted and are concerned about the multiple head winds I related in “More Tales” and in other columns — the stocks may have finally discounted these concerns. I purchased Google, Microsoft and Amazon over the last two trading sessions.
Here’s more:
Position: Long AMZN (S), GOOGL (S), MSFT (S)