The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
I mentioned in the Week Ahead that my expectations for the Fed today were for no major fireworks:
The Fed has never hiked with less than a 10% chance priced into markets, so we’re either going to get the biggest surprise to markets the Fed has ever delivered (on par with the surprise 75 basis point hike in 2022) or a relative snoozer that is already priced. It would be quite something though if they did hike (which is what BofA still calls for by the way) as it would not only be a huge hawkish surprise – a handful of days before the election – but it would also mean the long-standing “troika” at the top of the Fed in Chair-Vice Chair-NY Fed President (Warsh-Jefferson-Williams) had been busted wide open.
In terms of the rest of the meeting it is expected to also follow the “snoozer” pathway, particularly as there is no new Summary of Economic Projections and Chair Warsh has consistently been cutting back the length of the press conference and providing little information. Again, a change to that would be a big surprise. But the one thing that won’t surprise is dissents. The other regional Fed Presidents (Hammack in particular) have expressed a preference for continued rate hikes.
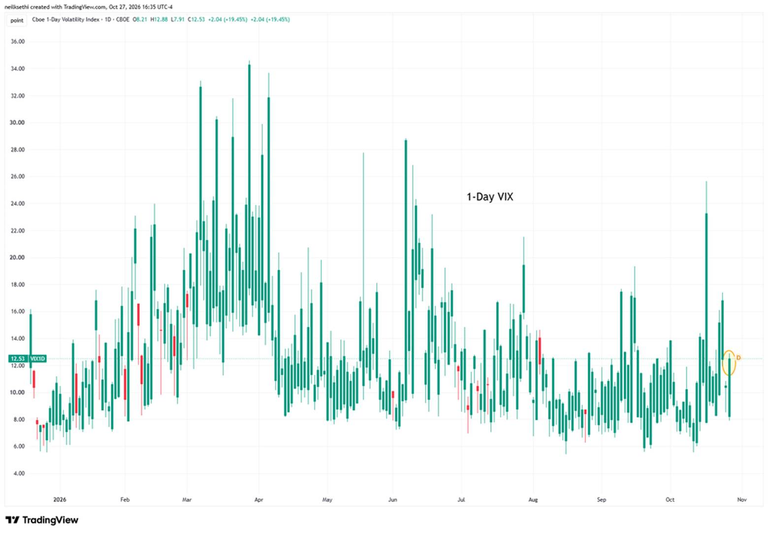
It seems markets are expecting a relative snoozer as well. I mentioned in last night’s update that “the 1-day VIX rose to 12.5 Tuesday, implying a move of about 0.79% for the S&P 500 today, pretty subdued.” I went ahead and looked back, and it’s the lowest pre-Fed day reading since April.
A wave of AI-related deals sent semiconductor shares soaring, helping the Nasdaq rally while investors prepared for the Fed and crucial earnings from Microsoft and Google parent Alphabet.
Another selloff in AI names broadened to encompass most of Tech, sending the Nasdaq-100 to its worst week since April 2025. Five sectors though would finish the week up 2% or more, as 30-year Treasury yields fell the most since April 2025.