Meta and Broadcom-Anthropic Financing Deals: 8 Key Items Shaping the Stock Market Tuesday

Earnings from Boeing and Welltower, prepping for Paccar’s results plus other headlines moving the market this morning.
Earnings from Boeing and Welltower, prepping for Paccar’s results plus other headlines moving the market this morning.
Super Micro Computer crushes expectations while United Airlines and Alaska Airlines confirm energy input concerns. Those and other headlines are moving the market this morning.
Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
From my evening update:
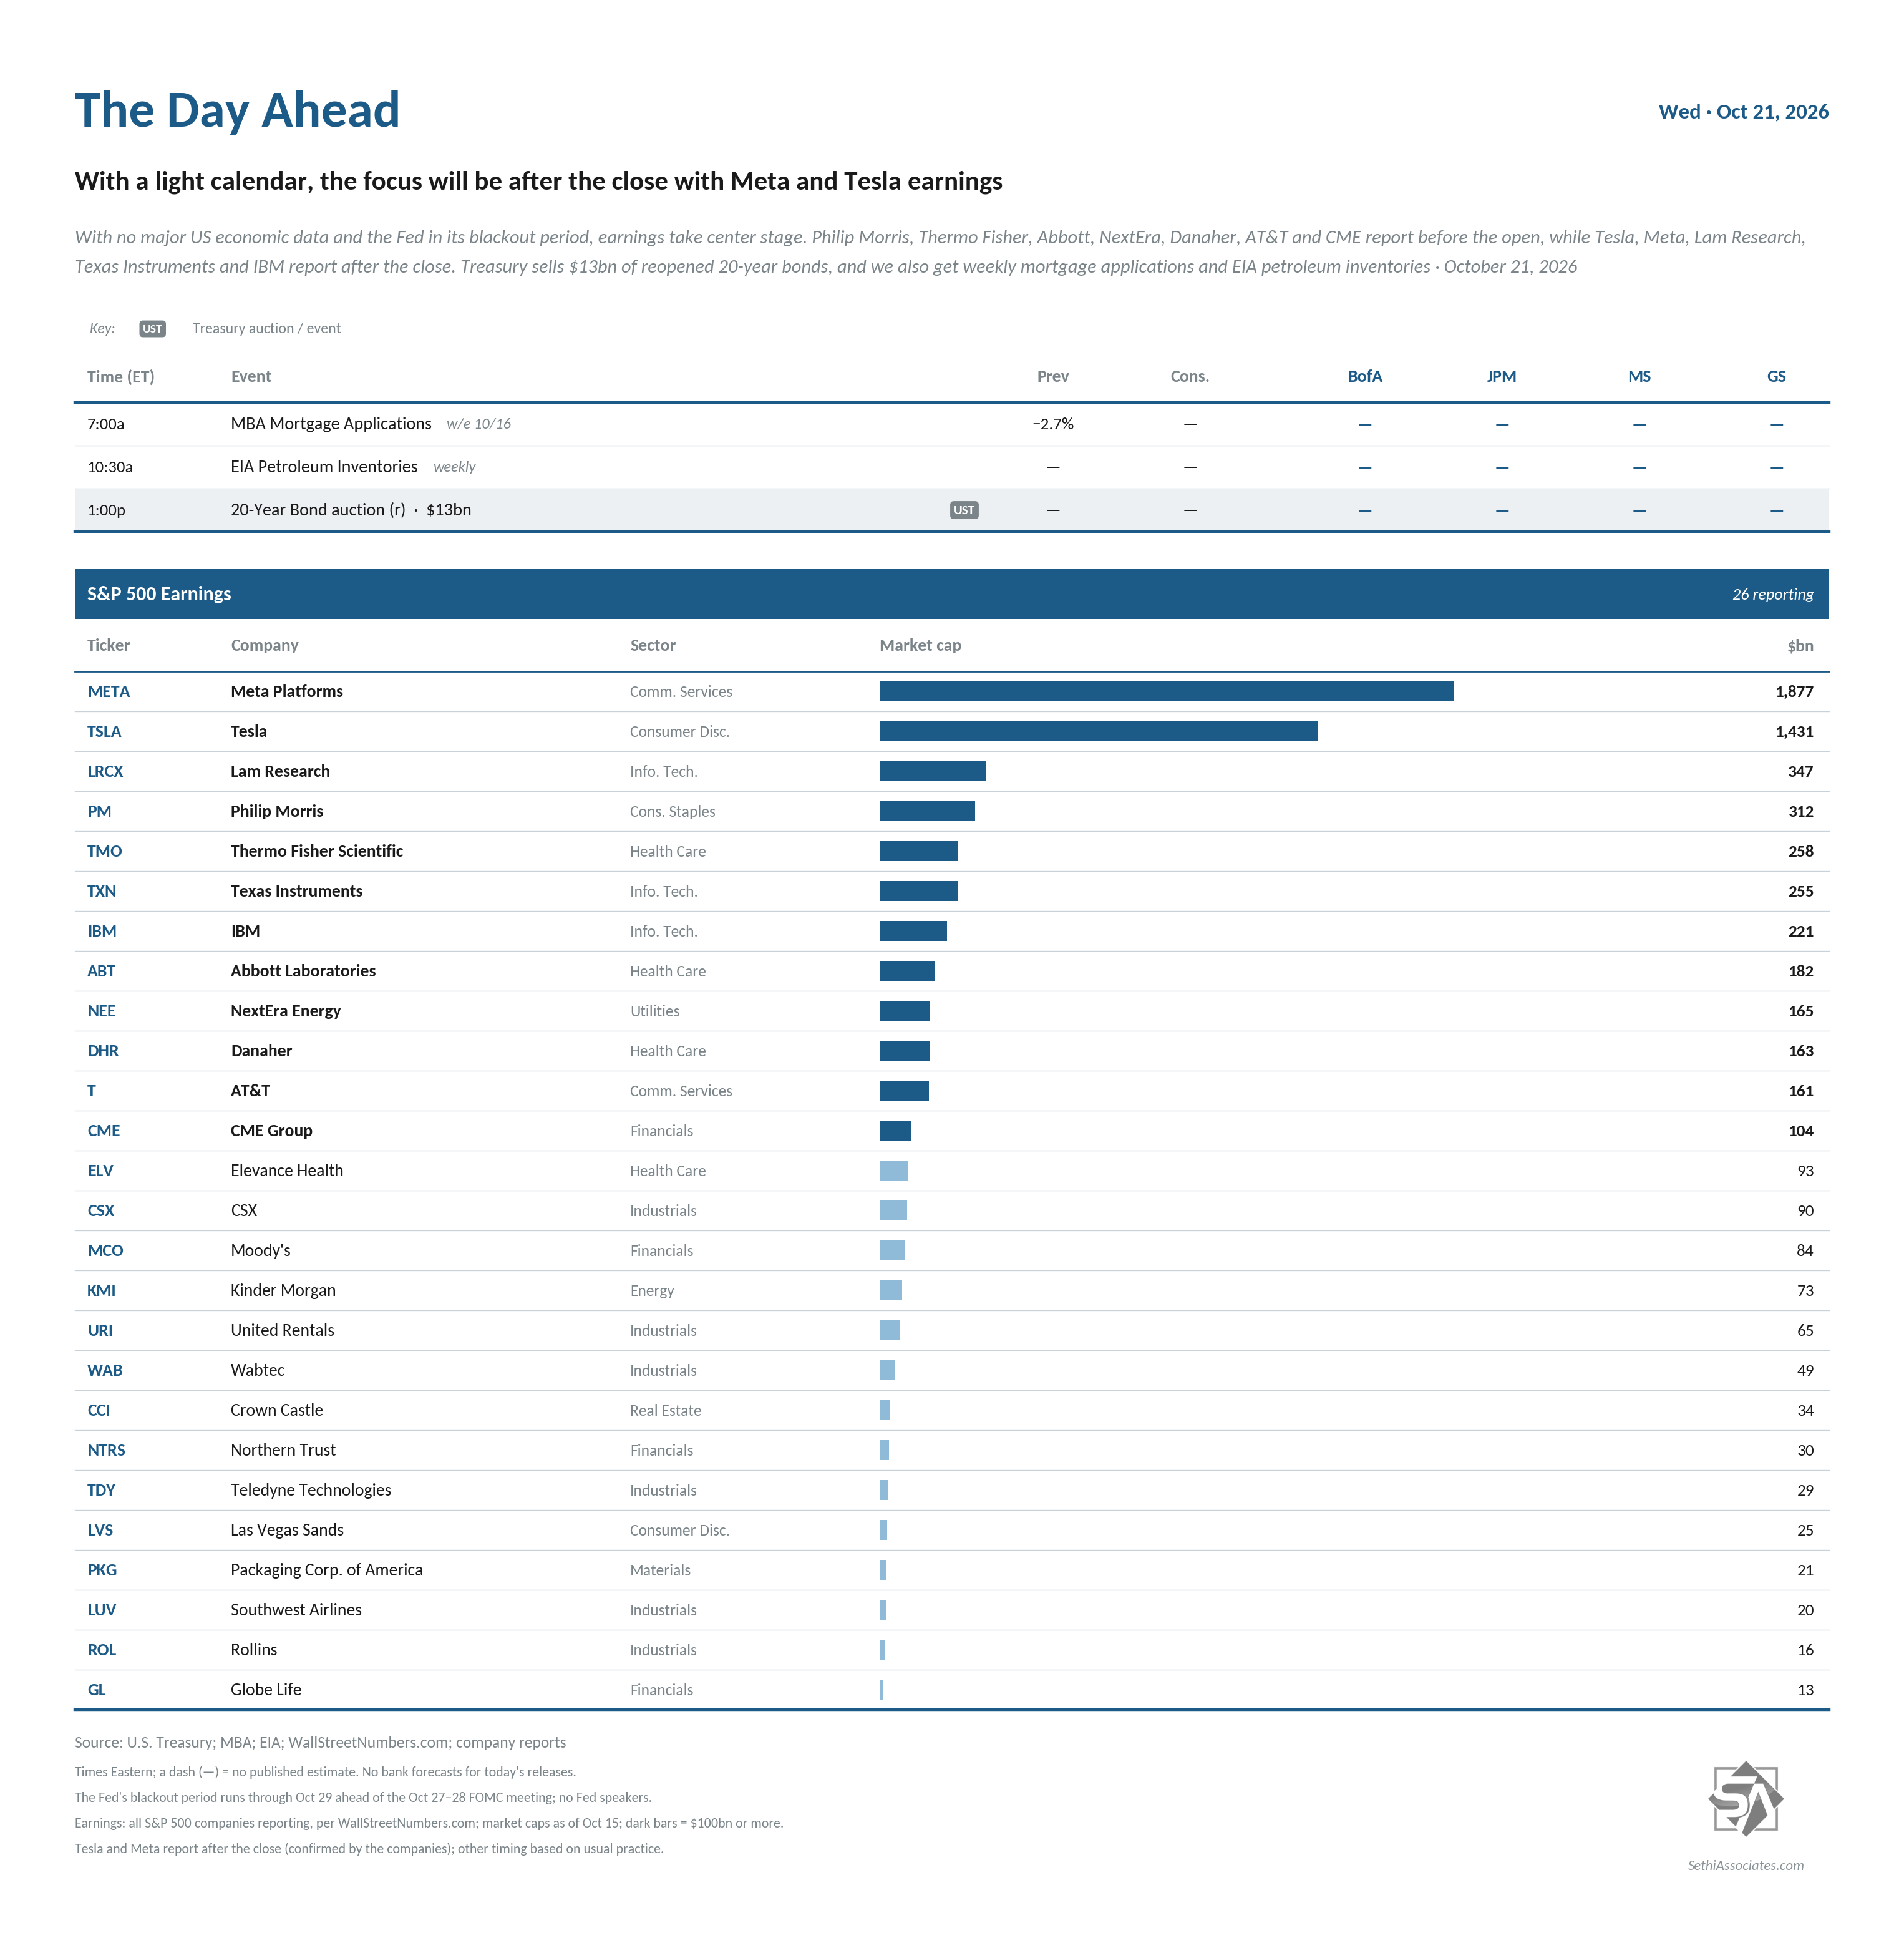
US economic data is light Wednesday, with only weekly mortgage applications and EIA petroleum inventories.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions resume with a $13B 20-year bond reopening.
Q3 earnings season continues with 26 S&P 500 components including a number of AI-related names: Meta Platforms ($META), Tesla ($TSLA), Lam Research ($LRCX), Philip Morris ($PM), Thermo Fisher Scientific ($TMO), Texas Instruments ($TXN), IBM ($IBM), Abbott Laboratories ($ABT), NextEra Energy ($NEE), Danaher ($DHR), AT&T ($T), CME Group ($CME), Elevance Health ($ELV), CSX ($CSX), Moody’s ($MCO), Kinder Morgan ($KMI), United Rentals ($URI), Wabtec ($WAB), Crown Castle ($CCI), Northern Trust ($NTRS), Teledyne Technologies ($TDY), Las Vegas Sands ($LVS), Packaging Corp. of America ($PKG), Southwest Airlines ($LUV), Rollins ($ROL) and Globe Life ($GL).
Ex-US highlights are UK September CPI, PPI, RPI, public finances, August house price index, Japan September trade balance, New Zealand Q3 CPI.
Easing long-term yields and oil prices lifted the Russell 2000 to its best day since early August and saw 9 of 11 S&P 500 sectors higher, even as weakness in Tech dragged on the cap-weighted index.
September housing starts miss, but there is more to the margin pressure story.
We raised cash early, put some back to work late in the month, locked in gains on Meta and kicked off our quarterly EPS All-Stars reconstitution.
During the week of challenging developments, we refreshed out shopping list, exited one holding and added to four others.
Perhaps we’ll get a change in direction following the Fed’s press conference tomorrow. Until then, this market feels complacent, which is not productive.
Duration remains a key, but year-over-year increases are flashing a yellow light