Cybersecurity Names Won’t Stay Down for Long: 8 Key Items Shaping the Stock Market Thursday


Qualcomm’s handset slump, oil questions, and other headlines moving the market this morning.
Qualcomm’s handset slump, oil questions, and other headlines moving the market this morning.
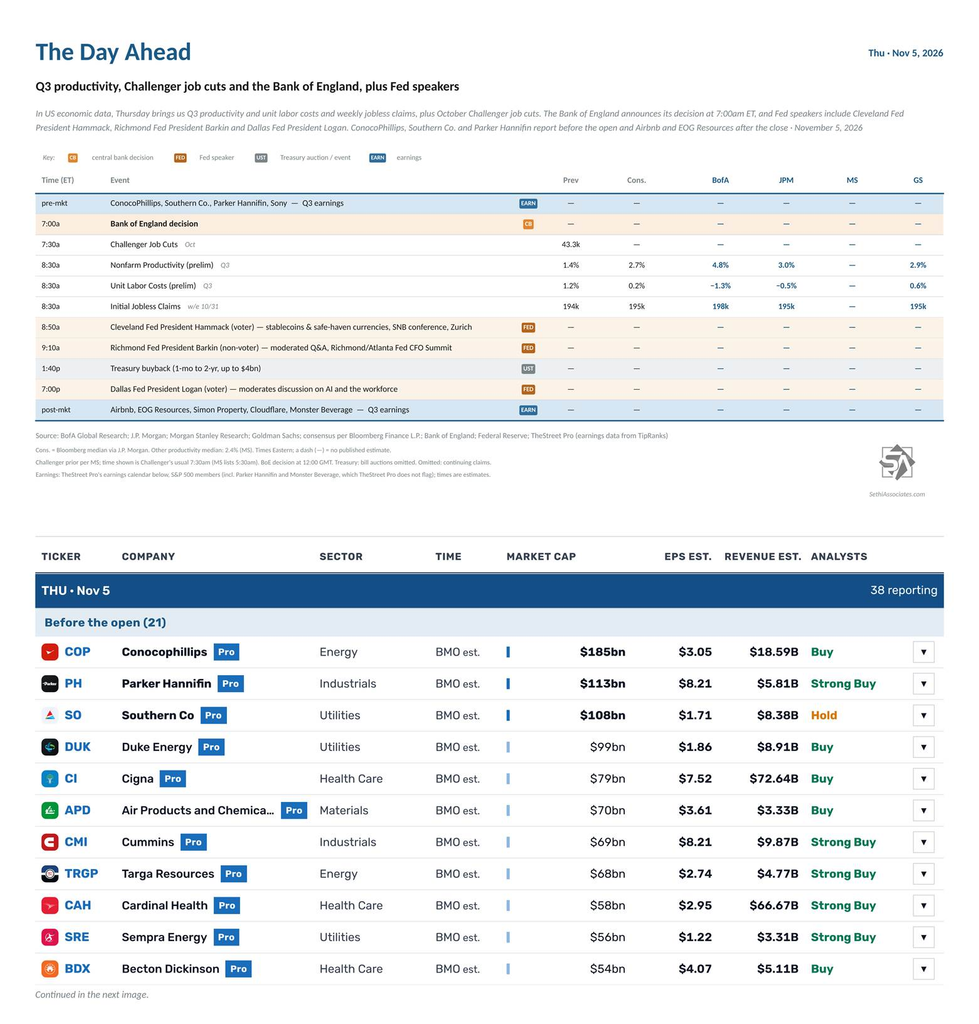
In U.S. economic data, Thursday brings us Q3 productivity and unit labor costs, plus October Challenger job cuts/hires. We’ll also get the weekly unemployment claims.
Cleveland Fed President Hammack (voter) speaks on stablecoins and safe-haven currencies in Zurich at 8:50am ET, Richmond Fed President Barkin (non-voter) participates in a moderated Q&A at 9:10am ET, and Dallas Fed President Logan (voter) moderates a discussion on AI and the workforce at 7pm ET.
The Bank of England announces its decision at 7am ET.
There are no non-Bill (>1yr in maturity) U.S. Treasury auctions, but Treasury holds a buyback of up to $4 billion of 1-month to 2-year securities at 1:40pm ET.
Also, a White House committee is scheduled to hold a closed hearing on allegations against Fed Governor Lisa Cook and whether there’s cause for her removal, per Bloomberg (via @C_Barraud).
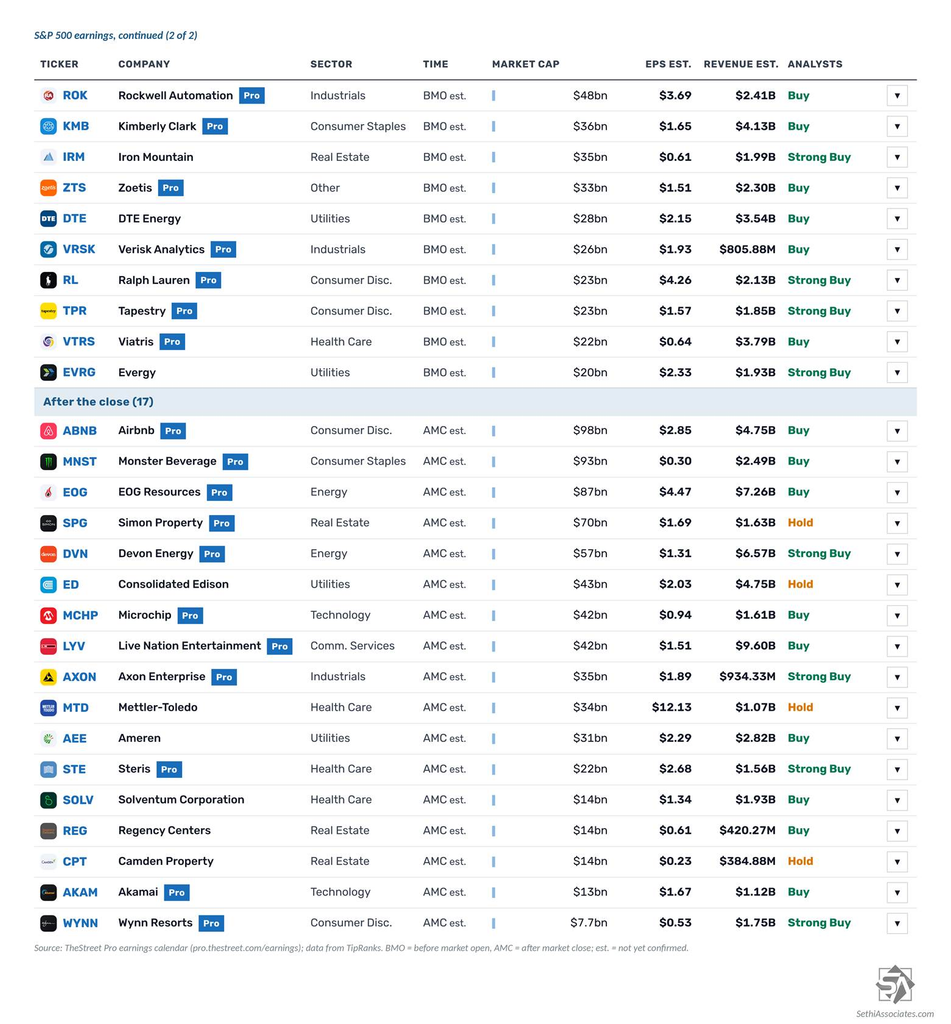
38 S&P 500 components report, three of them with market caps over $100bn:
Before the open: ConocoPhillips ($COP), Parker Hannifin ($PH), Southern Co. ($SO), Duke Energy ($DUK), Cigna ($CI), Air Products ($APD), Cummins ($CMI), Targa Resources ($TRGP), Cardinal Health ($CAH), Sempra ($SRE), Becton Dickinson ($BDX), Rockwell Automation ($ROK), Kimberly-Clark ($KMB), Iron Mountain ($IRM), Zoetis ($ZTS), DTE Energy ($DTE), Verisk Analytics ($VRSK), Ralph Lauren ($RL), Tapestry ($TPR), Viatris ($VTRS) and Evergy ($EVRG)
After the close: Airbnb ($ABNB), Monster Beverage ($MNST), EOG Resources ($EOG), Simon Property ($SPG), Devon Energy ($DVN), Consolidated Edison ($ED), Microchip Technology ($MCHP), Live Nation ($LYV), Axon ($AXON), Mettler-Toledo ($MTD), Ameren ($AEE), Steris ($STE), Solventum ($SOLV), Regency Centers ($REG), Camden Property ($CPT), Akamai ($AKAM) and Wynn Resorts ($WYNN)
Outside the S&P 500, Sony ($SONY), National Grid ($NGG) and ArcelorMittal ($MT) report before the open, Cloudflare ($NET) after the close, and Toyota ($TM) at a time not yet announced.
Ex-U.S. highlights include U.K. October new car registrations and construction PMI, Japan September labor cash earnings, Germany September factory orders and October construction PMI, France September industrial production, Italy September retail sales, Eurozone September PPI and Sweden October CPI.
Besides the BoE, Norges Bank, Malaysia and Mexico announce rate decisions, ECB President Lagarde speaks, the ECB opens its annual money markets conference, Canada releases its 2026 federal budget and the China International Import Expo begins in Shanghai.
A Democratic sweep of Congress supercharged the rotation trade, with hyperscalers joining a rally that lifted almost everything except semiconductors and AI power and data center names.
Trump “low-keying” it with Iran, Meta’s new AI model and other headlines moving stocks this morning.
Let’s sort through what those Friday jobs numbers mean for rate-hike chatter, what’s happening (or not happening) on the Strait, and why Trump is in a tough spot.