Cybersecurity Names Won’t Stay Down for Long: 8 Key Items Shaping the Stock Market Thursday


Qualcomm’s handset slump, oil questions, and other headlines moving the market this morning.
Qualcomm’s handset slump, oil questions, and other headlines moving the market this morning.
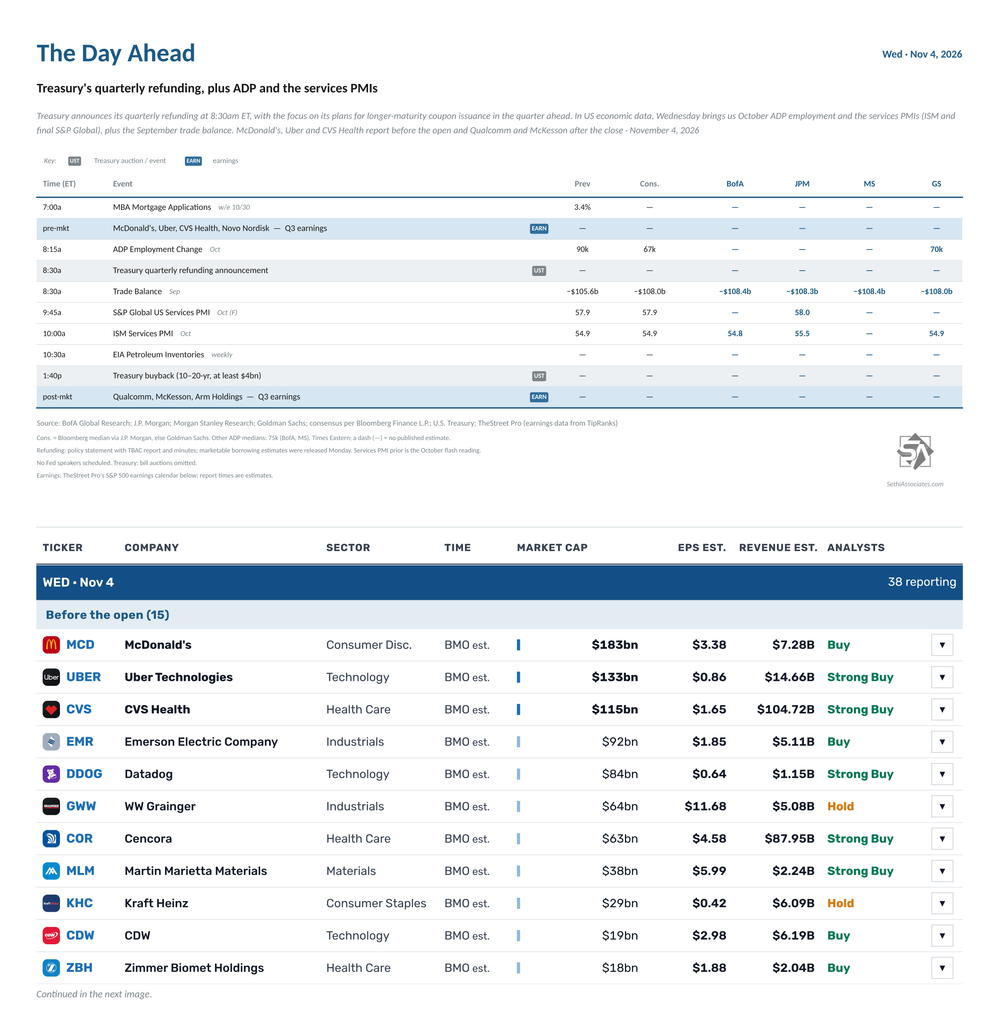
In US economic data, Wednesday brings us October ADP private employment growth and the services PMIs (ISM and final S&P Global), plus the September trade balance. We’ll also get weekly MBA mortgage applications and EIA petroleum inventories.
There are no Fed speakers scheduled.
There are no non-Bill (>1yr in maturity) US Treasury auctions, but Treasury announces its quarterly refunding at 8:30am ET, with the focus on its plans for longer-maturity coupon issuance in the quarter ahead. It also holds a buyback of 10- to 20-year securities in the afternoon.
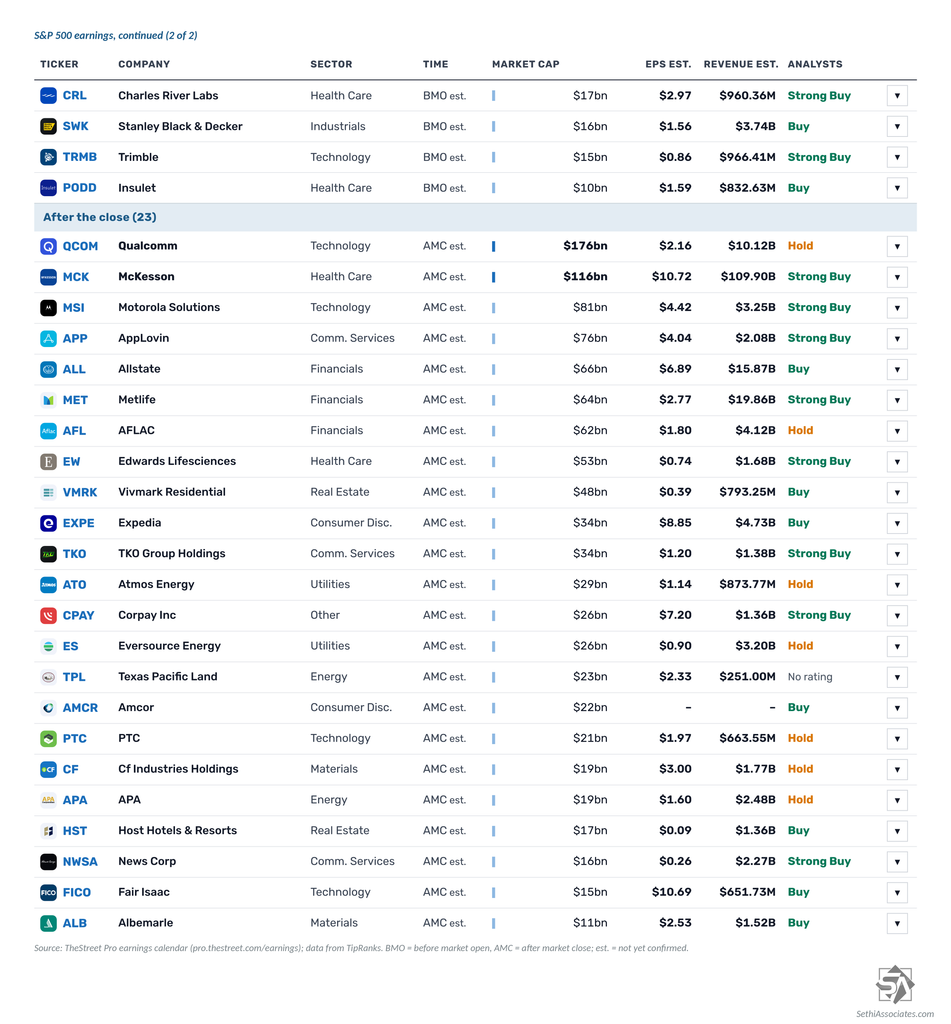
38 S&P 500 components report, five of them with market caps over $100B:
Before the open: McDonald’s ($MCD), Uber ($UBER), CVS Health ($CVS), Emerson Electric ($EMR), Datadog ($DDOG), W.W. Grainger ($GWW), Cencora ($COR), Martin Marietta Materials ($MLM), Kraft Heinz ($KHC), CDW ($CDW), Zimmer Biomet ($ZBH), Charles River Laboratories ($CRL), Stanley Black & Decker ($SWK), Trimble ($TRMB) and Insulet ($PODD)
After the close: Qualcomm ($QCOM), McKesson ($MCK), Motorola Solutions ($MSI), AppLovin ($APP), Allstate ($ALL), MetLife ($MET), Aflac ($AFL), Edwards Lifesciences ($EW), Vivmark Residential ($VMRK), Expedia ($EXPE), TKO Group ($TKO), Atmos Energy ($ATO), Corpay ($CPAY), Eversource Energy ($ES), Texas Pacific Land ($TPL), Amcor ($AMCR), PTC ($PTC), CF Industries ($CF), APA ($APA), Host Hotels & Resorts ($HST), News Corp ($NWSA), Fair Isaac ($FICO) and Albemarle ($ALB)
Outside the S&P 500, Novo Nordisk ($NVO) reports before the open and Arm Holdings ($ARM) and MercadoLibre ($MELI) after the close.
Also, opening arguments are scheduled in a Los Angeles trial over claims that Meta ($META) and Snap ($SNAP) designed their platforms to be addictive and harmful to young users, per Bloomberg.
Ex-US highlights include the final October services PMIs (including China’s RatingDog services PMI), Eurozone October CPI, Spain’s October unemployment rate, UK October official reserves changes and Canada’s September trade balance. There are rate decisions from Sweden’s Riksbank, Poland and Brazil, the ECB releases its wage tracker, ECB Chief Economist Lane and Bank of France Governor Moulin speak, and the Bank of Japan releases the minutes of its September meeting.
Semiconductors led a rebound that broke the S&P 500’s three-day losing streak, but the average stock fell.
Let’s talk hyperscaler earnings — and why cloud backlogs matter more than ever.
Fresh Federal program wins build on recent public safety ones
Let’s break down the latest earnings and guidance, why the stock’s moving lower today and our plan going forward.
ISM’s Inflation data, SpaceX spending and Foxconn’s July revenue among the headlines shaping the market today/