Chart of the Day: Can Microsoft Save the Magnificent Seven?

Earnings are out this week and expectations are quite high.
Earnings are out this week and expectations are quite high.
Let’s talk hyperscaler earnings — and why cloud backlogs matter more than ever.
Anthropic just filed a key financial doc, SpaceX reported earnings, and some investors are betting against Elon. Here’s what all that means for my position.
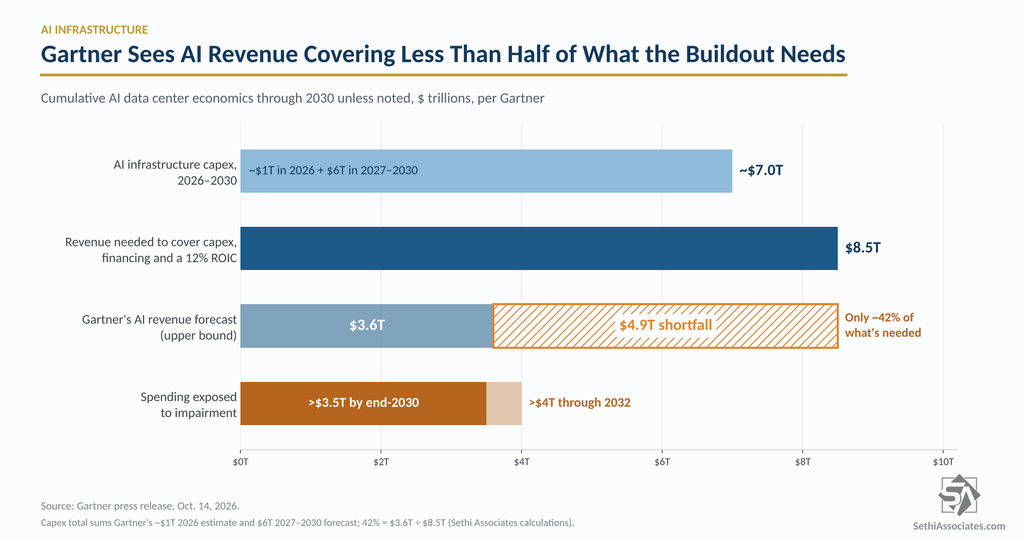
Also catching headlines today: Bloomberg picked up a Gartner analysis from earlier this month showing a yawning gap between its forecasts for AI spending and AI revenue.
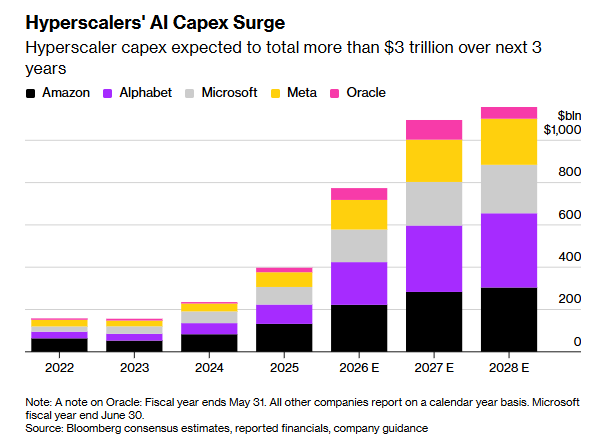
Gartner expects AI providers to spend nearly $1 trillion on AI infrastructure this year and another $6 trillion from 2027 through 2030.
Covering that spending, plus financing costs and a 12% return on invested capital, would take a cumulative $8.5 trillion in revenue through 2030. Gartner though forecasts no more than $3.6 trillion in enterprise and consumer AI revenue attributable to those data centers, about 42% of what’s needed. That leaves a roughly $4.9 trillion revenue gap, and more than $3.5 trillion of AI infrastructure spending exposed to impairment by the end of 2030, rising to more than $4 trillion through 2032. Gartner doesn’t expect that 12% return to be reached until the end of 2032 at the earliest.
The cloud math is no kinder. Gartner sees spending on AI-optimized infrastructure-as-a-service (IaaS) growing from $66 billion in 2027 to $174 billion in 2030. “The growth in spending on AI-optimized IaaS will be too low for most AI compute providers to recover their AI investments before the current generation of AI semiconductors is replaced,” said Gartner analyst Will Sommer. By my math, even that 2030 figure is only about 12% of the roughly $1.5 trillion a year Gartner expects AI providers to spend on infrastructure from 2027 through 2030.
Neoclouds are the most exposed. As Gartner notes, Microsoft ($MSFT), Alphabet ($GOOGL) and Amazon ($AMZN) have diversified revenue that could sustain AI spending for years, while specialists like CoreWeave ($CRWV) and Nebius Group ($NBIS) need returns soon.
Gartner predicts more than 80% of neocloud providers will cease independent operations by 2030. “All of them want to be the full-stack. They can’t all be,” Sommer told Bloomberg. “For every dollar that’s spent on compute, only a fraction of that is going to the owners of compute.”
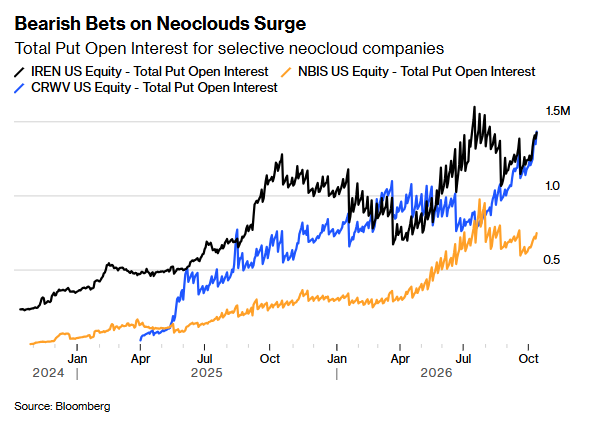
The options market is starting to brace for that. Put open interest in CoreWeave, Nebius and IREN ($IREN) has climbed sharply this year, per Bloomberg.
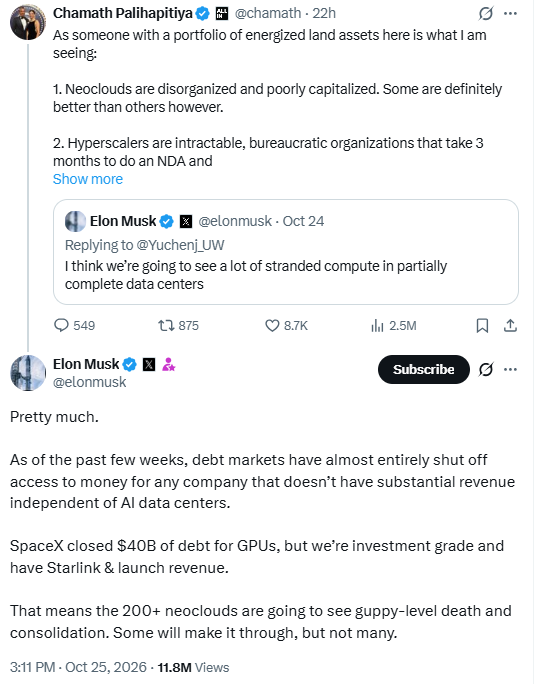
“Debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers…That means the 200+ neoclouds are going to see guppy-level death and consolidation.” —SpaceX CEO Elon Musk in a tweet yesterday, in which he also said his company had secured $40 billion in debt financing.
While everyone will be focused on earnings from Alphabet ($GOOGL), Microsoft ($MSFT) and Amazon ($AMZN) this week, a Wall Street Journal analysis shows they aren’t expected to contribute enough to third-quarter S&P 500 earnings growth to get their own callout in terms of needle-movers. That’s quite a change from the second-quarter season, when their “other income” was one of the biggest sources of upside surprise.
In contrast, Nvidia ($NVDA) and Micron Technology ($MU) alone account for about a third of the nearly 30% year-over-year growth in S&P 500 third-quarter earnings. That figure blends actual results from companies that have reported with estimates for those that haven’t. Just 10 companies account for nearly two-thirds of that growth. Along with Nvidia and Micron, they are Broadcom ($AVGO), Exxon Mobil ($XOM), EchoStar ($SATS), Sandisk ($SNDK), Marathon Petroleum ($MPC), Meta Platforms ($META), Chevron ($CVX) and Valero Energy ($VLO).

Big AI and data center focused earnings, SpaceX’s $40 billion capital raise, and other headlines moving the market this morning.
With the Fed, Microsoft, Alphabet and Amazon on deck, the AI-related spending debate comes to a head.
Let’s scan through the headlines for the stories of the week that speak to our Pro Portfolio holdings.
Brent topped $116 and stocks pulled back on fears of renewed U.S.-Iran hostilities after the midterm elections. For the week, small caps led with the Russell 2000 up 2% while the S&P 500 and Nasdaq slipped.
We added to six holdings, and upgraded and lifted a price target on another as favorable AI data conflicted with market emotion.