The Crude Conundrum

Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
From my evening update:
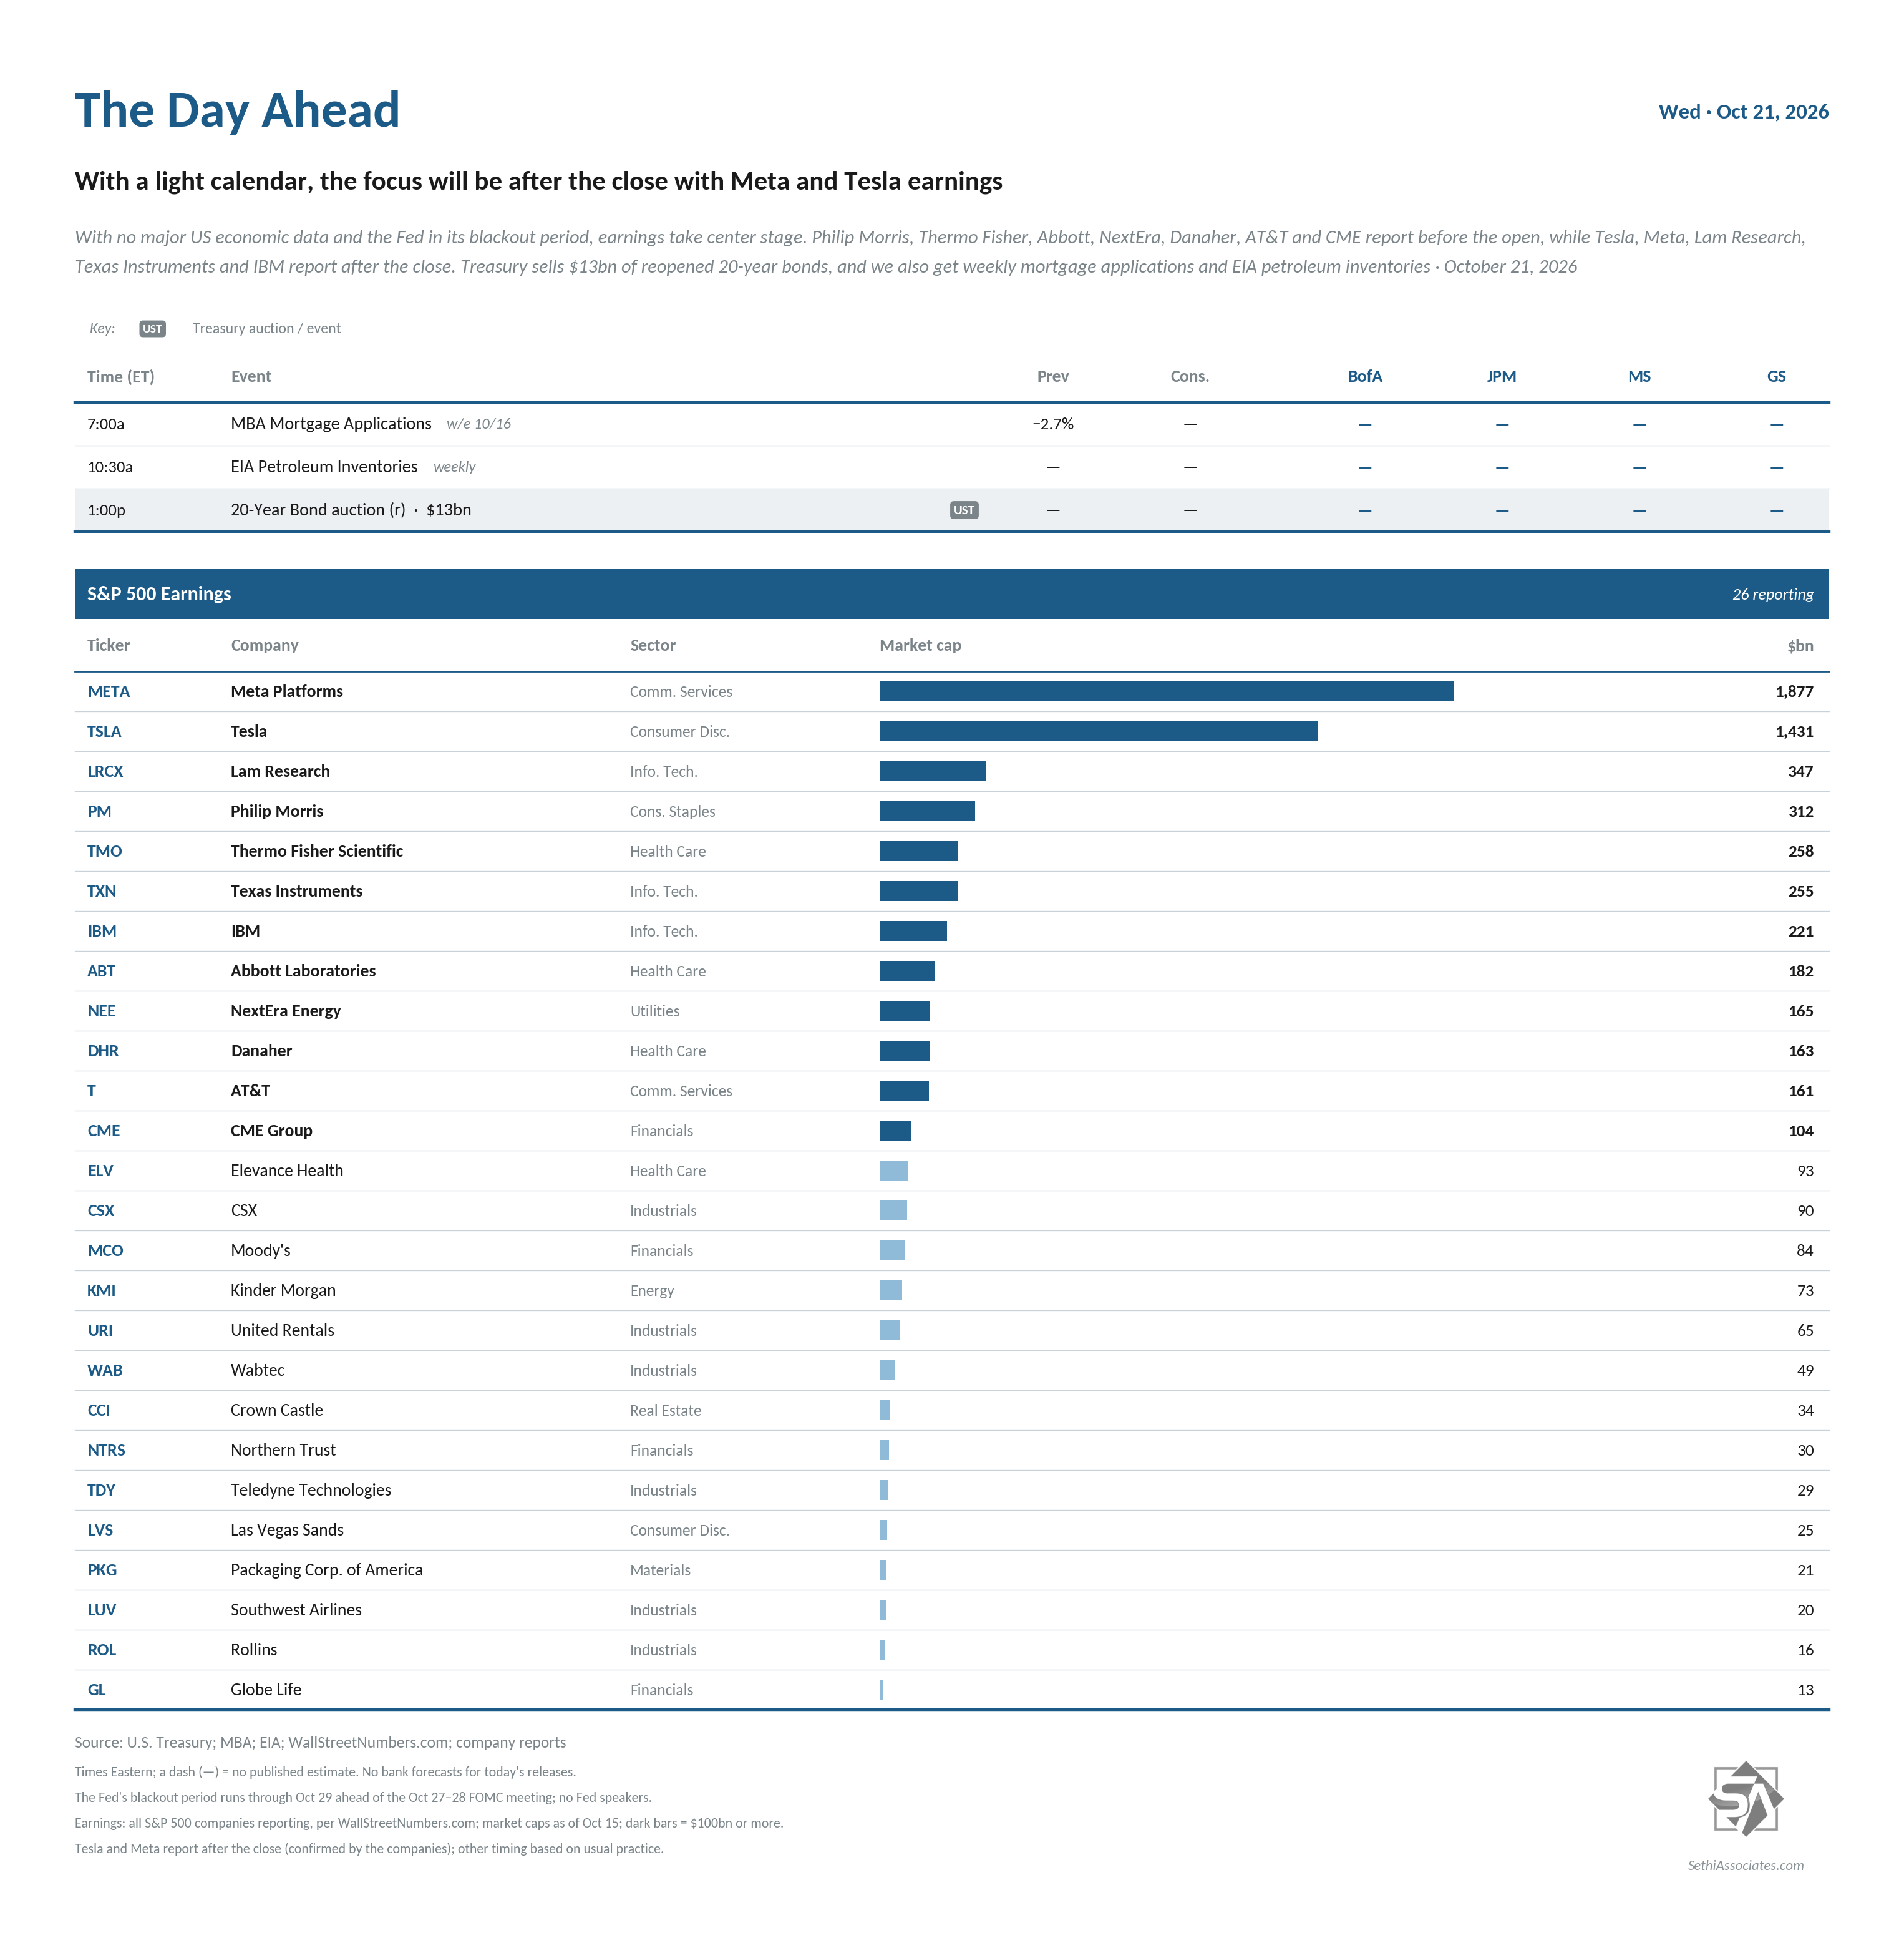
US economic data is light Wednesday, with only weekly mortgage applications and EIA petroleum inventories.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions resume with a $13B 20-year bond reopening.
Q3 earnings season continues with 26 S&P 500 components including a number of AI-related names: Meta Platforms ($META), Tesla ($TSLA), Lam Research ($LRCX), Philip Morris ($PM), Thermo Fisher Scientific ($TMO), Texas Instruments ($TXN), IBM ($IBM), Abbott Laboratories ($ABT), NextEra Energy ($NEE), Danaher ($DHR), AT&T ($T), CME Group ($CME), Elevance Health ($ELV), CSX ($CSX), Moody’s ($MCO), Kinder Morgan ($KMI), United Rentals ($URI), Wabtec ($WAB), Crown Castle ($CCI), Northern Trust ($NTRS), Teledyne Technologies ($TDY), Las Vegas Sands ($LVS), Packaging Corp. of America ($PKG), Southwest Airlines ($LUV), Rollins ($ROL) and Globe Life ($GL).
Ex-US highlights are UK September CPI, PPI, RPI, public finances, August house price index, Japan September trade balance, New Zealand Q3 CPI.
Easing long-term yields and oil prices lifted the Russell 2000 to its best day since early August and saw 9 of 11 S&P 500 sectors higher, even as weakness in Tech dragged on the cap-weighted index.