FOMC Holds Rates Steady; Governor Cook Dissents

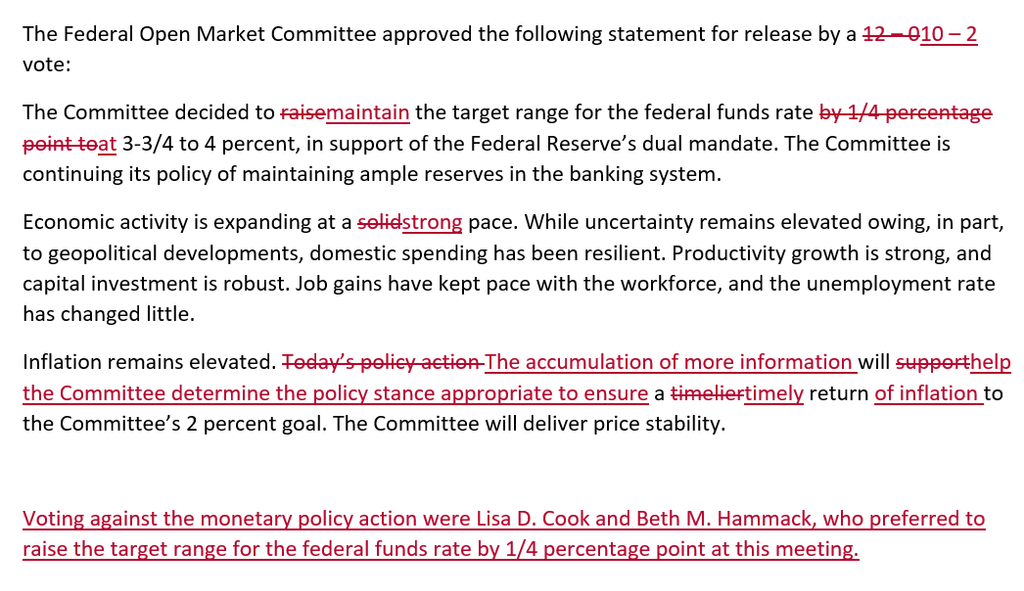
As expected by most, the Fed held rates unchanged this afternoon, reiterating their commitment to bringing down inflation, but not offering a clear signal on December.
The statement remained short but upgraded the assessment of the economy to a “strong pace” from a “solid” one in September.
The committee went on to say that the the “accumulation of more information will help the committee determine the policy stance appropriate to ensure a timely return of inflation to the committee’s 2% goal.”
There was one big surprise, though. I mentioned in my preview there would likely be dissents, particularly from Cleveland Fed President Hammack, who did dissent, but there was also a dissent from Governor Lisa Cook, her first dissent since becoming a Board member in 2022. As you may recall, President Trump has recently renewed efforts to remove Cook from the Fed, following an earlier effort blocked by the Supreme Court.
From the press conference
Warsh starts on economic growth, noting the strong numbers fueled by consumer spending and business investment. Unemployment rate down from a year ago. Says later that the investment boom is “broadening”.
“Not willing to call financial conditions tight” but they have moved “in the direction of achieving a longer and more durable period of economic growth”.
There will be eight meetings next year, but one will focus “exclusively on broad monetary policy strategy with neither a vote on the Federal Funds rate nor a policy statement anticipated” and sees that growing to two meetings on strategy and six on policy in 2028.
Interesting moment at the presser: before answering a question from Colby Smith of The New York Times, Warsh said, “I have been reading your stories this week.” Smith was seen by some as an outlet the Fed used to signal coming moves during blackout periods when she covered the Fed for the Financial Times. The remark could raise her standing as a potential “Fed whisperer,” a title long held by The Wall Street Journal’s Nick Timiraos. Timiraos seems to have lost some favor after his report that Governor Waller wasn’t a fan of Warsh’s task forces which drew harsh criticism from Treasury Secretary Scott Bessent.
Warsh on the impact of interest rates on the AI buildout: “On the thrust of your question of — with respect to the new technology and this investment surge — do interest rates matter? I believe they do. And I don’t believe that they’re somehow divorced from the rest of the economy.”
Post-FOMC rate hike expectations are little changed:
- December: the odds of a hike are 83%, from 84% yesterday.
- Hikes priced by Dec ‘26: +21bps (about 0.8 hikes), from +22bps.
- Hikes priced by Dec ‘27: +74bps (about 3.0 hikes), from +75bps.