The rotation out of Tech continued last week. Now a packed week headlined by Apple on Monday, Tuesday’s midterm elections, and Friday’s jobs report test a market with thin gamma and CTAs near their sell triggers.
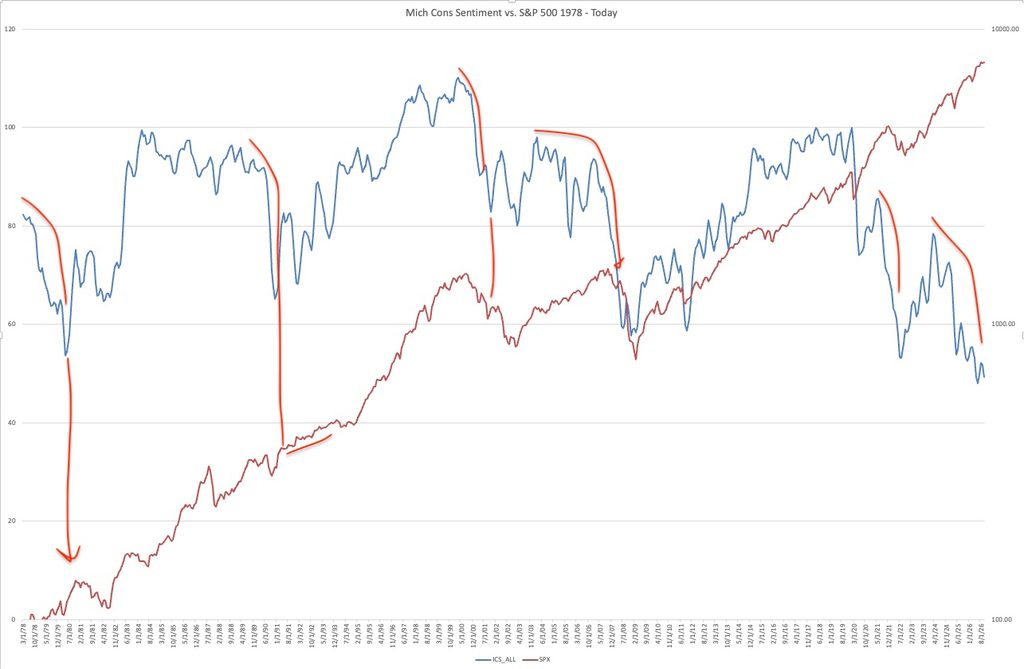
Neil’s note earlier on Michigan Consumer Sentiment dropping to lows (although beating expectations) got me thinking about research I did back in my Fear & Greed days. Back then, I noticed that lows in Consumer Sentiment happened around lows in the S&P 500.
Here’s the thing. It’s not a timing tool. And you might even say that Consumer Sentiment leads stocks. So, where are we now?
The red line is the S&P 500 and the blue is Mich Consumer Sentiment. What I see is a relationship between the two and according to my stats, Sentiment explains 40% of the movement in the S&P 500. Now, this is a simplistic analysis, but it has some merit.
Basically, consumers lose faith in the economy, and then stocks fall. Consumers have no faith in the economy right now, and haven’t for years! (This isn’t a political statement.) I probably should have used RSP for this analysis instead of S&P 500, but it doesn’t go back as far.
So, the stock market may continue to go up, but risk is only increasing.
Trend is your friend, except at the ends, where it bends.
The megacap growth sectors went from worst (Friday) to first (Monday) as chipmakers snapped an eight-session losing streak, but rising Treasury yields left seven sectors, the Dow Jones Industrial Average, and the equal-weight S&P 500 lower.
Another selloff in AI names broadened to encompass most of Tech, sending the Nasdaq-100 to its worst week since April 2025. Five sectors though would finish the week up 2% or more, as 30-year Treasury yields fell the most since April 2025.