The Week Ahead: The Rotation Continues

AI worries are pressuring Tech and sending yields lower as we embark on a heavy earnings week including several names in the cross-hairs.
AI worries are pressuring Tech and sending yields lower as we embark on a heavy earnings week including several names in the cross-hairs.
Setting a stop is the most important task in trading. It’s also the hardest.
Another selloff in AI names broadened to encompass most of Tech, sending the Nasdaq-100 to its worst week since April 2025. Five sectors though would finish the week up 2% or more, as 30-year Treasury yields fell the most since April 2025.
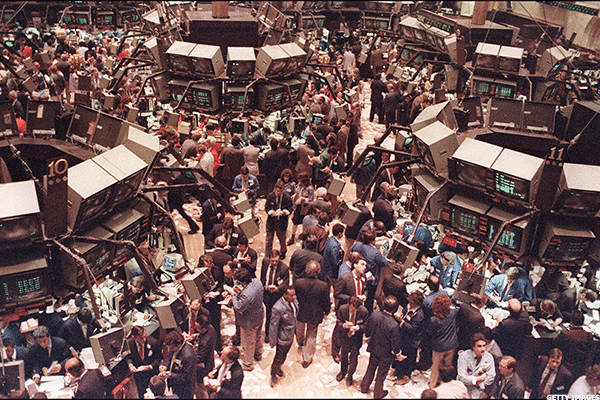
While there are some similarities to 1987, there are also some major differences.
Industrial production beats estimates, rising from a year earlier the most since September 2022, as manufacturing rebounds from August’s dip and utility output jumps to a record high led by electricity.
Fuel prices rebounded and nonfuel import prices hit their highest annual rate since April 2022, with semiconductor prices posting an eighth straight record year-over-year gain.
Here’s what I’m most concerned about the future of our economy. Also, let’s check on Warsh’s latest speech, the market rebound and the charts.
The hyperscalers pay for AI out of their own cash. The companies that borrow to build it are starting to trade like rate-sensitive stocks.
Stocks recovered from early losses as Tech bounced and the largest drop in 10- and 30-year yields in over a year saw five sectors gain over 1%.
The hot CPI report finally triggered the rotation. Breadth was the best in weeks as money moved toward the laggards.